


EN
Quarterly Earnings At TriNet Group Stock Have Changed Its Investment Story
- TriNet Group reported third quarter 2026 revenue of US$1,175 million and net income of US$31 million, and reaffirmed full year guidance for US$4,750 million to US$4,900 million in revenue and diluted EPS of US$2.85 to US$3.35.
- The quarterly figures show softer top line and profit for the period alongside higher year to date earnings. This puts more weight on how TriNet Group manages costs and pricing while targeting a full year net loss of 15%.
- We will now look at how reaffirmed full year guidance despite softer quarterly results could influence TriNet Group's investment narrative.
Compare how TriNet Group’s reaffirmed guidance stacks up against peers and scan for other companies with resilient earnings profiles using the curated 31 resilient stocks with low risk scores
TriNet Group Investment Narrative Recap
To own TriNet Group, you need to believe that demand for outsourced HR, compliance support and benefits administration stays resilient enough for the business to offset softer worksite employee volumes and elevated health costs. The reaffirmed 2026 revenue and EPS guidance, despite a weaker third quarter, suggests management still sees its current pricing and cost levers as workable.
The near term swing factor remains whether TriNet Group can stabilise volumes while keeping healthcare costs within its insurance cost ratio range. The biggest risk is that client workforce counts stay under pressure or medical inflation runs hotter than expected, which would make it harder to defend margins without straining customer relationships.
The most relevant update for this story is the third quarter and nine month 2026 result. Revenue for the quarter was US$1,175 million, lower than the same period a year earlier, while net income was US$31 million compared with US$34 million. EPS also eased slightly, which puts more scrutiny on how efficiently the model can run at this scale.
Across the first nine months, TriNet Group generated US$3,579 million of revenue versus US$3,762 million a year ago, yet net income reached US$173 million compared with US$156 million. That mix of softer top line and higher year to date earnings ties directly into the guidance reaffirmation and keeps execution on cost control, AI tools and expanded distribution as key catalysts to watch.
TriNet Group's current analyst narrative points to revenue of US$5.2b and earnings of US$164.8 million by 2029, built on forecast annual top line growth of 2.2% and a projected earnings decline of US$10.2 million from US$175.0 million today.
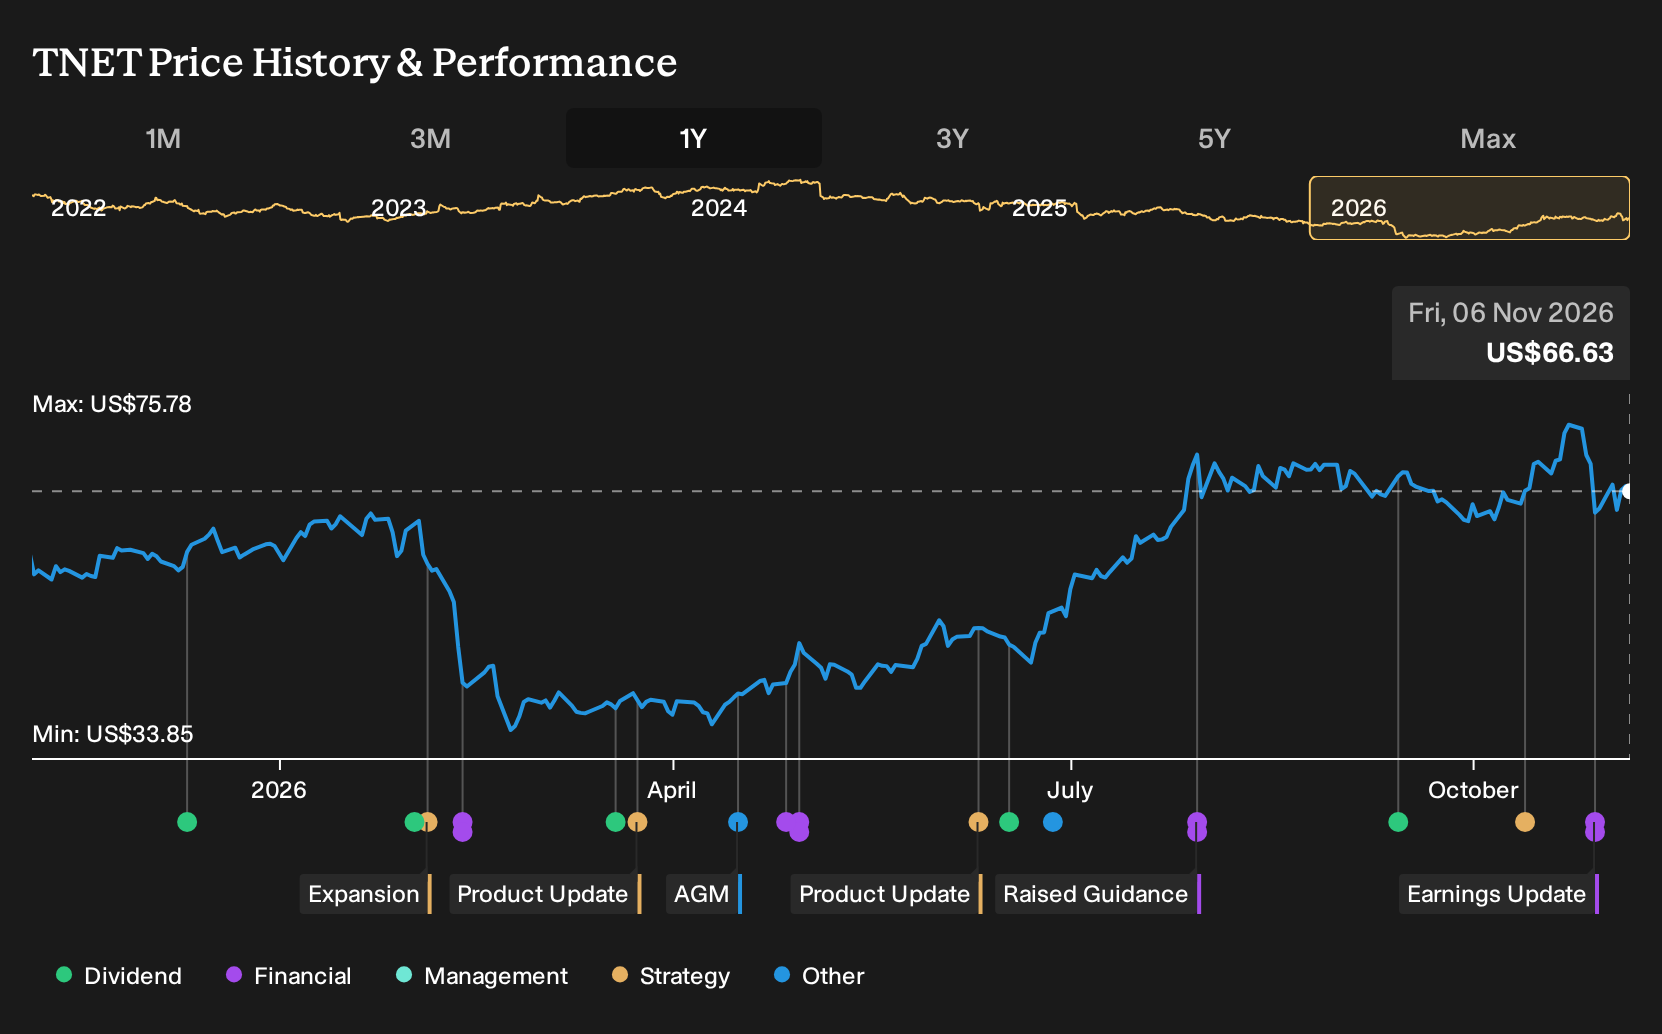
Discover how TriNet Group's fair value closely aligns with its current price.
Exploring Other Perspectives
One bullish twist on TriNet Group focuses on AI driven efficiency rather than worksite employee growth. Some of the most optimistic analysts were pencilling in 2.9% annual revenue growth and earnings of about US$204.6 million by 2029 before this reaffirmed guidance. That is far above the cautious US$164.8 million path, so views may shift as new data lands and it is worth exploring how your own expectations compare.
Explore 3 other TriNet Group fair value estimates, including one that suggests up to 273% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TriNet Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TriNet Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriNet Group's overall financial health at a glance.
Looking for more investment ideas beyond TriNet Group?
If the TriNet Group story has sharpened your thinking about risk, return and earnings quality, you can use that same lens across a wider watchlist with the Simply Wall St screener tools.
- For investors who care most about balance sheet strength and fundamental resilience, start by scanning our curated list of solid balance sheet and fundamentals (25 results) to see which businesses match that profile.
- If value is your focus and you want to zero in on companies where quality and pricing appear out of sync, take a look at the 38 high quality undervalued stocks to see which ideas fit that brief.
- To widen the opportunity set and surface potential future leaders that are not widely followed, use the 19 high quality undiscovered gems as a jumping off point for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com