


EN
Learn Why The Bull Case For COPT Defense Properties Stock Could Change Following Raised EPS Guidance
- COPT Defense Properties reported third quarter 2026 revenue of US$208.76 million and net income of US$47.74 million, with diluted EPS from continuing operations at US$0.41, and raised full year EPS guidance midpoint to US$1.44.
- The mix of higher quarterly earnings and an increased full year EPS range reflects management’s view of current leasing strength and cash flow visibility across its defense focused portfolio.
- This article reviews how COPT Defense Properties' raised full year EPS guidance may influence the existing investment narrative built around defense demand.
Scan defense focused real estate peers reacting to similar contract and leasing trends by reviewing the list of solid balance sheet and fundamentals (25 results) that meet strict financial strength filters.
COPT Defense Properties Investment Narrative Recap
To own COPT Defense Properties, you need to be comfortable tying your capital to long term demand for secure defense and IT facilities, and to a development pipeline that is mostly pre leased. The near term swing factor is whether leasing and rent collections stay firm enough to counter higher interest expense and the expected moderation in same property NOI growth.
The biggest operational risk still sits with refinancing costs and any soft patch in re leasing within the broader office exposure, especially as some tenants move out or contract. This latest earnings beat and guidance lift helps support the near term story but does not remove those funding and occupancy pressures.
The guidance revision for 2026 diluted EPS to a midpoint of US$1.44 is the clearest operational signal in this update. Management is effectively indicating that, based on signed leases and visibility into the portfolio, the business currently expects slightly stronger earnings than previously outlined, despite known headwinds from move outs and financing costs.
For short term catalysts, that updated EPS band of US$1.43 to US$1.45 for the year, and US$0.29 to US$0.31 for the fourth quarter, gives investors concrete markers to track execution. If reported results stay within or above those ranges, it supports the idea that high occupancy defense campuses and the pre leased development pipeline are doing the heavy lifting against interest expense and the idled Des Moines data center land bank.
COPT Defense Properties' current analyst narrative points to forecast revenues of US$877.7 million and earnings of US$166.3 million by 2029. This implies revenue growth of about 3.7% per year, with earnings rising by roughly US$2.8 million from US$163.5 million today to the 2029 consensus level.
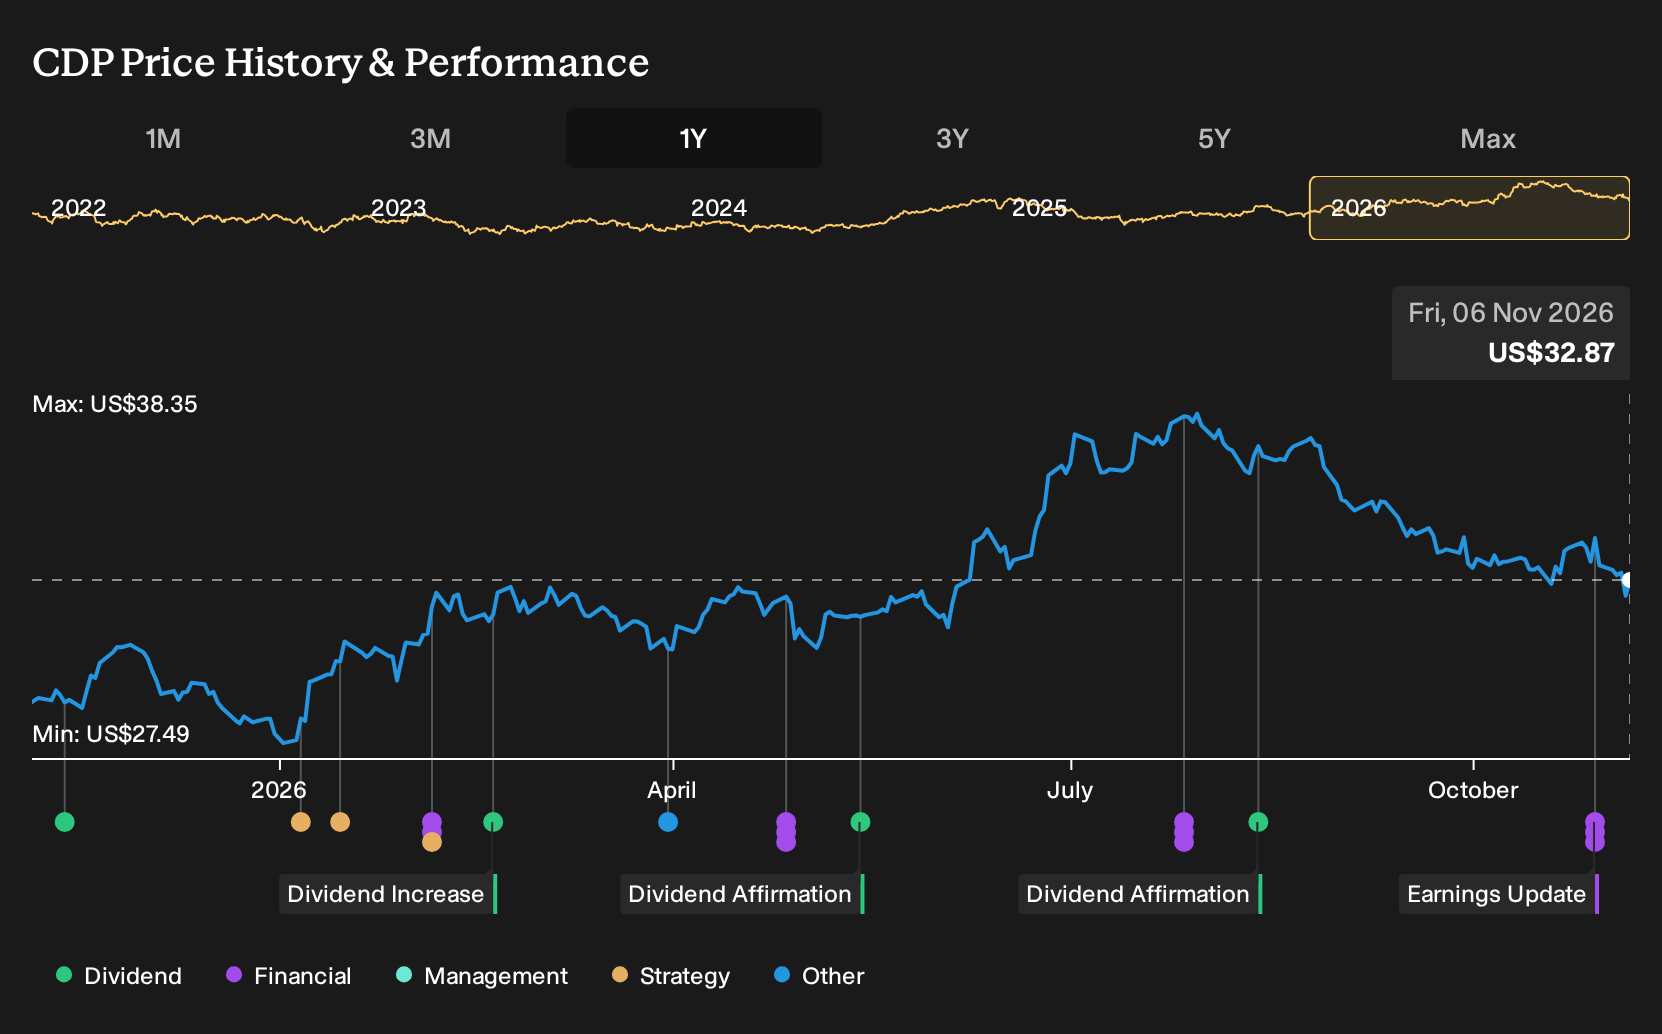
Uncover why COPT Defense Properties' fair value indicates a 21% potential upside to its current price before that discount gap begins to attract broader attention.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your COPT Defense Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for COPT Defense Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate COPT Defense Properties' overall financial health at a glance.
Looking for more investment ideas beyond COPT Defense Properties?
Once you understand COPT Defense Properties, it can be useful to compare its profile with other businesses that match different risk, income, and quality filters in the Simply Wall St Screener.
- For investors who want potential torque but still care about financial strength and balance sheet quality, scan a curated 9 elite penny stocks with strong financials that clears strict fundamentals checks.
- If the goal is to focus on quality with a margin of safety, compare COPT Defense Properties to a 38 high quality undervalued stocks that combines solid cash flows with robust financial health filters.
- Income focused readers who want to prioritise durability of payouts can compare COPT Defense Properties with a 7 dividend fortresses designed to highlight higher yielding options that pass stability screens.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com