


EN
ATCO (TSX:ACO.X) Could Be 6% Undervalued Following Earnings And Emera Merger News
Why ATCO’s latest earnings and merger news matter for investors
ATCO (TSX:ACO.X) just paired fresh Q3 2026 earnings with a planned merger with Emera, tying short term performance to a much bigger reshaping of its utility and energy infrastructure footprint.
The headline merger announcement sits on top of a quarter where adjusted earnings reached $112 million, or $1 per share, alongside reported net income of $83 million and sales of CA$1,335 million for the period.
ATCO’s latest moves are landing on a stock that has already shifted gear this year, with a 90 day share price return of 15.43% and a year to date share price gain of 50.79%. Total shareholder return over five years sits at 155.93%, pointing to momentum that has been building rather than fading as investors react to both earnings resilience and the Emera merger plan.
Spot other regulated utility and infrastructure stocks that could be setting up for their own re-rating using our hand picked 41 power grid technology and infrastructure stocks.After a 50% plus year to date run and a current price of CA$85.30, ATCO now trades between a price target of CA$92.40 and a much lower intrinsic estimate. Which anchor best reflects this move?
Most Popular Narrative: 6% Undervalued
Analyst fair value for ATCO sits at CA$91, which is modestly above the last close at CA$85.30. The current rally still tracks below that narrative anchor while the Emera deal reshapes the story in the background.
Robust long-term demand for modular and affordable housing, driven by government policy and urbanization, positions ATCO to benefit from significant infrastructure investment initiatives in Canada and internationally; recent government commitments and ATCO's scalable modular manufacturing capacity are likely to translate to higher revenue growth over the next several years.
See why 34 investors see ATCO as 6% undervalued.
Result: Fair Value of CA$91 (UNDERVALUED)
Still, higher debt needs, exposure to government budget decisions, and tougher competition in modular housing could all challenge the current ATCO narrative.
Find out about the key risks to this ATCO narrative.
ATCO valuation check: price targets vs rich earnings multiple
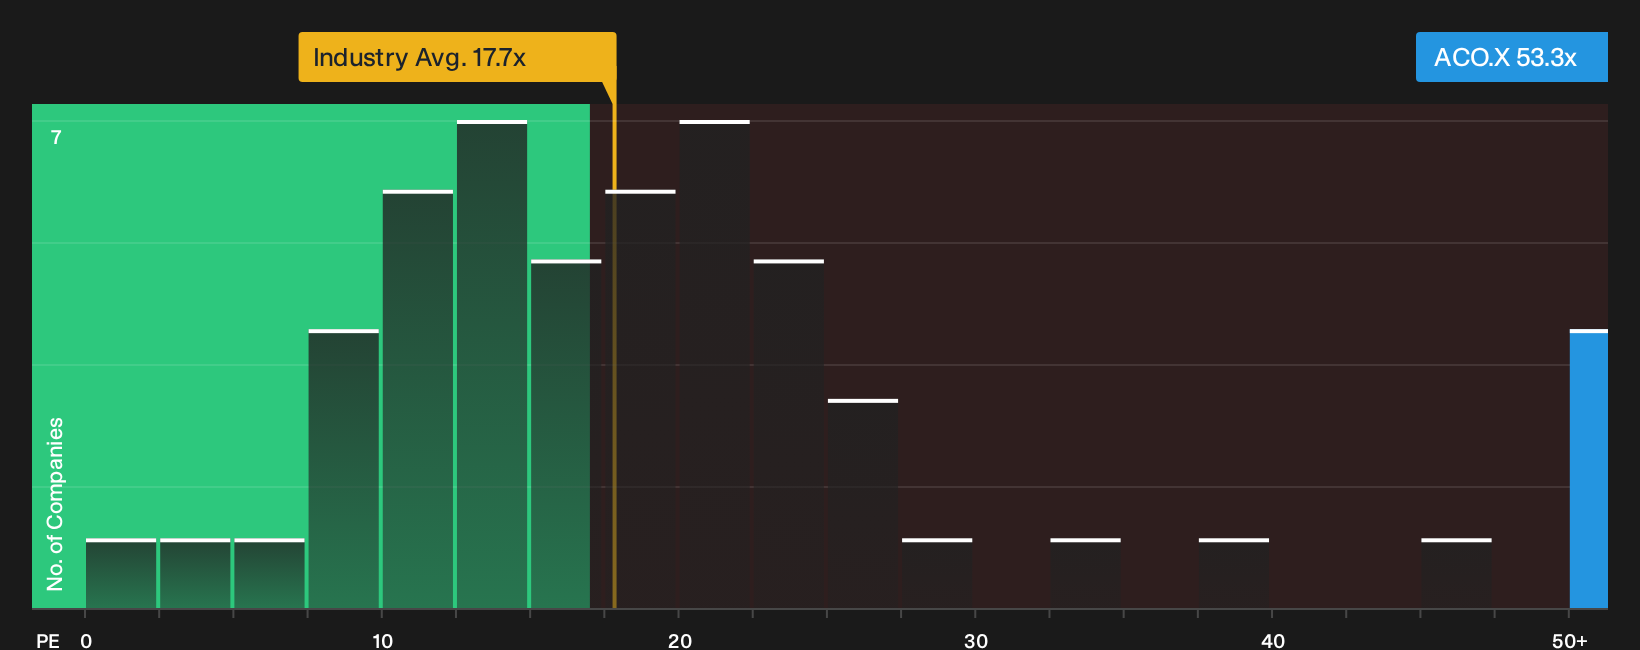
Analyst fair value of CA$91 paints ATCO as about 6% undervalued, yet the stock trades on a P/E of 53.3x. That is well above the global integrated utilities average of 17.7x and also ahead of ATCO’s own fair ratio of 44.7x. Is the story running ahead of itself, or are investors pricing in something the models miss?
Our valuation breakdown leans on this earnings multiple comparison to frame the risk that the market could move closer to that lower fair ratio if sentiment cools, even with the Emera merger on the horizon. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the story so far, with ATCO attracting both concern and optimism, make this a moment to move fast and test the data for yourself using our breakdown of 1 key reward and 3 important warning signs
Looking for more investment ideas beyond ATCO?
If ATCO has sharpened your focus on where capital could work harder next, broaden your hunt with a few focused screens that surface very different types of opportunities.
- Target durable cash flows and income resilience by scanning companies we flag as 9 resilient stocks with low risk scores that may hold up better when sentiment swings.
- Hunt for quality at a discount by running through our curated 7 high quality undervalued stocks and see which businesses trade below their implied worth.
- Spot earlier stage potential before it hits the crowd by pulling ideas from our 8 high quality undiscovered gems that pair solid fundamentals with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com