


EN
What Crédit Agricole (ENXTPA:ACA)'s Stronger Q3 Earnings Means For Shareholders
- Crédit Agricole reported Q3 2026 net interest income of €7,092 million and net income of €1,991 million, with basic EPS from continuing operations at €0.62, and for the first nine months net interest income of €21,449 million, net income of €5,718 million and EPS of €1.77.
- The group also plans to redeem its £750,000,000 senior non preferred callable fixed rate resettable notes issued in 2022, with payment scheduled for November 30, 2026. This slightly reshapes its funding mix and interest expense profile.
- Attention now turns to how this stronger quarterly profitability at Crédit Agricole may influence the existing investment narrative built around digital and capital efficiency.
Scan how Crédit Agricole’s funding and earnings story compares with other large lenders by reviewing our curated 209 resilient stocks with low risk scores, which is built around resilient balance sheets and measured risk profiles.
Crédit Agricole Investment Narrative Recap
To own Crédit Agricole, you need to believe the group can keep turning a broad, capital heavy banking model into steady earnings while managing pressure points in funding and auto finance. The recent earnings print, with €7,092 million in Q3 net interest income and €1,991 million in quarterly net income, broadly supports that operating story.
The short term swing factor is whether management can stop cost of risk and mobility financing issues from eroding that income base. The planned redemption of £750,000,000 in senior non preferred notes tidies up the liability stack a little, but it does not materially change the near term risk around provisioning or Italian exposure.
The most relevant update here is the October earnings release. Q3 net income of €1,991 million and basic EPS of €0.62, together with nine month net income of €5,718 million and EPS of €1.77, provides a current snapshot of how Crédit Agricole is funding its growth plans and absorbing regulatory, tax and credit costs.
Those figures sit alongside known pressure points. Earnings over the past year declined, net margins compressed from 27.2% to 22.8%, and mobility and auto finance are still flagged as weak through 2026. For catalysts such as digital investment, IT and AI spend, and European expansion to matter for the share price, execution has to offset those operational drags.
Crédit Agricole's current analyst storyline points to revenue of €31.4 billion and earnings of €8.5 billion by 2029, built on assumed yearly top line growth of 6.5%. That profile implies earnings would need to rise by about €2.4 billion from €6.1 billion today for the consensus case to play out.
Uncover why Crédit Agricole's fair value indicates a 33% potential upside to its current price that could narrow quickly.
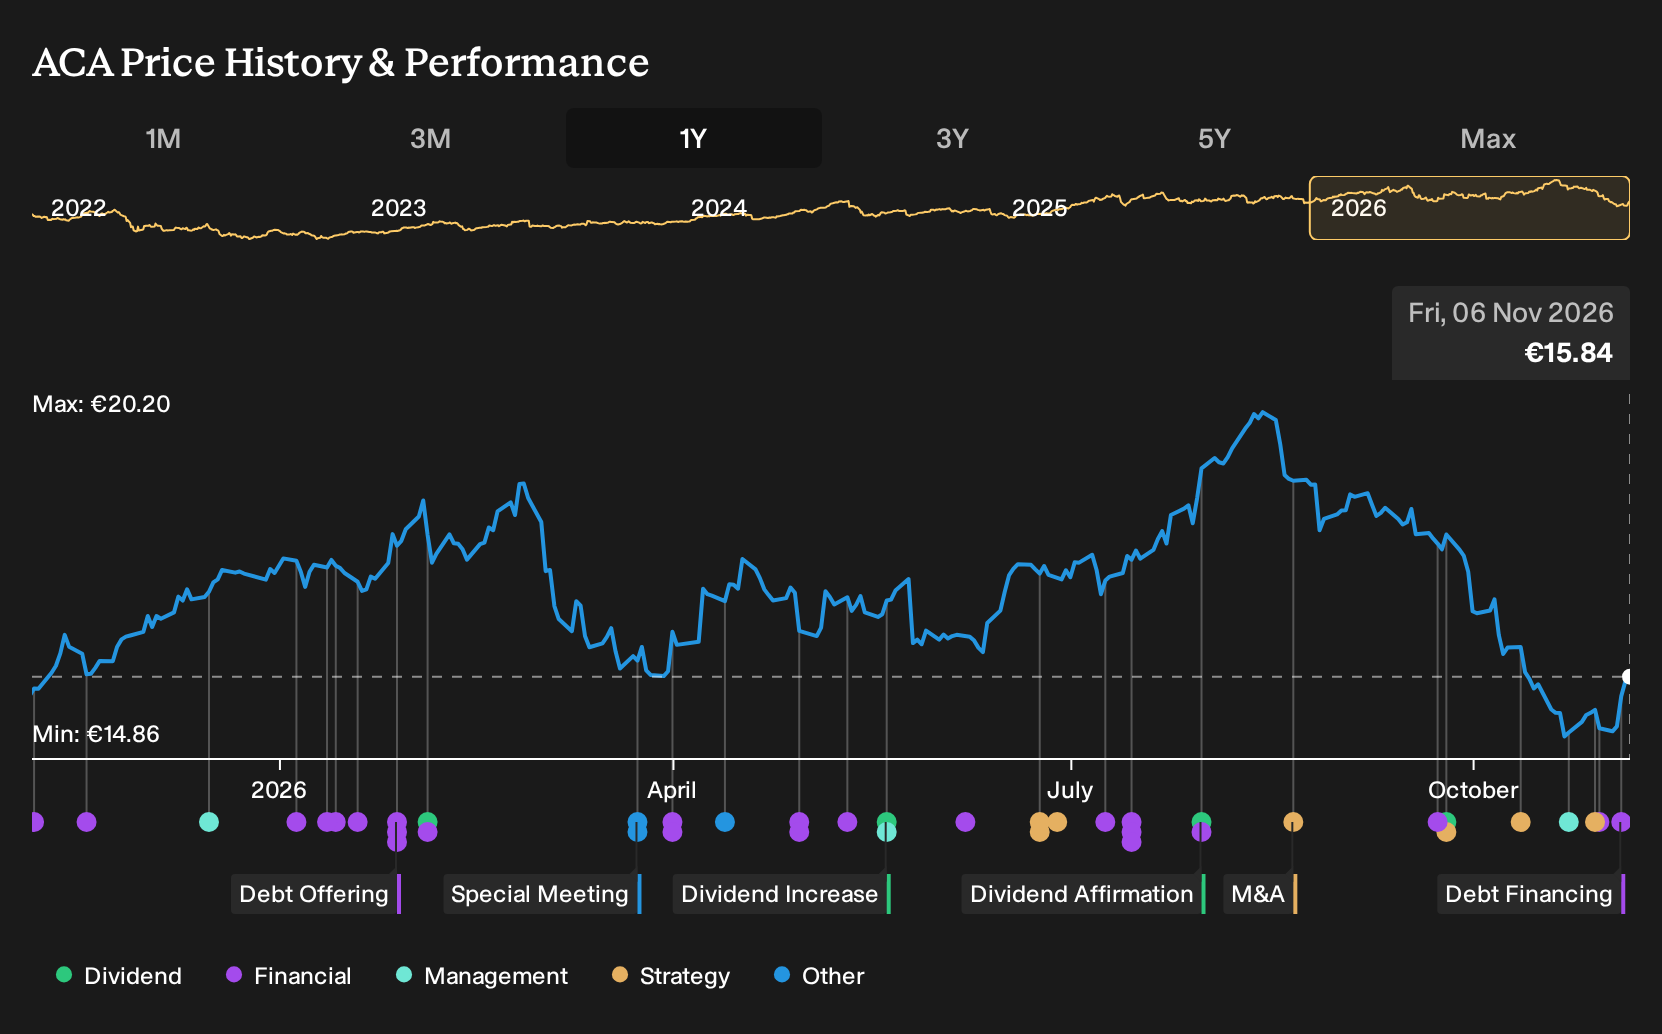
Exploring Other Perspectives
One alternate storyline around Crédit Agricole focuses on cost pressure from heavy digital and AI investment. The most cautious analysts were assuming about €31.6b of revenue and €8.2b of earnings by 2029, which already reflected concern that projects take longer to pay off. Q3 results and the planned debt redemption could shift that view, so consider several angles and assess what appears reasonable based on the available information.
Explore 4 other Crédit Agricole fair value estimates, including one that suggests it could be worth just €16.83.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Crédit Agricole research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Crédit Agricole. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Crédit Agricole's overall financial health at a glance.
Looking for more investment ideas beyond Crédit Agricole?
Once you have a view on Crédit Agricole, it can help to test that thinking against other opportunities that share similar traits or offer something quite different. The Simply Wall St Screener gives you a structured way to do that, whether you want stronger balance sheets, higher income, or under the radar potential.
- If capital preservation is high on your list, focus on resilience by scanning a curated list of solid balance sheet and fundamentals (192 results) that filters for financial strength and conservative funding profiles.
- For readers aiming to boost portfolio income, target steady cash payouts with our selection of 228 dividend fortresses that combine higher yields with a focus on sustainability.
- If you like finding opportunities before the crowd, widen your search with a hand picked 581 high quality undiscovered gems built around quality fundamentals and limited existing coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com