


EN
Atmos Energy (ATO) Following Fresh Guidance And Dividend Lift Looks Modestly Undervalued
What Atmos Energy’s latest moves signal for investors
Atmos Energy (ATO) just paired a long earnings growth streak with fresh 2027 guidance, a higher indicated dividend, and a nearly US$29b capital plan centered on safety, reliability, and Texas expansion.
For anyone tracking income and infrastructure driven utilities, that combination of updated forecasts, payout decisions, and multi year spending plans offers a clear window into how management currently views the business and its long term priorities.
Recent price action reflects that backdrop. The share price is up 7.15% over the past month and 3.16% over 90 days, while the 5 year total shareholder return of 105.41% indicates momentum that has built steadily over time as Atmos Energy rolls out its capital and dividend plans.
Scan other regulated utilities that show similar capital spending and income potential with our curated list of solid balance sheet and fundamentals (25 results) to benchmark Atmos Energy against financially resilient peers.
The recent rally and richer earnings outlook sharpen the real question around Atmos Energy. Has most of the gain already been booked at this point, or is the market still underpricing what investors are getting at US$173.22?
Most Popular Narrative: 6.6% Undervalued
On the most followed view, Atmos Energy’s fair value sits at $185.55, a shade above the last close of $173.22. This puts the recent rally in context but does not exhaust the upside implied by that narrative.
Major multiyear capital investment programs, including about US$4.2b of fiscal 2026 capex with roughly 87% to 89% directed to safety, reliability and modernization, continue to expand the regulated asset base and support future rate filings that can increase regulated revenue and operating income.
See why 16 investors see Atmos Energy as 7% undervalued.
Result: Fair Value of $185.55 (UNDERVALUED)
Still, the Atmos Energy story can shift quickly if the US$4.2b 2026 capex plan strains funding, or if legal and safety issues drive higher O&M costs.
Find out about the key risks to this Atmos Energy narrative.
Another View: Atmos Energy through the SWS DCF lens
The fair value story looks less comfortable when viewed through the SWS DCF model. At $173.22, Atmos Energy trades above an estimated future cash flow value of $135.64. This points to an overvalued signal rather than the 6.6% undervalued narrative. Which lens do you trust more when cash flow is the anchor?
To unpack how this cash flow based view is built and what would need to change for the signal to flip, Look into how the SWS DCF model arrives at its fair value.
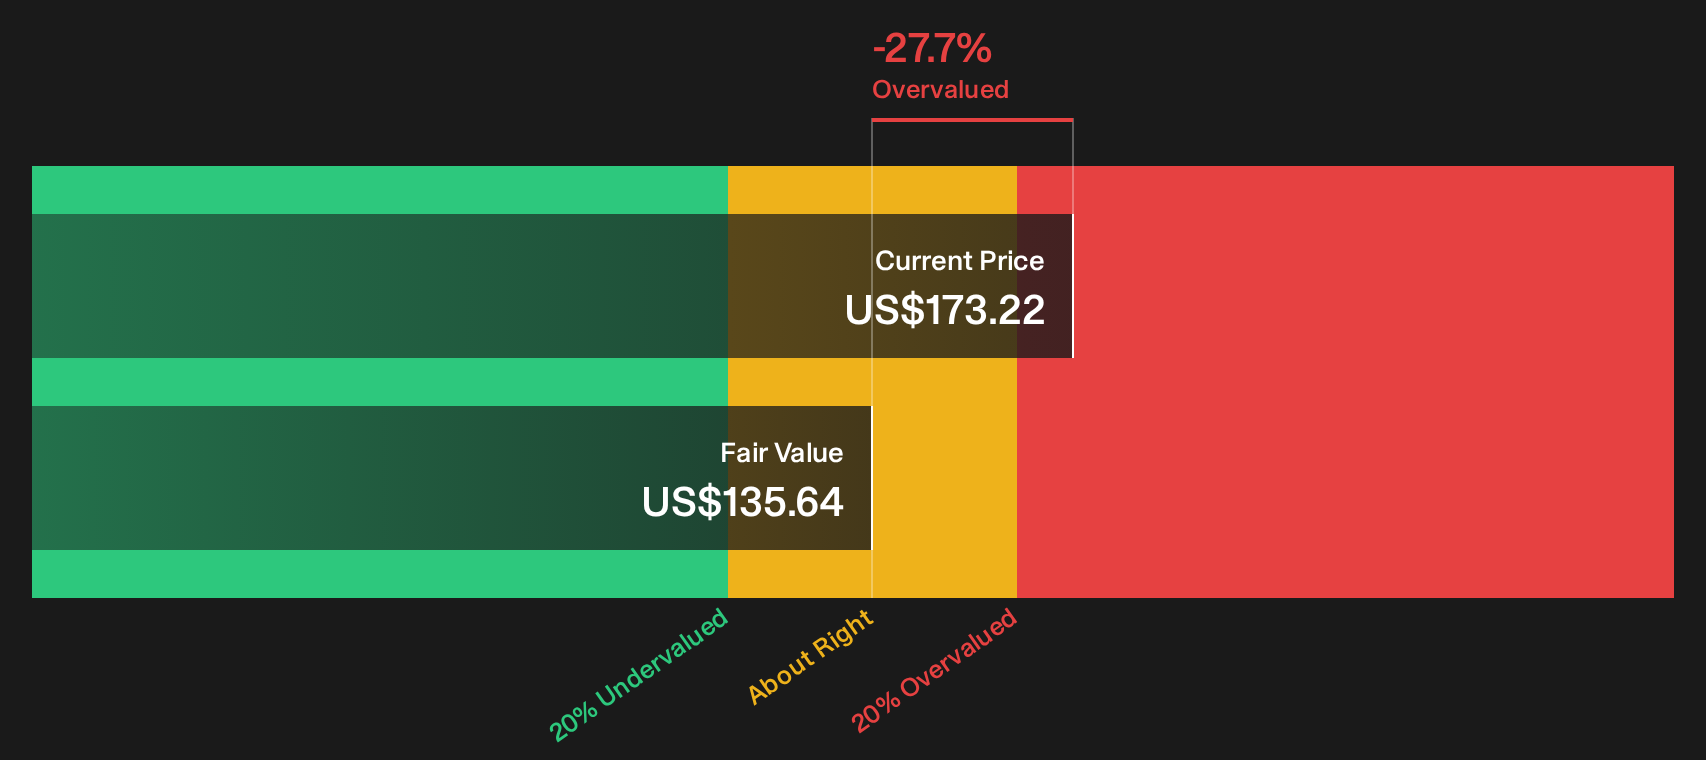
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Atmos Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Atmos Energy’s value and risk profile call for your own judgment, so move quickly through the numbers, weigh both sides, and benchmark those insights against the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Atmos Energy?
If Atmos Energy has sharpened your focus on quality and resilience, do not stop here. Broaden your watchlist now or risk overlooking your next strong performer.
- Target steady compounding by scanning companies with strong fundamentals and durable balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential value gaps by reviewing the 38 high quality undervalued stocks that match your preferred mix of quality and pricing.
- Prioritize resilience first and filter out fragile businesses with the 31 resilient stocks with low risk scores that pass strict financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com