


EN
Syensqo (ENXTBR:SYENS) Dropped, So What Is Driving Attention Now?
Syensqo (ENXTBR:SYENS) just put fresh numbers on the table, with third quarter 2026 results showing higher sales and net income year on year, giving investors new data to reassess the stock.
Recent trading shows that momentum in Syensqo has cooled a little, with the share price giving up around 5% over the past 90 days even after a 9.7% year to date share price return and a 12.32% total shareholder return over the past year. That mix suggests the market had already priced in some of the earnings progress and is now reassessing how durable this improved profitability might be.
Spot 222 high quality undervalued stocks that, like Syensqo after its latest earnings, combine improving fundamentals with prices the market may still be questioning.The earnings rebound is clear. The open question for Syensqo now is whether most of the re rating is already in the rear view mirror or if the current valuation still leaves meaningful upside on the table.
Most Popular Narrative: 7% Undervalued
On the widely followed narrative view, Syensqo's fair value of €82.40 sits modestly above the latest close at €76.70. This frames the recent earnings progress against a still cautious market price.
Structural shift towards lightweighting, electrification, and sustainable materials across mobility, aerospace, healthcare, and industrial sectors is increasing Syensqo's addressable market for high-margin specialty polymers and composites, supporting higher long-term revenue growth and resilience. Ongoing investment and operational transformation, including cost saving initiatives, organizational delayering, and portfolio streamlining after the Solvay spin-off, are producing tangible reductions in fixed cost base and improving gross and EBITDA margins. This is setting up further net margin expansion as these measures scale through 2026.
See why 8 investors see Syensqo as 7% undervalued.
Result: Fair Value of €82.40 (UNDERVALUED)
Still, the narrative can unravel if volume weakness in key segments persists and if higher input costs and tariffs squeeze Syensqo's margins more than expected.
Find out about the key risks to this Syensqo narrative.
Another Look At Syensqo’s Valuation
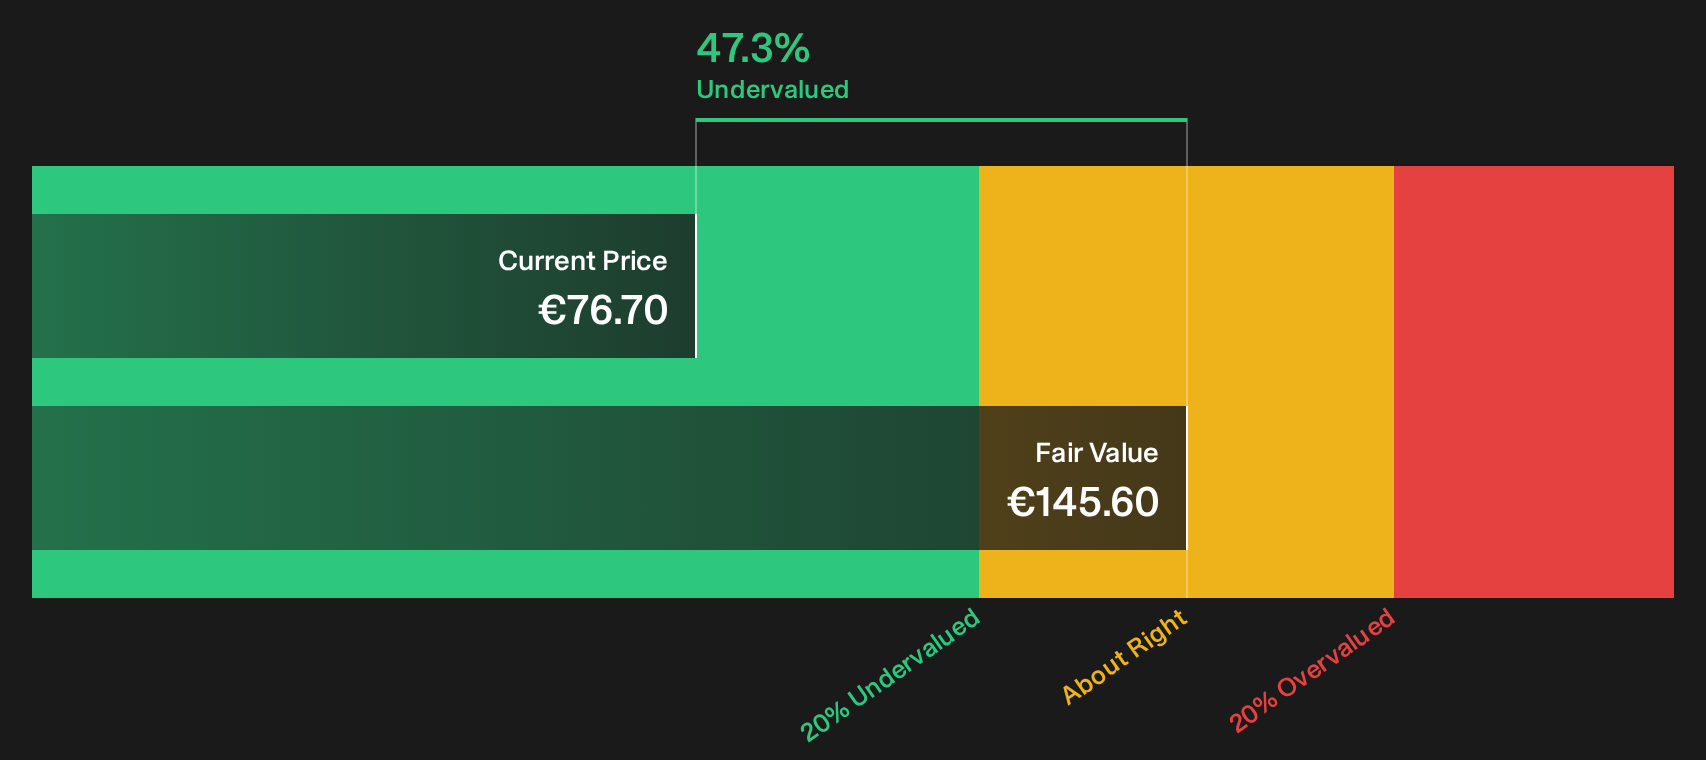
The SWS DCF model presents a very different picture for Syensqo. On that framework, the shares at €76.70 sit around 47.3% below an estimated future cash flow value of €145.60, which indicates a wide upside gap that the market has not closed yet. Which signal appears more persuasive, the cautious multiple view or the punchy cash flow story?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of caution and optimism around Syensqo leaves you on the fence, review the available data now and evaluate the story for yourself. Then round out your view by checking the 2 key rewards.
Looking For More Ideas Beyond Syensqo?
Do not stop with a single opportunity. Give yourself options by scanning wider across the market, or risk missing some of the most interesting setups on offer.
- Target resilient balance sheets and steady fundamentals by running a focused search through our list of solid balance sheet and fundamentals (192 results).
- Hunt for mispriced opportunities where quality and valuation line up using the curated 222 high quality undervalued stocks.
- Capture potential income ideas with reliable cash returns by screening for proven payers in the 228 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com