


EN
EPAM Systems (EPAM) After Earnings Beat And Buyback Plan What Valuation Looks Like
EPAM Systems (EPAM) just packed several catalysts into one session, beating its own Q3 outlook, lifting full year earnings guidance, and unveiling a large new share repurchase plan through 2029.
For context, EPAM Systems has seen a sharp swing in sentiment, with the share price rallying about 64% over the past 90 days and about 41% over 30 days, yet still sitting on a year to date share price decline of roughly 21% and a 1 year total shareholder return decline of about 9%. This suggests the latest earnings beat, guidance lift, buyback activity and activist interest have shifted expectations without fully erasing longer term losses.
Surf 38 high quality undervalued stocks that, like EPAM Systems after this earnings surprise and buyback announcement, pair solid balance sheets with potential mispricing.The share price now trades close to analyst targets, yet still appears to be at roughly a one third discount to one intrinsic value estimate. Where does fair value for EPAM Systems really sit across that spread?
Most Popular Narrative: 40.5% Overvalued
EPAM Systems closed at $159.31, while the most followed narrative pegs fair value at $113.38. This implies a steep premium and frames the current rally as excessive according to that lens.
EPAM Systems has long been a darling of the IT services world, but a convergence of structural dangers suggests the stock may be worth half its current value. Three unaddressed red flags point to a brutal de-rating ahead.
See why 4 investors see EPAM Systems as 41% overvalued.
According to Westminster, the narrative applies an 8.63% discount rate and argues that heavy macro headwinds, talent disruption in key engineering hubs, and a lack of proprietary compute assets could weigh on EPAM Systems. That view stands in sharp contrast to the SWS DCF output, which points to good value based on future cash flow estimates and implies the shares trade at a discount to that model.
This clash between a $113.38 narrative fair value and a higher $242.69 future cash flow estimate leaves investors balancing structural risk concerns against quantitative indications of undervaluation. The result is a wide valuation band around EPAM Systems that depends heavily on how much weight you give to macro pressure, talent mix shifts, and EPAM's role in the AI stack.
Result: Fair Value of $113.38 (OVERVALUED)
Still, if EPAM Systems stabilises key engineering hubs or starts to monetise its AI and data capabilities more effectively, this harsh narrative could soften.
Find out about the key risks to this EPAM Systems narrative.
Another View: EPAM Systems Through Earnings Ratios
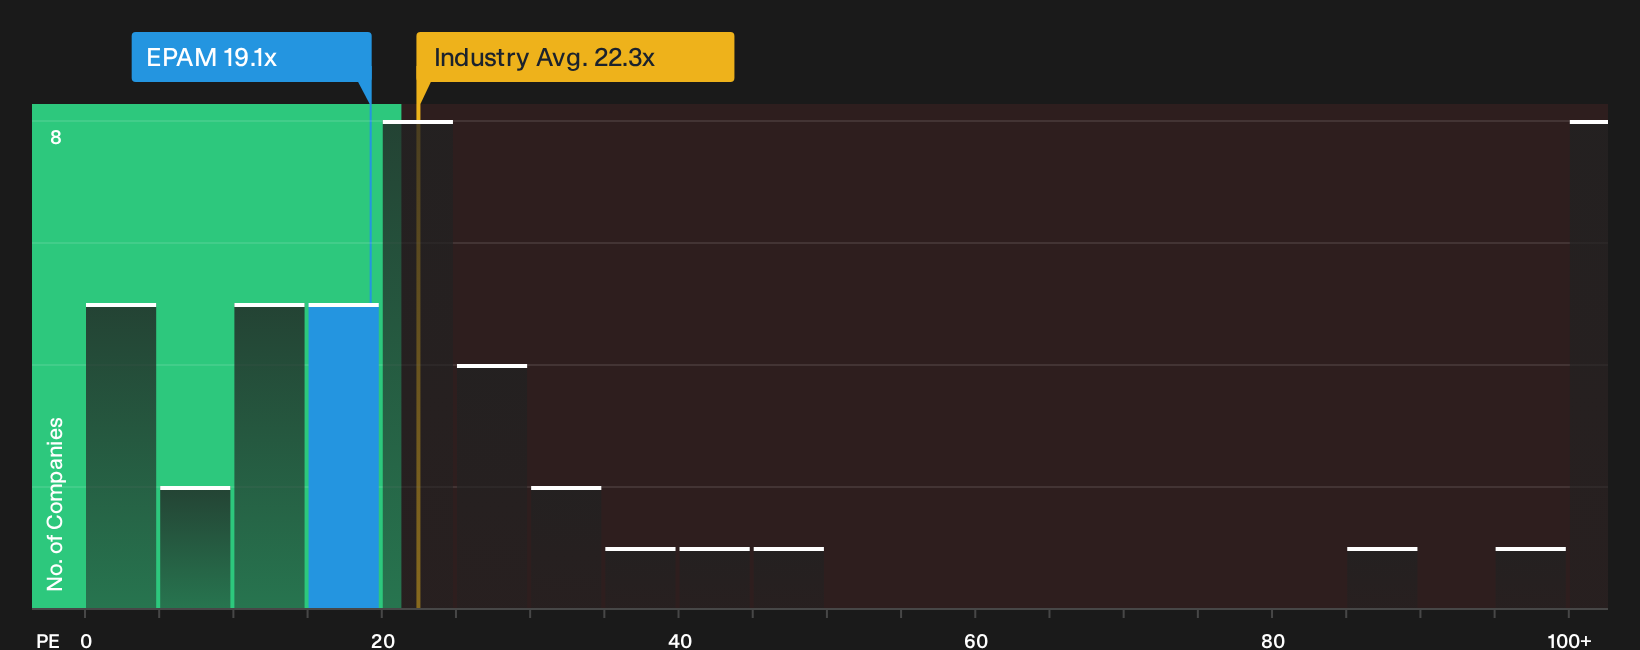
A very different picture emerges when you look at EPAM Systems through earnings multiples instead of narrative fair value. The shares trade on a P/E of 19.1x, while peers sit around 21.2x, the wider US IT industry around 22.3x, and the fair ratio is 27.7x.
That gap suggests the market prices EPAM at a discount to both similar companies and a level the fair ratio points to as a possible destination. This can indicate either a margin of safety or a signal that investors still worry about long term risks. Which side of that line do you think the stock belongs on over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on EPAM Systems is split, which is exactly why your own work matters most right now. Act quickly and pressure test both the risks and the potential upside using the 4 key rewards.
Looking for more EPAM Systems style opportunities
If EPAM Systems has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist and pressure test fresh ideas now.
- Spot potential mispricing early by reviewing the 19 high quality undiscovered gems that combine strong fundamentals with lower market attention.
- Strengthen downside protection by scanning the list of solid balance sheet and fundamentals (25 results) so you focus on businesses with robust financial footing.
- Dial back volatility risk by filtering for the 31 resilient stocks with low risk scores that score well on resilience and financial quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com