


EN
Why IMCD (ENXTAM:IMCD) Is Getting Attention Today
IMCD event puts recent performance in focus
IMCD (ENXTAM:IMCD) has drawn fresh attention after reporting 9% constant currency gross profit growth and 11% EBITA growth for the first nine months of 2026, with organic gross profit growth reaching 10% in Q3.
At a share price of €102.75, IMCD has logged a 31.39% year-to-date share price return. The 1-year total shareholder return of 26.19% contrasts with a 3-year total shareholder return decline of 14.68% and a 5-year total shareholder return decline of 44.29%, suggesting that recent momentum has picked up after a weaker longer period.
Scan how IMCD's momentum and cash generation stack up against peers by reviewing our hand picked list of 222 high quality undervalued stocks with resilient balance sheets and solid cash flow profiles.
Bulls point to IMCD's recent profit growth, cash generation and balance sheet improvement. Bears highlight the weak 3 and 5 year returns. The key question is which side the current valuation supports next.
Most Popular Narrative: 12% Undervalued
IMCD's most followed narrative points to a fair value of €117.36 compared with the latest close at €102.75, which puts the current share price at a material discount and frames recent momentum against a longer term cash flow story.
The asset light model with low capex and high cash conversion, illustrated by free cash flow of €222 million in H1 2026 and 91.4% cash conversion in 2025, positions IMCD to keep generating surplus cash that can be used for M&A, deleveraging or shareholder returns, which ultimately feeds into equity value and earnings per share.
See why 13 investors see IMCD as 12% undervalued.
Result: Fair Value of €117.36 (UNDERVALUED)
Still, currency swings that have already reduced EBITA and renewed pricing pressure from local and Chinese competitors could quickly challenge the current IMCD undervaluation story.
Find out about the key risks to this IMCD narrative.
Another View: IMCD on earnings multiples
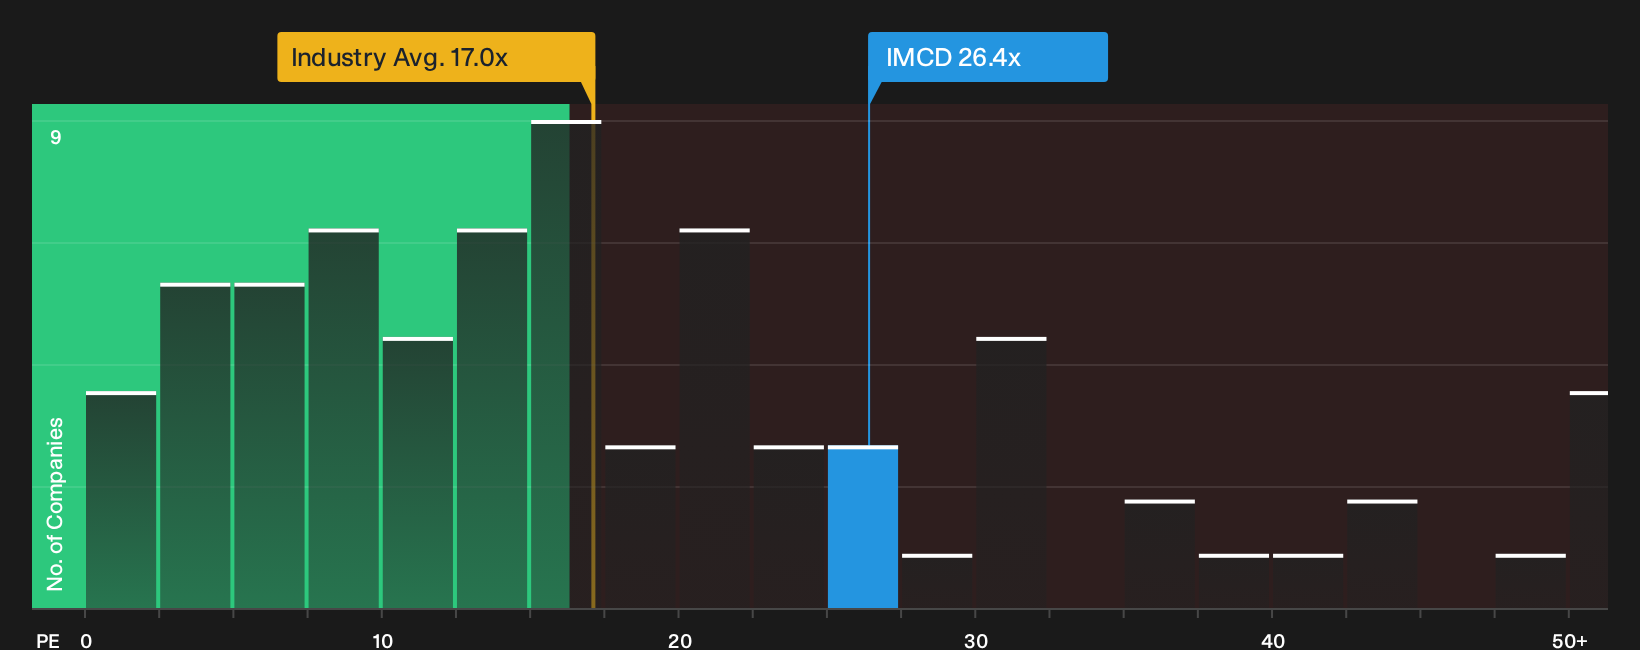
There is a different read on IMCD when you swap the cash flow lens for a simple earnings multiple. The shares trade on a P/E of 26.4x, compared with 17x for the European Trade Distributors group and a fair ratio of 17.1x. This points to a rich tag that could compress if sentiment cools.
That kind of premium can reflect confidence in IMCD's model. It also raises the question of how much upside is already baked into the current price and how much room is left if expectations slip or rates stay higher for longer, especially when peers and the fair ratio both cluster around 17x. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on IMCD so far. If you care about both the upside case and the risk list, start weighing the numbers for yourself and then check the 2 key rewards and 1 important warning sign.
Looking for more IMCD investment ideas?
If IMCD has your attention, do not stop here. Broaden your watchlist with a few focused screens and give yourself more options.
- Hunt for potential mispricing by scanning a curated 222 high quality undervalued stocks that combine solid fundamentals with room for re rating.
- Build a steadier income stream by reviewing a focused set of 228 dividend fortresses that emphasise resilience alongside yield.
- Strengthen your defence by checking a 209 resilient stocks with low risk scores that filters for robust balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com