


EN
Should Single Use Ventilator Sensor Launch Require Action From Sensirion Holding (SWX:SENS) Investors?
- Sensirion Holding announced global availability of the single-use SFM3304-D gas flow sensor for proximal flow measurement in mechanical ventilation, smart resuscitation, and medication nebulization, featuring an updated sensor chip, improved performance characteristics, and contamination-protected packaging suitable for sterilization.
- The shift to a single-use, globally distributed sensor that is a pin-compatible successor to the SFM3300-D underscores Sensirion Holding's focus on higher-specification medical devices that can integrate into existing equipment designs while addressing hygiene, regulatory, and usability requirements in critical care settings.
- The following section examines how Sensirion Holding's investment narrative relates to the global rollout of its new single-use SFM3304-D sensor.
Sensirion Holding Investment Narrative Recap
Sensirion Holding may appeal if you think a focused sensor specialist can keep finding new, regulated use cases while managing currency swings, industrial normalization, and a relatively high P/E of 41.7x. The story leans on forecast revenue growth of 9.4% a year and expected earnings growth of 15.2% a year, with margin progress already visible.
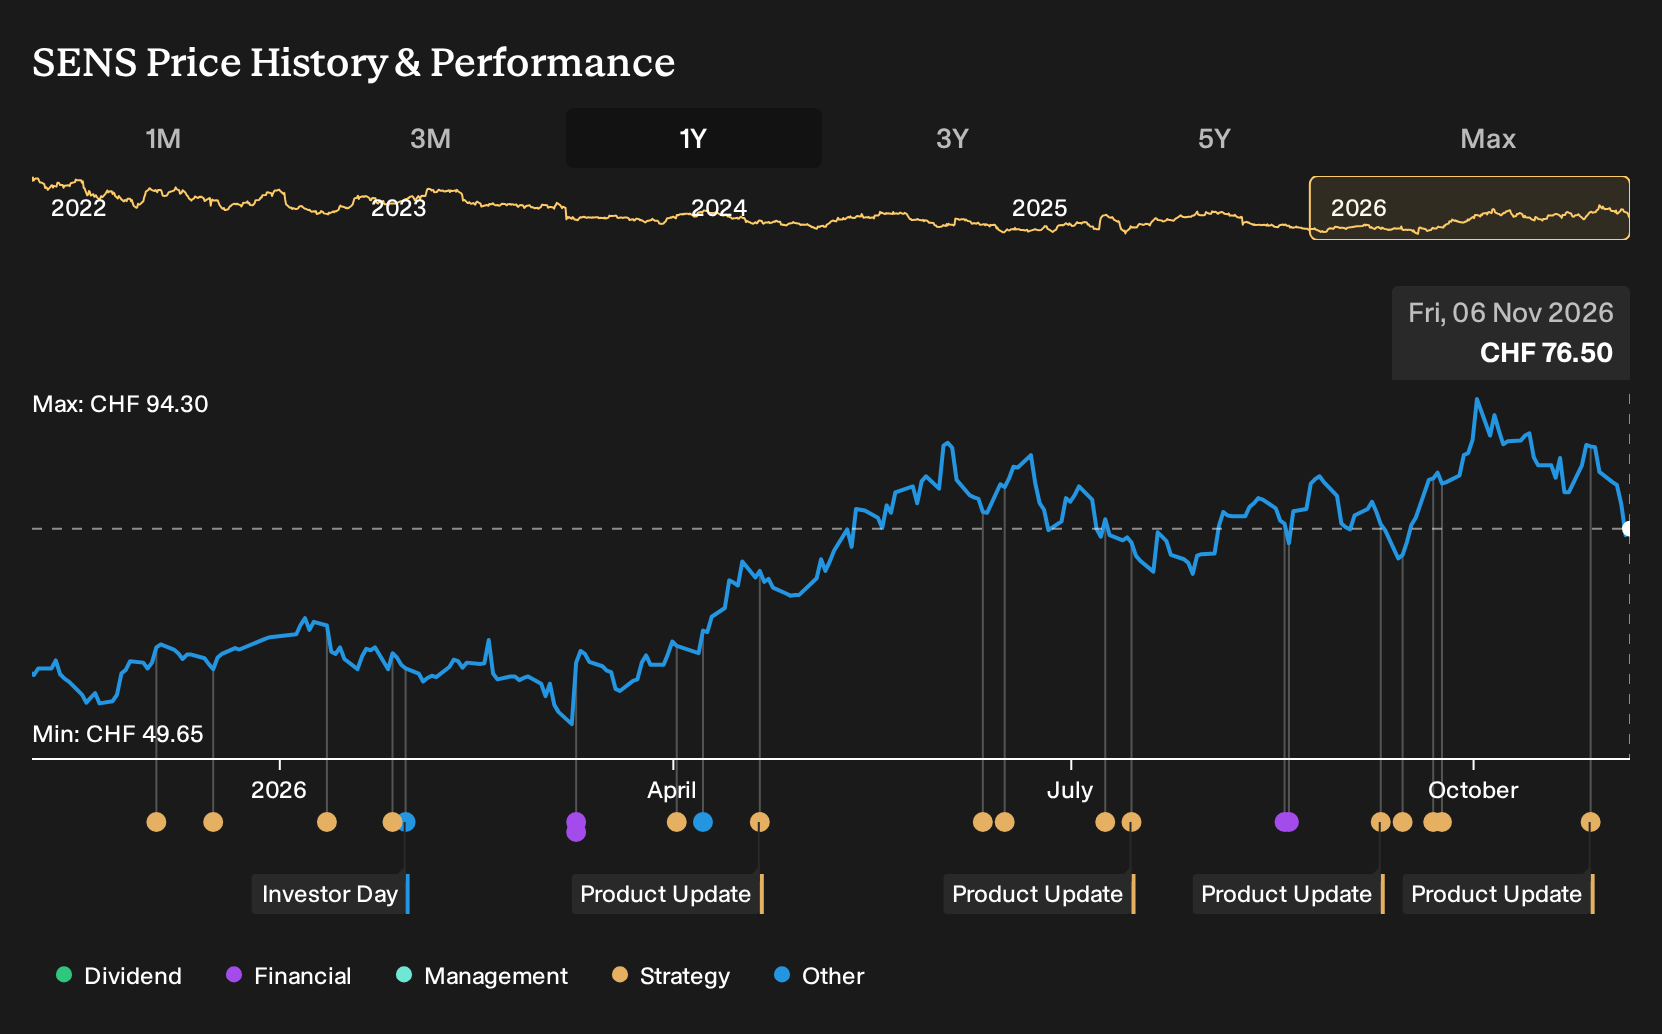
The near term hinge point is whether fresh products in medical, HVAC and environmental sensing offset tapering A2L ramp up and any softer automotive or China related demand. Currency exposure and a volatile share price remain key risks. The latest SFM3304 D launch does not drastically change that balance on its own.
The SFM3304 D rollout is the clearest operational link to the current catalyst debate. Sensirion Holding is trying to broaden its mix into medical and environmental applications where regulation, hygiene and data accuracy matter, and where its CO₂ and flow sensor know how already underpins the narrative of higher quality, potentially more recurring revenue streams.
For you as a shareholder, the question is whether this kind of medical hardware design in can scale fast enough to counteract normalization in industrial sensors and any pressure from tariffs or weaker automotive demand. Execution on this new single use platform, combined with what management shares at the November 2026 ZKB Swiss Equity Conference, may shape how credible those growth forecasts look.
Sensirion Holding's narrative projects CHF 437.5 million revenue and CHF 42.5 million earnings by 2029. This aligns with analyst expectations of 9.1% yearly revenue growth and an earnings increase of about CHF 13.9 million from CHF 28.6 million today.
Uncover why Sensirion Holding's fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between CHF 57.09 and CHF 88.60, which is a wide span for the same Sensirion Holding equity story. Those private forecasts sit beside concrete catalysts such as the SFM3304 D launch and the November 2026 ZKB conference. At the same time, currency and tariff risks keep opinion gaps wide. Explore the different viewpoints before deciding how you frame this stock.
Explore 2 other Sensirion Holding fair value estimates, including one that suggests there could be as much as 25% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Sensirion Holding research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sensirion Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sensirion Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sensirion Holding?
If you want to stress test your view on Sensirion Holding, it can help to line it up against other businesses with different risk and income profiles using the Simply Wall St Screener.
- Prioritise financial resilience and see which companies show consistently strong balance sheets through our list of solid balance sheet and fundamentals (192 results).
- If you care most about quality at a reasonable price, compare Sensirion Holding with a 222 high quality undervalued stocks based on fundamentals.
- For investors who want income potential alongside capital growth, scan for 228 dividend fortresses that might suit a yield focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com