


EN
JFrog (FROG) Stock Looks Fully Priced As Its 287% Run Continues
JFrog has been on a powerful multi‑year run, and the question now is whether the cash the business can generate really backs up the current share price. With the stock closing at US$100.98 most recently, investors are increasingly asking what its cash flows are worth when put through a rigorous Discounted Cash Flow (DCF) lens.
- Over the past 3 years the stock has returned 286.9%, which puts a lot of accumulated optimism on the line if the underlying cash generation does not keep pace.
- Recent headlines around rapid cloud demand and AI driven software activity suggest investors may be baking in expectations for stronger and potentially faster arriving cash flows than in the past.
- What if you looked at JFrog through its sales instead? See what JFrog's 19.4x P/S says about the price.
The stock's next move may depend on whether the current share price is broadly in line with what its future cash flows imply when run through a Discounted Cash Flow (DCF) view of intrinsic value.
If you want to test this same cash flow question across other AI exposed software players, apply the valuation lens to 40 AI small caps.
Is JFrog Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) model here projects what JFrog might generate in cash and then discounts those streams back to today. Latest twelve month Free Cash Flow sits at about $209.5 million, and the projection set has it rising into the low to mid hundreds of millions of dollars over the coming decade, which assumes a business that keeps building on its current footing rather than stalling out.
Those rising Free Cash Flow estimates still leave JFrog trading at a level where the DCF view comes in meaningfully below the current share price of $100.98. The recent “blowout” Q3 2026 print, helped by AI driven coding activity and a large SaaS deal, helps explain why the market is willing to pay more for the stock than the cash flow model supports right now. Find out what JFrog could be worth using our Discounted Cash Flow (DCF) estimate.
The JFrog Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the JFrog valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price, and they sit on the platform's Community page. Rather than focusing on a single multiple or model snapshot, each scenario lays out the key drivers behind its fair value view so you can compare those inputs with JFrog's actual results as they come through.
One of the top community narratives on JFrog: 11% undervalued
"The main thing that has to go right is that JFrog continues to convert the AI fueled demand for binaries and software supply chain security…"
Discover why this Narrative puts JFrog at 11% undervalued.
One more JFrog check that can change the story
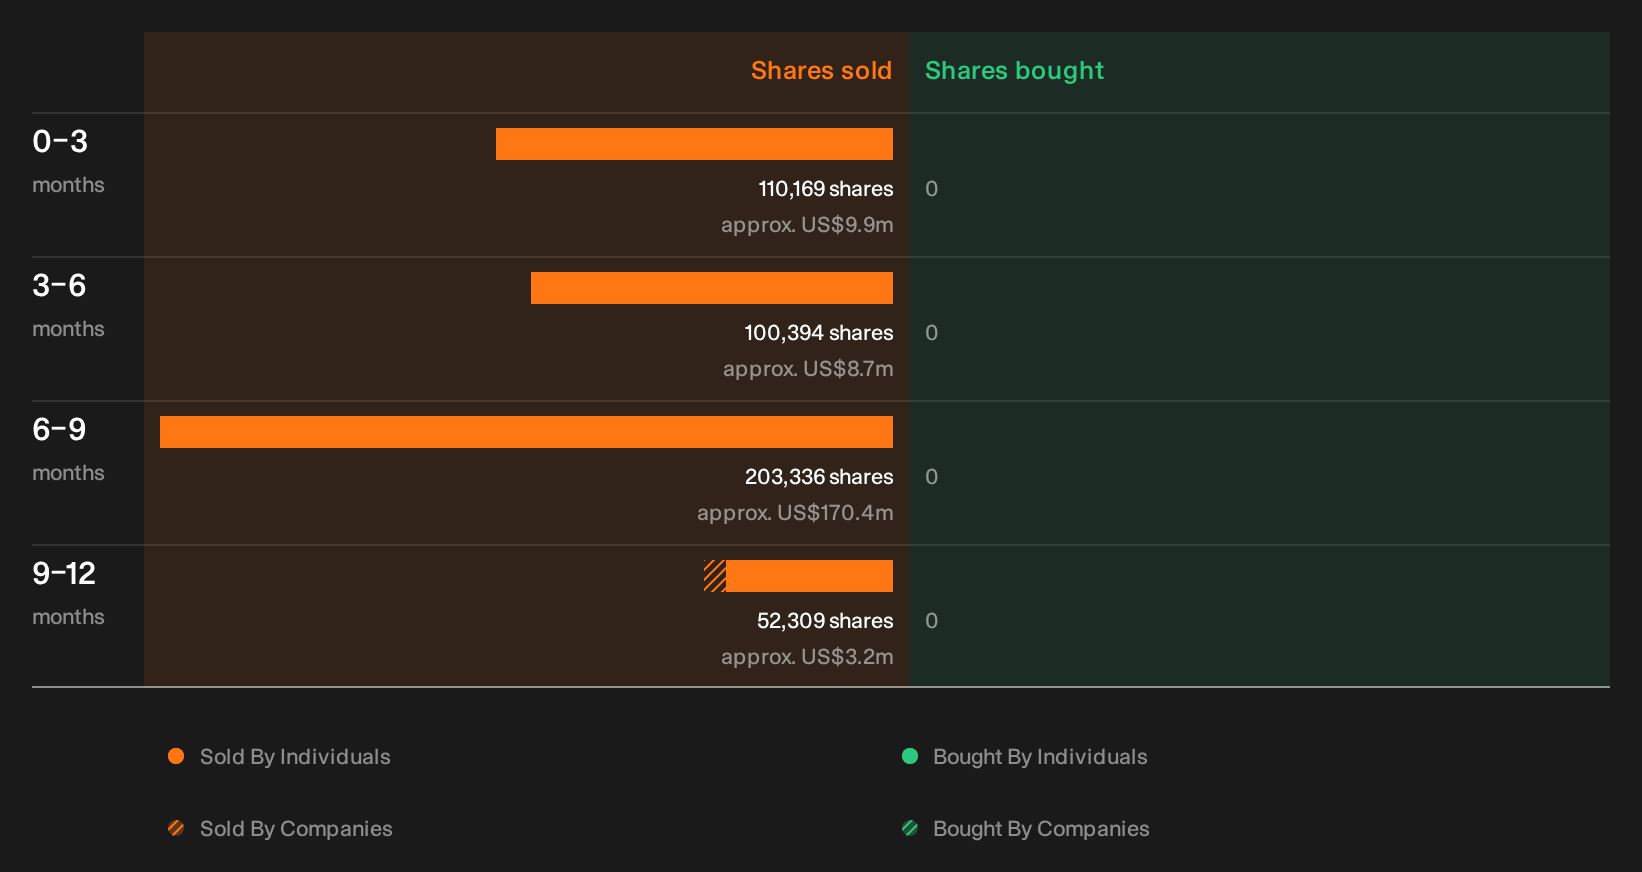
DCF models focus on cash flows, but ownership moves can quietly reshape the risk picture, and recent selling activity by people inside JFrog is the next piece to review before you decide what the story really is. See the recent insider selling flagged for JFrog.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com