


EN
3 Australian Undervalued Stocks For November 2026
Higher interest rates are keeping global borrowing costs elevated, which puts cash flow under a brighter spotlight for Australian investors. Reliable cash generation can matter more when cheap money is off the table, especially if the market price does not fully reflect that strength. This article walks through three Australian stocks that currently look mispriced against their future cash streams, all filtered by a rigorous discounted cash flow approach.
The three stocks covered below are just a starting sample, since the full screen surfaced three more companies with equally cash rich potential and valuation stories that are not covered here.
If you want to identify and analyze those extra opportunities with the same cash flow lens, head straight into the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner focused on developing the Havieron project in Western Australia to support future cash flows.
Operations: Greatland Resources generates about A$2.3b in revenue from the Telfer Havieron segment, reflecting its concentration in that integrated operation.
Market Cap: A$6.9b
Greatland Resources is included in this cash flow focused screen because Havieron represents a potential transition from exploration-focused activities to production-backed, recurring cash generation.
"The primary driver of Greatland’s outlook is the gold price. As a single-asset developer moving toward production, its operational performance is closely tied to movements in the gold price."
Even a small change in a key input cost or price assumption in a cash flow model can materially alter the anticipated margin profile.
Those small shifts in assumptions can matter a lot, so read the full narrative for Greatland Resources to see how Greatland Resources’ cash story could decouple from simple gold price moves.
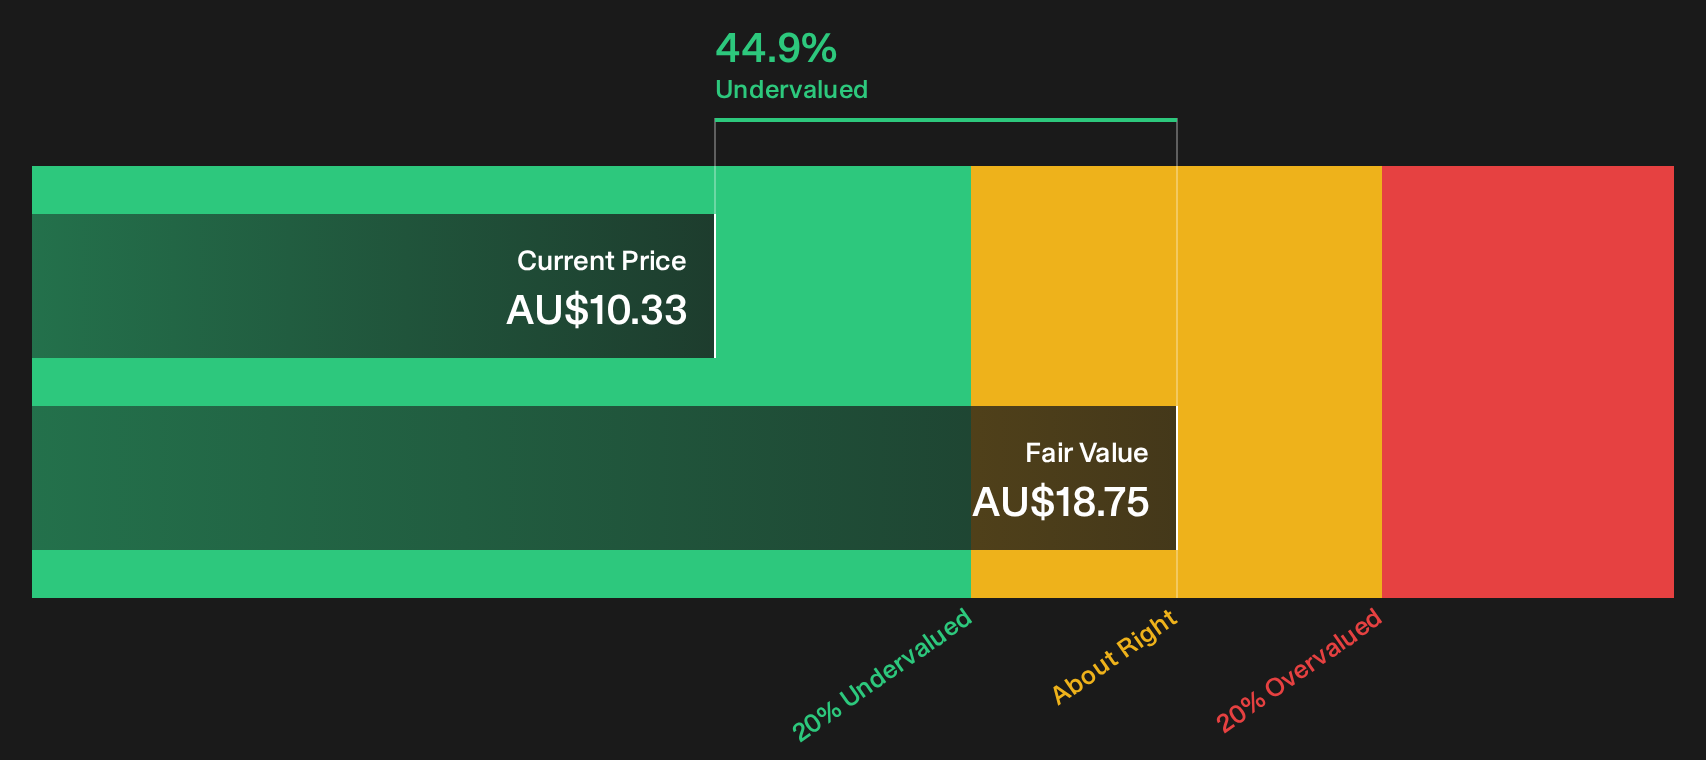
Ansell (ASX:ANN)
Overview: Ansell supplies medical and industrial protective gloves and clothing, with recurring healthcare glove sales anchoring the cash-flow theme.
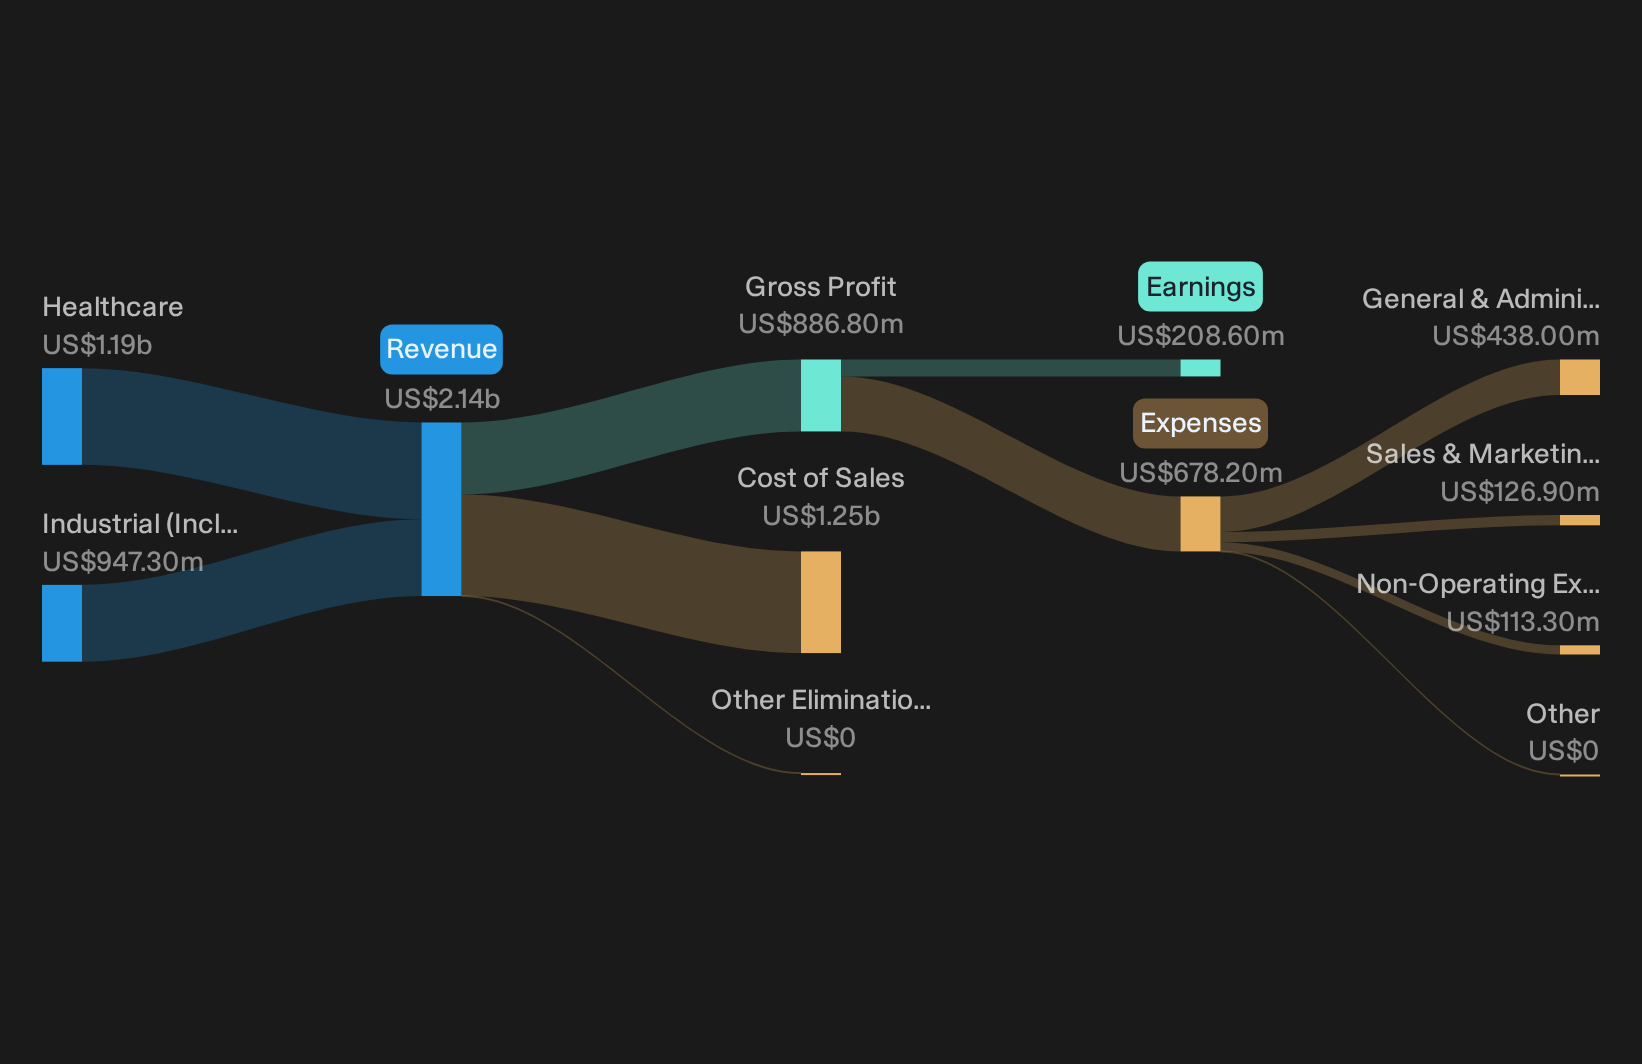
Operations: Ansell generates US$1.2b from Healthcare and US$947 million from Industrial, supported by broad international sales across North America and Europe.
Market Cap: A$6.3b
Ansell matters for this cash flow focused screen because its Healthcare glove business sells essential, repeat-use PPE that can support steady, model-friendly cash streams across economic cycles.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets. Volatility in raw-material prices (nitrile, latex, energy), freight disruptions, and trade or tariff risks can pressure margins."
What happens to those cash-rich glove earnings if a single unseen pressure quietly reshapes the cost base investors are assuming today?
When those input pressures start to quietly shift, the full narrative for Ansell shows how Ansell’s cash engine could accelerate or stall in ways headline earnings barely reveal.
Origin Energy (ASX:ORG)
Overview: Origin Energy is an integrated utility that sells electricity and gas, while its Integrated Gas and LNG assets anchor long term cash flows.
Operations: Origin Energy generates about A$15.3b from Energy Markets and A$307 million from Integrated Gas, indicating a primarily domestic retail and wholesale cash engine.
Market Cap: A$20.8b
Origin Energy matters for this cash flow focused screen because the Integrated Gas and LNG business supplies relatively steady cash generation that supports discounted cash flow value upside alongside its broader electricity and retail operations.
"Continued growth in rooftop solar, home batteries and the 1.6 GW virtual power plant, supported by rising adoption of customer electrification products, can shift more consumption behind the meter and reduce grid supplied volumes."
The real swing factor is how one key pressure on long term returns ultimately feeds through to margins investors are counting on.
That pressure point is exactly where the full narrative for Origin Energy maps how Origin Energy’s cash flows could decouple from headline volumes and where the upside still hides.

Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. Once the breakout momentum is obvious, the best entry points can be gone. Scan these under the radar picks before the crowd and consider your options.
- Track durable income streams and stress test payout safety across a curated set of yield opportunities through the 5 dividend fortresses.
- Spot early breakout potential in lesser known operators with strong finances by using the curated 14 high quality undiscovered gems.
- Explore structural shifts in power demand with a focused group of grid enablers using the targeted 41 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com