


EN
Badger Meter (BMI) Wins An Argus Upgrade, Is The Valuation Already Priced In?
Argus recently upgraded Badger Meter (BMI) to a BUY rating, highlighting its water meter technologies, software services, and flow instrumentation offerings for municipal and industrial customers as key drivers of analyst optimism.
Recent trading has been lively for Badger Meter, with a 30-day share price return of 20.4% and a 90-day gain of 15.9%, building short term momentum even though the year to date share price return is down 10.3% and the 1-year total shareholder return is lower by 14.8%.
Scan other water and infrastructure plays showing similar analyst interest by reviewing the curated 41 power grid technology and infrastructure stocks, which is aligned with Badger Meter's metering and utility focus.
After a sharp rebound and an Argus upgrade, Badger Meter now trades only slightly below the average analyst target, while one valuation model points to a premium. Where does a reasonable fair value anchor actually land in that spread?
Most Popular Narrative: 3.4% Undervalued
Badger Meter last closed at $158.18, a touch below the most widely followed narrative fair value estimate of $163.78, which uses an 8.7% discount rate and long run earnings assumptions to frame upside as modest rather than dramatic.
Balanced capital allocation, including roughly US$400 million deployed on acquisitions over five years, continued R&D focused on ultrasonic metering and cellular AMI, a renewed US$150 million undrawn credit facility and an active share repurchase program with about US$90 million remaining, gives Badger Meter financial flexibility to continue compounding revenue and to protect EBITDA margin and cash conversion even through periods of uneven project pacing.
See why 13 investors see Badger Meter as 3% undervalued.
Result: Fair Value of $163.78 (UNDERVALUED)
Still, the Badger Meter story could be knocked off course if large AMI and sewer projects ramp more slowly than expected, or if legal actions tighten management’s flexibility.
Find out about the key risks to this Badger Meter narrative.
Another View: DCF Says Badger Meter Screens As Expensive
The popular narrative pegs Badger Meter at a fair value of $163.78, which points to modest undervaluation. Our DCF model tells a different story. On a future cash flow basis, the estimate sits at $135.91, which puts the recent $158.18 price in clearly overvalued territory. Which lens do you trust more for a long term hold?
To see how this clashes with the more upbeat fair value story, Look into how the SWS DCF model arrives at its fair value.
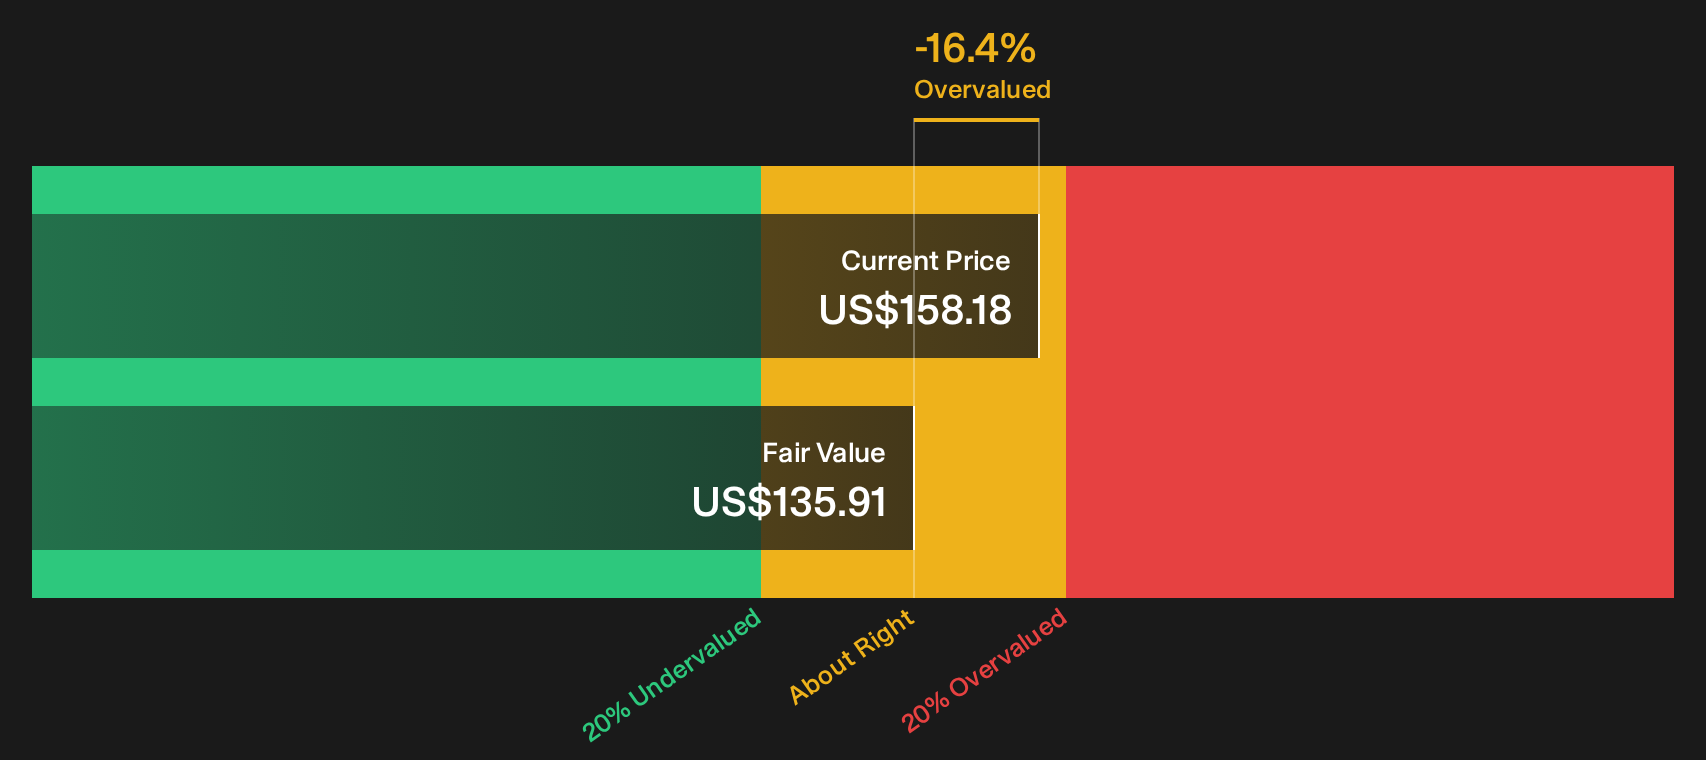
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Badger Meter for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Badger Meter is mixed enough that it pays to check the underlying numbers yourself and decide where you stand. Act quickly, review the current upside drivers, and dig into the 1 key reward.
Looking for more Badger Meter style investment ideas?
Do not stop with Badger Meter. Use the Simply Wall Street screener to spot fresh opportunities that fit your style before other investors crowd in.
- Target quality at a discount by reviewing a curated 38 high quality undervalued stocks that filters for strong fundamentals and supportive valuations.
- Focus on resilience first and scan a 31 resilient stocks with low risk scores filtered for companies with sturdier balance sheets and fewer red flags.
- Hunt for tomorrow's leaders early through a 19 high quality undiscovered gems that highlights under-followed businesses with solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com