


EN
How Positive Pain Trial Data At Xenon Pharmaceuticals (XENE) Has Changed Its Investment Story
- Xenon Pharmaceuticals reported past positive Phase 1 results for pain drugs XEN1701 and XEN1120, with both compounds meeting target engagement and showing generally mild side effects that supported plans to move into Phase 2 acute pain studies.
- The most distinctive element was the linkage between more than 75% NaV1.7 receptor occupancy and a pain free human genetic phenotype, which frames Xenon Pharmaceuticals’ pain assets as tightly guided by mechanistic and translational evidence rather than trial and error dose finding.
- We will now look at how Xenon Pharmaceuticals’ investment narrative could be influenced by Phase 1 receptor occupancy data in acute pain.
Scan beyond Xenon Pharmaceuticals and compare its pain-focused approach with other hand-picked biotechs progressing clinically advanced programs through our 19 high quality undiscovered gems.
Xenon Pharmaceuticals Investment Narrative Recap
To own Xenon Pharmaceuticals, you need to believe the ion channel platform can convert clinical assets into future commercial products across epilepsy, mood disorders, and pain. The recent Phase 1 data for XEN1701 and XEN1120 adds technical depth to the pain story but does not change that the key near-term value driver remains azetukalner in late-stage epilepsy trials.
The biggest operational risk stays the same. Xenon is loss making with no current revenue and needs clean late-stage readouts plus future payer support to move toward self-funding. The pain franchise update modestly broadens the long-term opportunity set but does not materially reduce development, reimbursement, or execution risks today.
The most relevant update for this news is the detailed Phase 1 and preclinical package around XEN1701 and XEN1120, which now supports advancing both into Phase 2 acute pain studies targeted for the first half of 2027. For a holder of Xenon Pharmaceuticals, this sharpens the idea that the business is not only an epilepsy story but an ion channel platform targeting several neurological and pain indications.
That platform angle matters for catalysts. Azetukalner still anchors the near-term thesis in epilepsy and mood disorders, with late-stage results likely to dominate sentiment. The XEN1701 and XEN1120 progress introduces an additional set of potential readouts further out, while also adding another layer of clinical and execution risk if timelines slip or future efficacy signals do not match the mechanistic promise implied by receptor occupancy and modeling work.
Xenon Pharmaceuticals' current analyst narrative projects revenue of US$435.9 million and earnings of US$75.0 million by 2029. This reflects a move from no revenue today and an earnings loss of US$409.2 million to positive profitability, implying a total earnings swing of about US$484 million over that period.
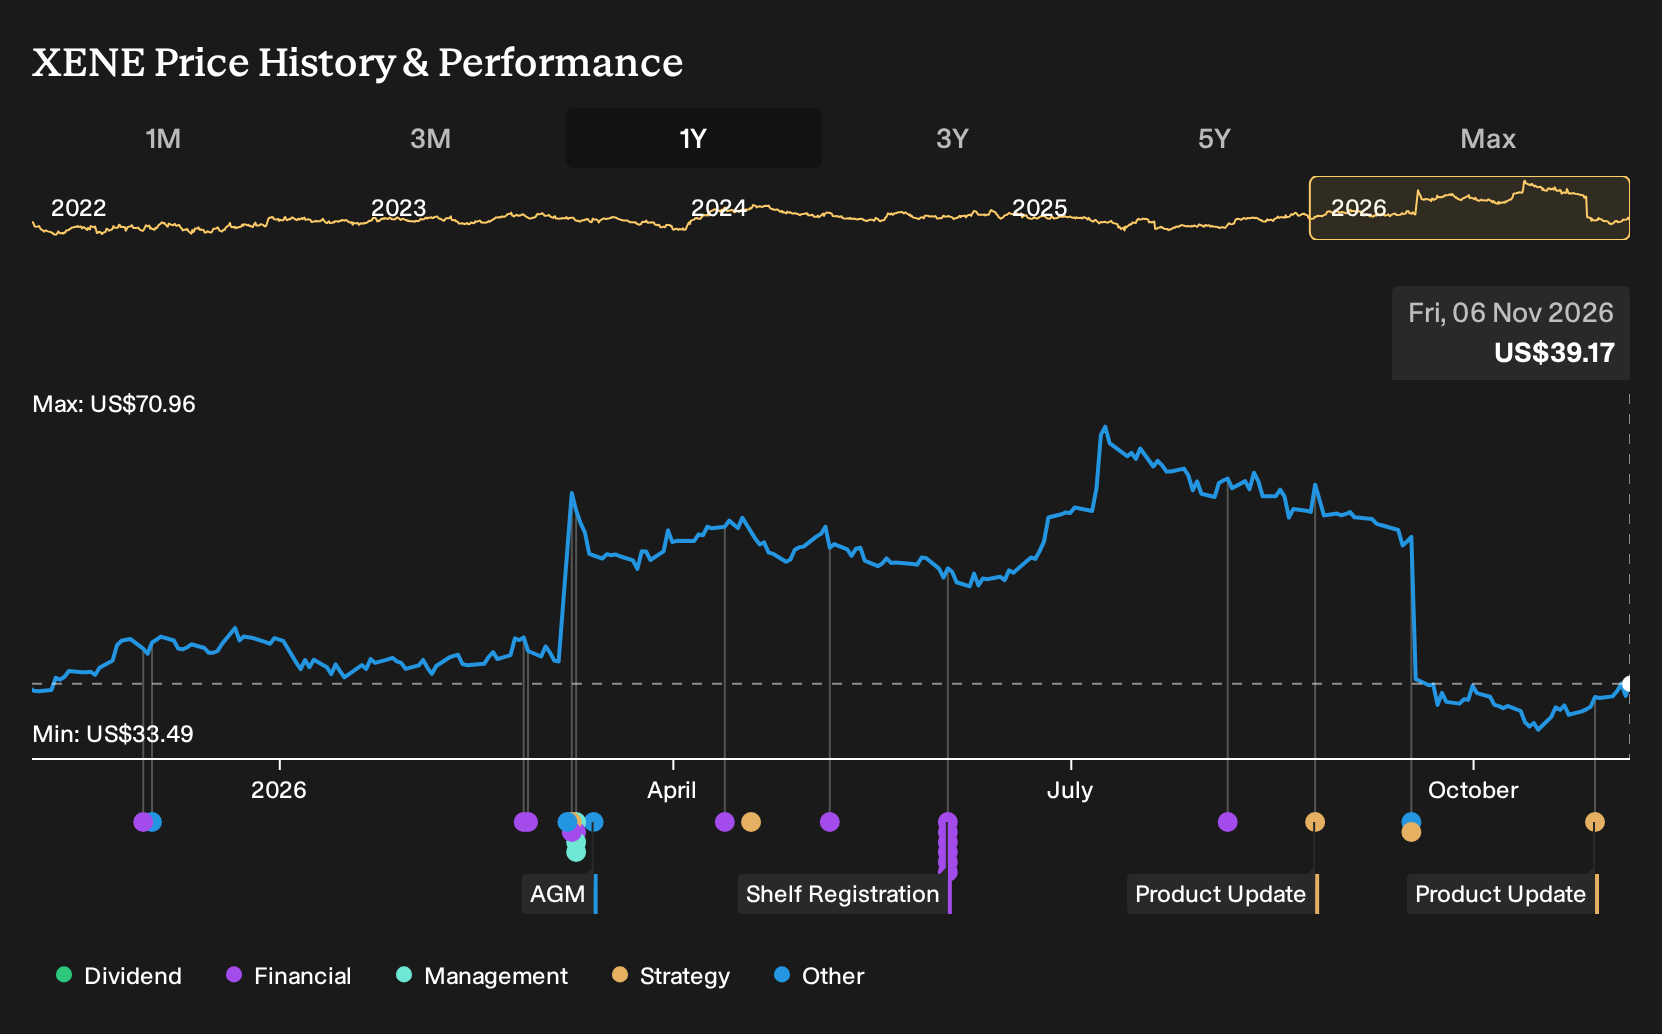
Uncover why Xenon Pharmaceuticals' fair value indicates an 85% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Xenon Pharmaceuticals leans heavily on the psychiatry program as a future catalyst, not just epilepsy and pain. Bullish analysts were modeling about US$983.3 million of revenue and US$179.9 million of earnings by 2029, far above consensus. Those projections and today’s fresh pain data could both push forecasts to shift, in either direction.
Explore 2 other Xenon Pharmaceuticals fair value estimates, including one that suggests an upside of as much as 980% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Xenon Pharmaceuticals research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Xenon Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xenon Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Xenon Pharmaceuticals?
If the Xenon Pharmaceuticals story has sharpened your thinking about risk, timelines, and clinical payoff, it can be useful to set it alongside other opportunities that fit very different profiles. The Simply Wall St Screener helps you move from a single ticker to a watchlist that matches your own comfort with quality, volatility, and income.
- If you want candidates that combine quality metrics with the possibility of mispricing, start with a curated set of 38 high quality undervalued stocks that meet strict fundamental criteria.
- If capital preservation is front of mind, narrow your focus to a 31 resilient stocks with low risk scores and see which businesses score well on balance sheet strength and risk checks.
- If you prefer companies that prioritize steady cash returns, aim your search at a 7 dividend fortresses that concentrates on higher yielding payers with resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com