


EN
Is TKO Group Holdings (TKO) Above Fair Value After 268% Gains?
TKO Group Holdings has delivered strong long term share gains, yet the recent price around US$191 raises a simple question for you as an investor. Is the market price you see today adequately grounded in what the business currently earns and can realistically earn from its combat sports and entertainment portfolio?
- The stock has returned about 268.1% over the past 5 years, which puts real pressure on the idea that the current valuation is still supported by its earnings power.
- Fresh talks to widen UFC distribution beyond Paramount+, including potential exposure on HBO and TNT, can influence how investors think about future earnings strength and the durability of TKO Group’s cash generation.
- The analysts covering TKO Group Holdings have run their own numbers. See what analysts think TKO Group Holdings's shares could be worth.
The issue now is whether TKO Group Holdings’ current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings based valuation question you are asking about TKO Group Holdings across a wider field, run the 38 high quality undervalued stocks
Does TKO Group Holdings Look Pricey on Earnings?
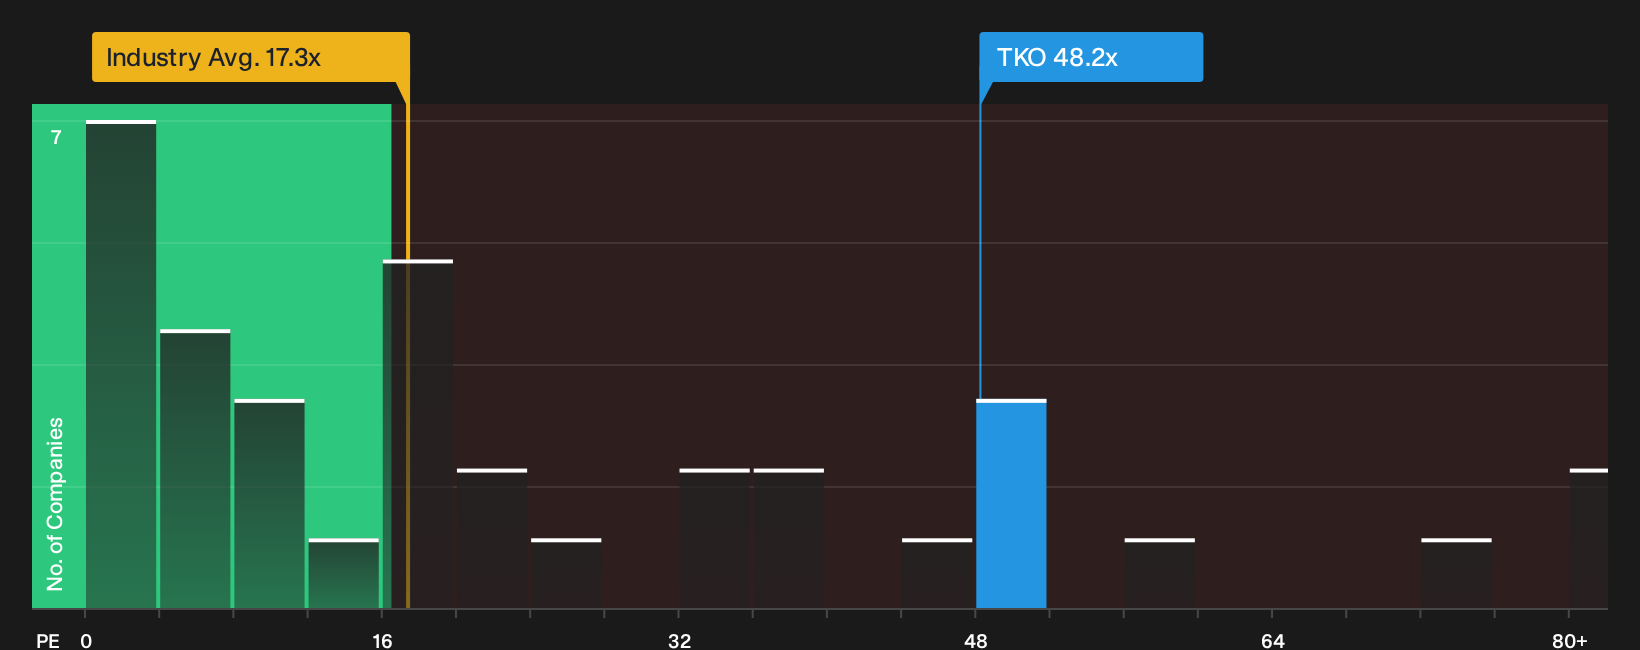
P/E is a useful lens for TKO Group Holdings because investors focus heavily on the earnings it can pull from long term media and rights deals. At roughly 48.2x earnings, the stock trades at a clear premium to the Entertainment sector average of about 17.3x and also above the peer group around 39.5x. Because the Fair Ratio framework adjusts for factors like profitability, size and risk, the current P/E sitting above that tailored benchmark points to a valuation that screens as overvalued on this metric.
The UFC distribution talks involving HBO and TNT keep expectations high, yet the current P/E already prices in a lot of earnings strength relative to both sector and peer norms. For anyone assessing TKO Group Holdings today, the key question is whether the existing earnings base and the media portfolio justify paying this kind of premium multiple relative to what similar businesses trade on. Explore the numbers behind TKO Group Holdings's P/E valuation.
The TKO Group Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for TKO Group Holdings leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Each scenario links a grounded fair value estimate to a specific mix of potential catalysts and risk factors, so you can track over time which version of TKO Group Holdings' story is playing out.
One of the top community narratives on TKO Group Holdings: 19% undervalued
"Rising demand from blue-chip brands for year-round, culturally relevant sports IP is enabling TKO to bundle UFC, WWE, PBR and future Zuffa Boxing inventory into larger, multi-property partnerships..."
Discover why this Narrative puts TKO Group Holdings at 19% undervalued.
There is one more side to TKO Group Holdings worth checking
Price tells only part of the story for TKO Group Holdings, because the research also flags specific concerns that could matter a lot to future risk and reward. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com