


EN
Earnings Guidance Update Could Be A Turning Point For Avery Dennison Stock (AVY)
- Avery Dennison reported Q3 2026 sales of US$2,331.5 million and net income of US$169.7 million, alongside updated full year earnings guidance of US$9.45 to US$9.59 per share.
- The pairing of higher earnings per share across the first nine months and a tighter full year guidance range gives investors a clearer read on Avery Dennison’s operating trajectory and confidence level for 2026.
- We will look at how Avery Dennison’s updated full year earnings guidance reshapes its investment narrative and long term earnings profile.
Avery Dennison Investment Narrative Recap
To own Avery Dennison, you need to believe its higher value solutions like Intelligent Labels and RFID can steadily become more meaningful within a materials heavy portfolio, while earnings hold up against raw material inflation and wage pressure. The firm’s updated 2026 EPS range and steady year to date profit trend give you clearer guardrails around that view in the near term.
Right now, the main short term swing factor is how much of the earlier customer inventory prebuys unwind and what that reveals about real end demand. The biggest risk is that sluggish organic sales in core materials, combined with higher input costs, could squeeze margins and slow the shift toward higher value segments.
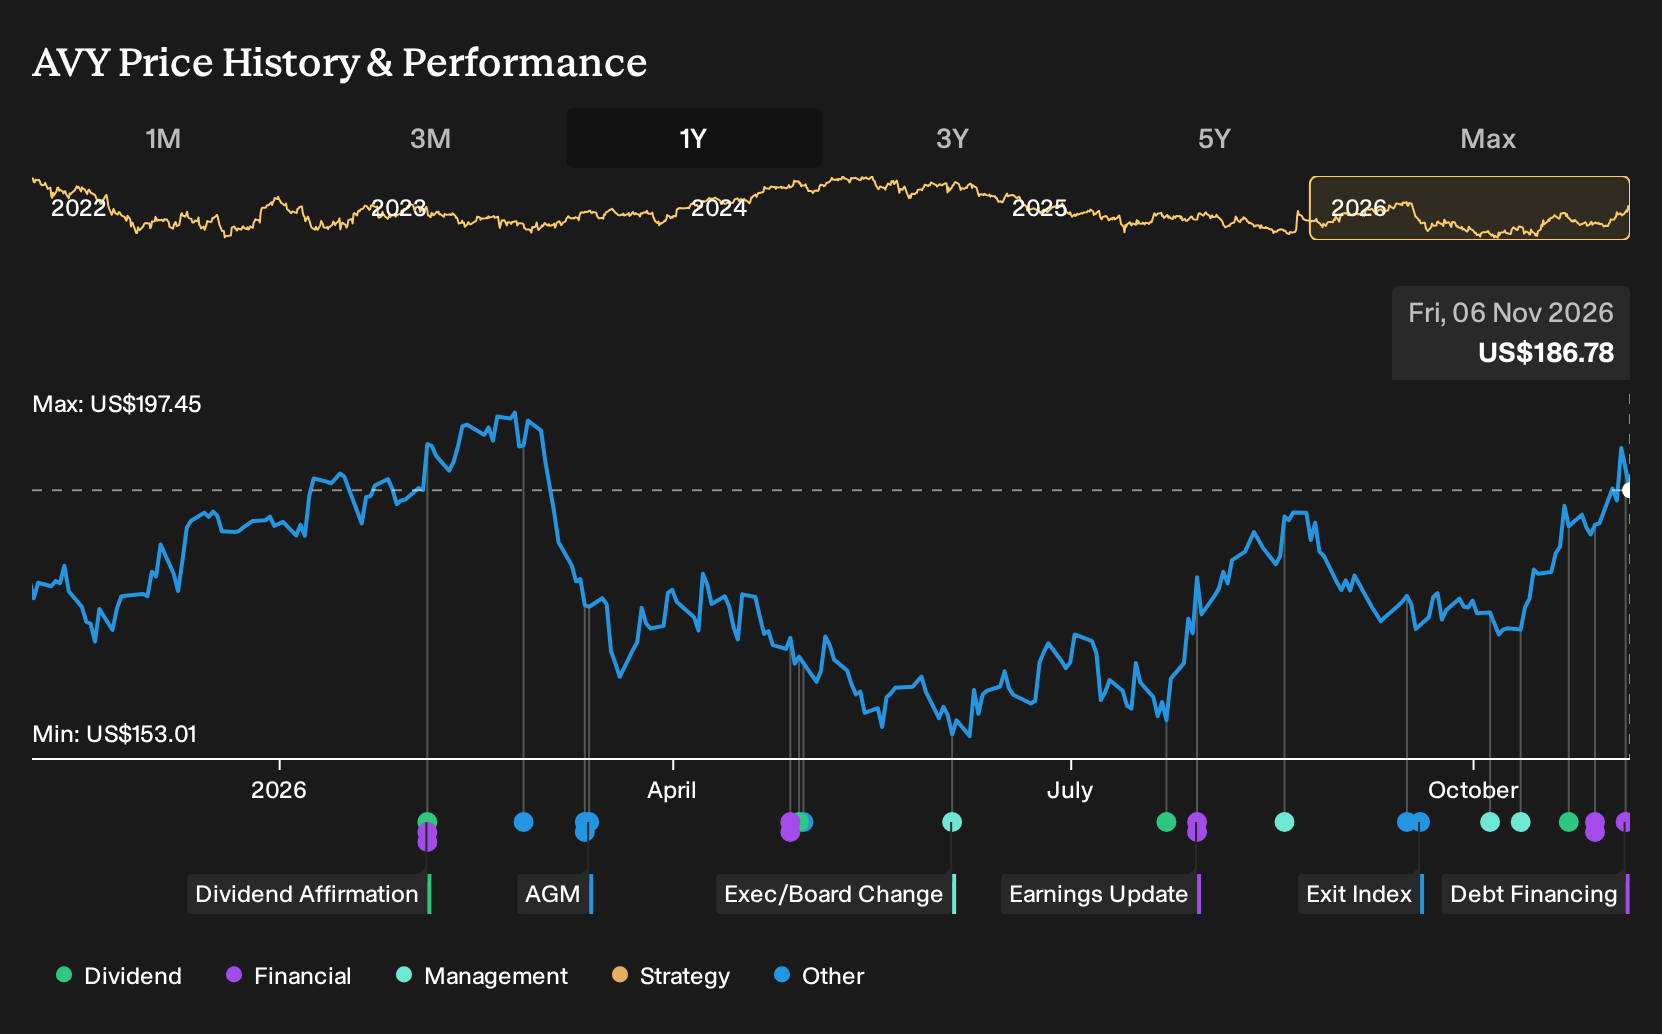
The fresh earnings guidance for 2026, at US$9.45 to US$9.59 per share, is a key reference point when considering the new debt tender. That EPS range reflects what current operations are producing, while the tender offers fall within the capital structure category and are capped at US$225.0m of principal.
If the tender removes some longer dated, higher coupon notes, it could reduce interest expense and slightly improve flexibility, which is relevant for funding Intelligent Labels rollouts and mix upgrades in the Materials Group. Investors following factors such as RFID adoption, pricing actions and raw material inflation now have one more data point on how Avery Dennison is managing leverage alongside those operational priorities.
Avery Dennison's current consensus narrative points to revenues of US$10.2b and earnings of US$939.6m by 2029, based on analysts assuming revenue grows 3.2% per year and earnings rise by about US$234.7m from US$704.9m today.
Discover how Avery Dennison's fair value indicates an 8% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$201.80 up to roughly US$335, which shows how far apart retail views on Avery Dennison can run. When you set that against the debt tender and raw material inflation risks, you can see why it pays to compare several viewpoints before leaning on any single narrative.
Explore another Avery Dennison fair value estimate, including one that suggests it could be worth just $201.80.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avery Dennison research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avery Dennison. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avery Dennison's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avery Dennison?
Once you have a view on Avery Dennison, it often helps to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener lets you quickly scan for stocks that line up with the kind of balance sheet strength, value tilt, or income profile you want in your portfolio.
- If capital preservation sits high on your list, start with companies that score well on resilience and risk and review the 31 resilient stocks with low risk scores.
- If you are hunting for potential mispricing, focus on quality businesses priced below what their fundamentals suggest and check out the 38 high quality undervalued stocks.
- If regular income matters to you, zero in on companies with higher yields and stronger payout support using the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com