


EN
What Nektar Therapeutics Stock's Late Stage Eczema Drug Progress Means For Shareholders
- Nektar Therapeutics is pushing rezpegaldesleukin through late stage trials for eczema and alopecia areata, aiming to serve patients who do not respond to current systemic treatments and to offer a different immune pathway than Dupixent and JAK drugs.
- The business now carries a rich P/S multiple relative to biotech peers. This increases execution pressure on rezpegaldesleukin’s trials and heightens the impact of any development or safety setback on Nektar Therapeutics’ future revenue mix.
- We will look at how Nektar Therapeutics’ investment narrative is reshaped by rezpegaldesleukin’s late stage progress in hard to treat patients.
Compare Nektar Therapeutics to other high-expectation stories by scanning our hand-picked 19 high quality undiscovered gems, which pair strong fundamentals with less crowded investor attention.
Nektar Therapeutics Investment Narrative Recap
To own Nektar Therapeutics, you need to believe rezpegaldesleukin can convert late stage eczema and alopecia areata programs into a real commercial franchise before the current cash runway into Q3 2028 tightens. The recent focus on hard to treat eczema and alopecia areata patients reinforces that the near term story is mostly about clinical execution rather than current revenue.
At the same time, the rich P/S multiple and limited 2026 revenue guidance of US$40 to US$45 million keep valuation tightly bound to rezpegaldesleukin trial progress. Any development or safety issue that slows Phase III eczema or alopecia studies remains the biggest risk to the business in the short term.
The most relevant context around this update is the prior disclosure that Nektar Therapeutics holds about US$1.02b in cash at the end of Q2 2026, with no debt and a guided year end balance of US$815 to US$840 million. That pool of capital gives management room to keep funding rezpegaldesleukin and the broader Treg and TNFR2 platform without near term financing.
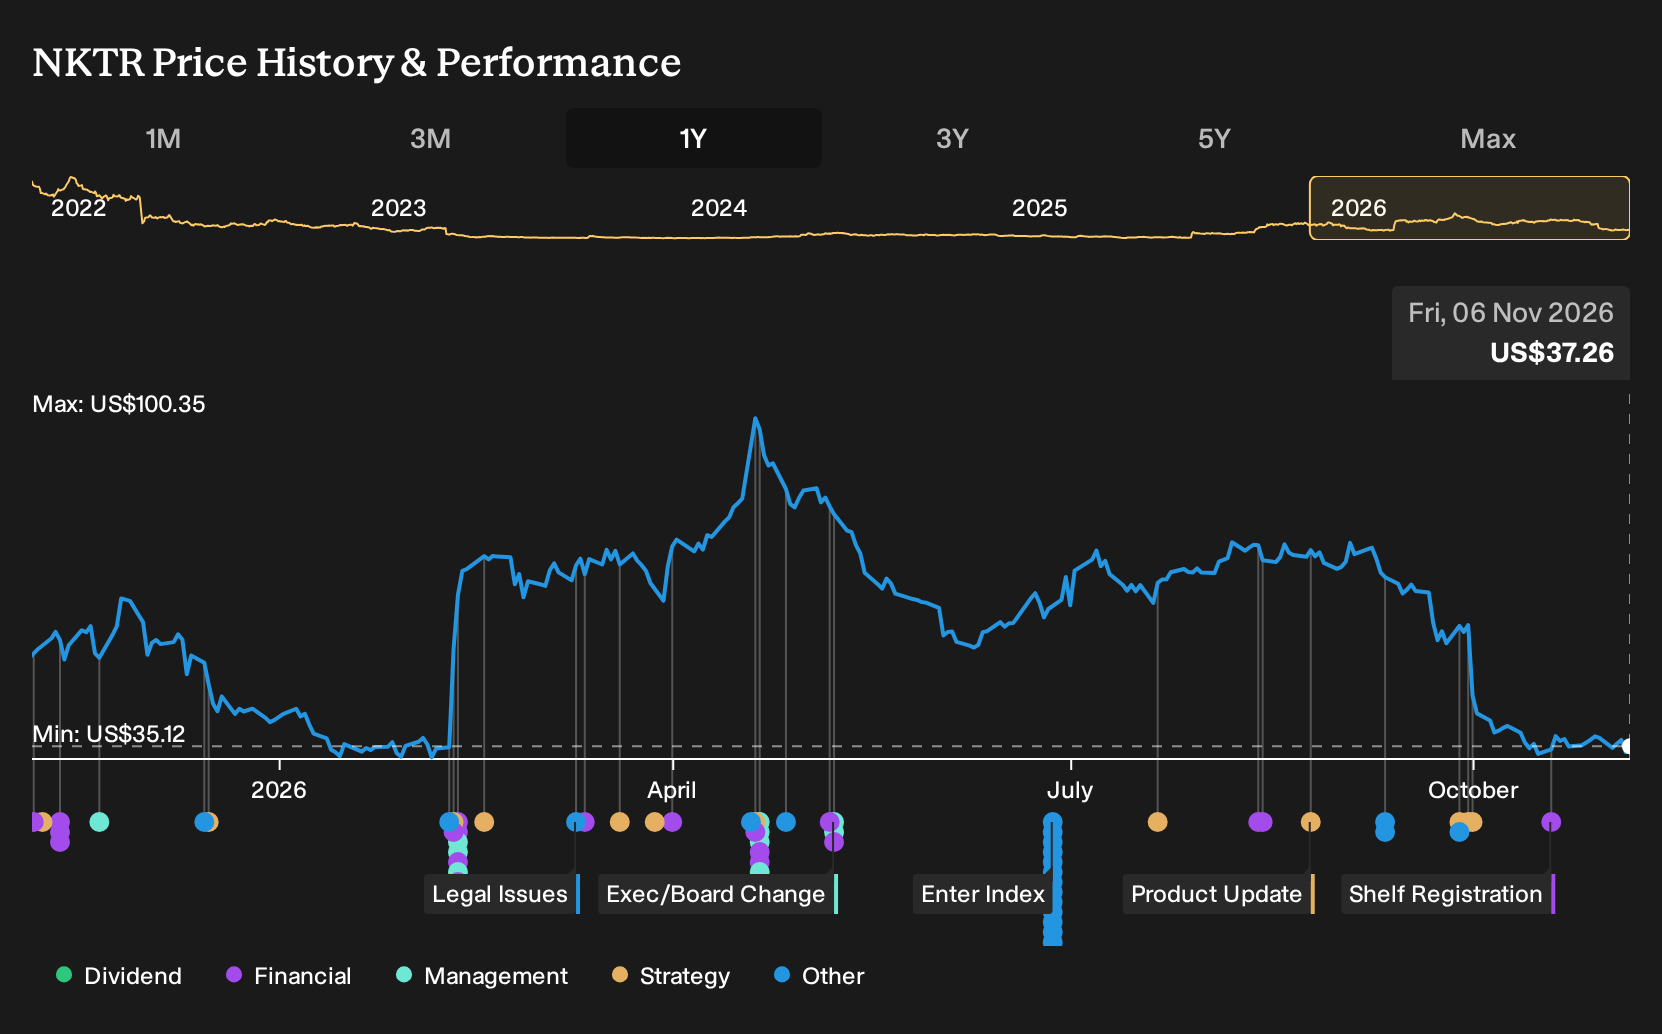
For you as a shareholder, the key operational question is whether that cash gets converted into Phase III data and, eventually, commercial use in underpenetrated atopic dermatitis and alopecia areata segments. With the stock already trading at a P/S of 22.6x compared with an industry level of 9.7x, the value of that runway now hinges on clean trial execution and timely readouts.
Nektar Therapeutics' narrative projects US$38.8 million of revenue and US$7.1 million of earnings by 2029. This is based on analyst assumptions of revenue declining 10.7% per year and requires an earnings swing of about US$164.2 million from the current loss of US$157.1 million to the projected profit.
Uncover why Nektar Therapeutics' fair value indicates a 257% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
Not every analyst shares the consensus view that rezpegaldesleukin execution is the main story for Nektar Therapeutics. The most bearish group focuses on a slower uptake catalyst, with revenue projected at only US$1.4 million and earnings of about US$301.7 thousand by 2029. That is far more cautious. These estimates were set before the latest eczema and alopecia updates, so opinions may evolve, and it can be useful to review both the cautious and optimistic cases yourself.
Explore 2 other Nektar Therapeutics fair value estimates, including one that suggests it could be worth just $133.08!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nektar Therapeutics research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nektar Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nektar Therapeutics' overall financial health at a glance.
Looking For More Nektar Therapeutics Sized Investment Ideas?
If you want to put Nektar Therapeutics in context and build a broader watchlist, the Simply Wall St Screener can help you quickly surface other businesses that fit the kind of risk and quality profile you are aiming for.
- For investors who care most about downside protection and steady fundamentals, start with a 31 resilient stocks with low risk scores that may better match a cautious approach.
- If your priority is balance sheet resilience and durable business quality, scan our list of solid balance sheet and fundamentals (25 results) and see which companies fit your criteria.
- Those hunting for quieter opportunities away from crowded trades can review the 19 high quality undiscovered gems that match your preferred mix of quality and valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com