


EN
Will Stronger Earnings Change Highwoods Properties Stock Narrative
- Highwoods Properties reported third quarter 2026 basic and diluted earnings per share from continuing operations of US$0.29, compared with US$0.12 a year earlier, and year to date earnings per share of US$1.42, compared with US$1.19 for the same period in 2025.
- The earnings update highlights that Highwoods Properties is converting its office portfolio efforts into higher earnings per share from continuing operations despite sector wide demand pressure.
- This article reviews how Highwoods Properties’ stronger earnings per share may influence the investment narrative investors were using before this update.
Compare Highwoods Properties' earnings momentum with other office-focused landlords by scanning our hand picked list of solid balance sheet and fundamentals (25 results) that may be withstanding sector pressure more effectively.
Highwoods Properties Investment Narrative Recap
To own Highwoods Properties, you need to be comfortable with a Sun Belt focused office landlord that is still dealing with soft traditional office demand while trying to translate a leased pipeline into steady earnings and cash flow. The higher earnings per share from continuing operations in the latest quarter helps the story, but it does not remove leasing, occupancy, and capex execution risk.
The key near term swing factor is whether signed but not yet commenced leases and rent spreads in its business district portfolio flow through before high leasing capex and interest costs squeeze cash generation. The biggest risk remains that elevated leasing spend and any dilution from noncore asset sales weigh on funds available to comfortably cover the dividend and interest expense.
The recent third quarter 2026 earnings announcement is the update that matters most right now. Highwoods Properties reported basic and diluted earnings per share from continuing operations of US$0.29 for the quarter and US$1.42 for the first nine months of 2026. Those figures sit against sector wide pressure on office demand, which keeps the focus firmly on quality of earnings rather than just the headline number.
Given prior flags around large one off items affecting reported profit and interest payments that are not well covered by earnings, this report directs attention to how much of the uplift reflects recurring net operating income versus accounting noise. Investors tracking Highwoods Properties will likely compare these results to leasing capex levels, asset recycling plans, and the timing of that US$20 million NOI uplift from signed leases to gauge whether the current earnings run rate looks durable.
What The Current Forecasts Assume For Highwoods Properties
Highwoods Properties' narrative projects US$919.4 million revenue and US$91.6 million earnings by 2029. This assumes 3.1% yearly revenue growth and an earnings decline of US$74.8 million from US$166.4 million today.
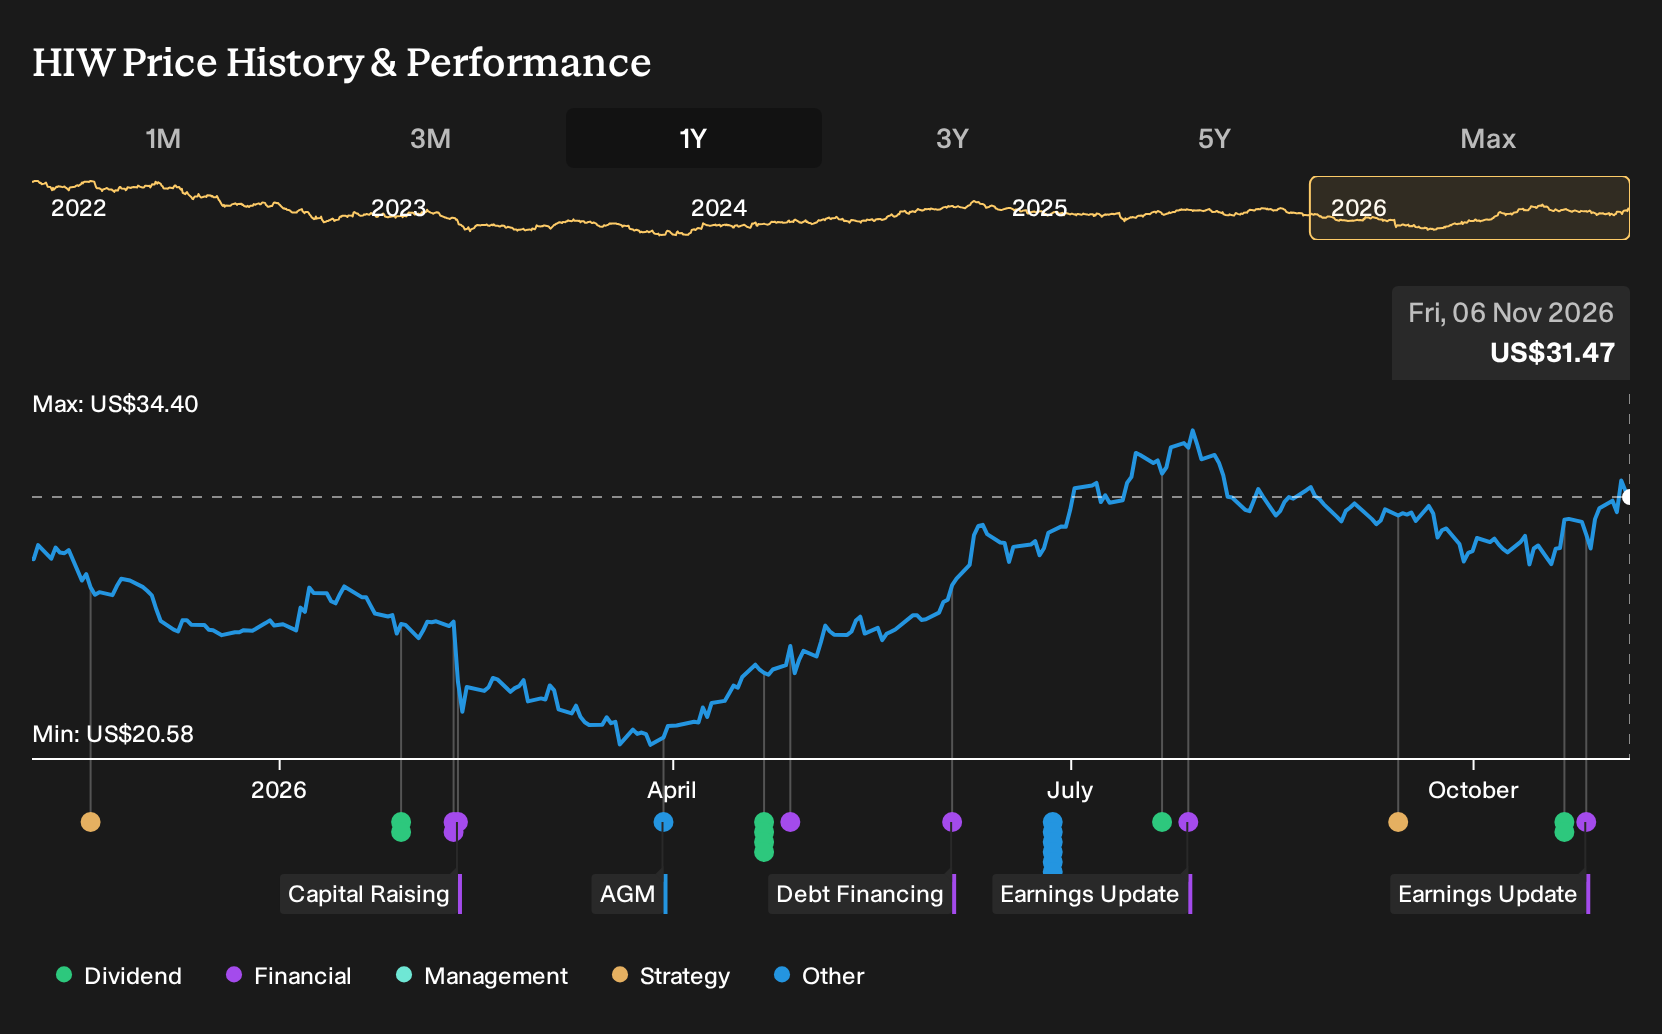
Uncover how Highwoods Properties' fair value indicates a 3% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
You are not short of debate around Highwoods Properties. The lowest analysts focus on the risk that elevated leasing capex and concessions eat into returns. This is why they were pencilling in around US$915.5 million of revenue and only US$64.9 million of earnings by 2029. That is much more cautious than the baseline view. These pre earnings estimates may shift after this quarter, so use them as starting points and compare several narratives before deciding what fits your own expectations.
Explore 2 other Highwoods Properties fair value estimates, including one that indicates up to 11% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Highwoods Properties research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Highwoods Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Highwoods Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond Highwoods Properties?
If Highwoods Properties has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you sort through other companies using the same data driven lens, instead of relying on headlines or hunches.
- For investors who want potential upside without ignoring quality, review companies flagged in our 38 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- If reliable income is your priority, scan income focused businesses in the 7 dividend fortresses to see which payouts look more resilient on current numbers.
- When capital preservation comes first, start with companies highlighted in the 31 resilient stocks with low risk scores and see which balance sheets and risk scores better align with your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com