


EN
3 Top Undervalued Stocks With Discount To Fair Value Over 27%
The recent US midterm elections shook confidence in high profile AI plays after a sharp $3.2tn sell off tied to concerns about slower AI spending. When frothy stories lose their shine, investors often look closer at solid cash generators that have been quietly overlooked. This article walks through three stocks that our cash flow focused value screen flags as trading below estimated fair value today.
The three stocks covered below are a small sample, since the full cash flow screen surfaced 99 more companies with similarly compelling stories that are not unpacked in this article. To see the broader opportunity set, head straight into the Undervalued Stocks Based On Cash Flows screener and use it to identify, analyze, and focus on the highest conviction ideas for your watchlist.
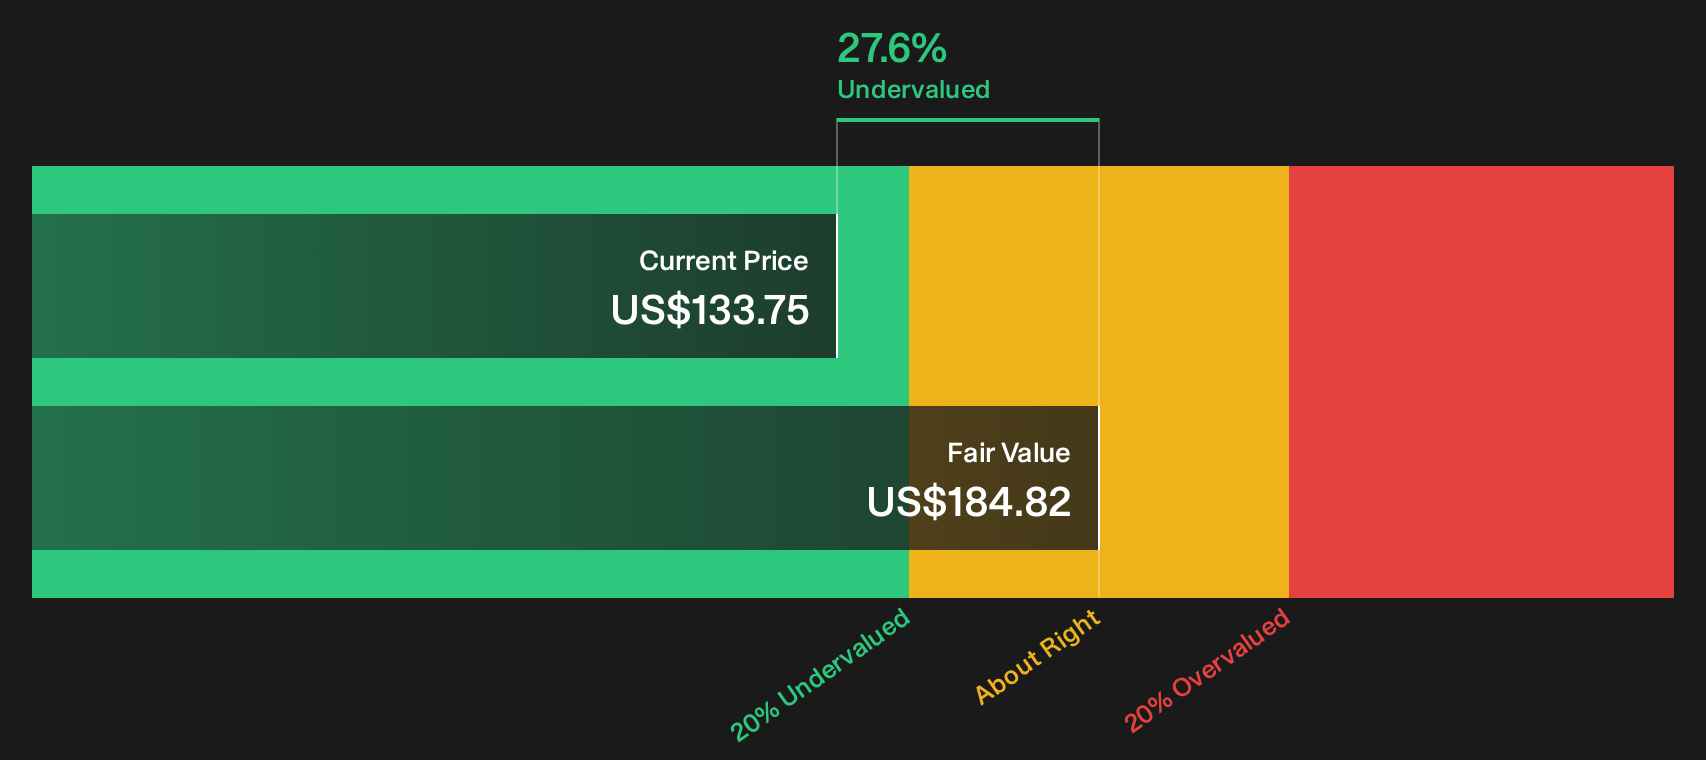
Dollar General (DG)
Dollar General plays directly into the screener’s focus on dependable cash flows. Its discount model is built around repeat purchases of everyday essentials that can underpin a discounted cash flow based value case.
Dollar General is a US discount retailer focused on low priced everyday consumables and basic household needs. It generates about US$43.6b from retail store operations and has a market value of roughly US$29.5b.
"Expansion of the Dollar General store footprint, including ongoing openings in underserved areas and early testing of new markets such as Mexico, is expected to keep adding selling square footage and support future revenue growth."
The real swing factor for Dollar General’s cash flow story now lies in how one pressure on profitability ultimately plays out against that expanding footprint.
That swing factor is exactly what the full narrative for Dollar General unpacks, showing how store expansion, mix shifts and cost pressure could be decoupling headline worries from long term cash generation.
Alphabet (GOOGL)
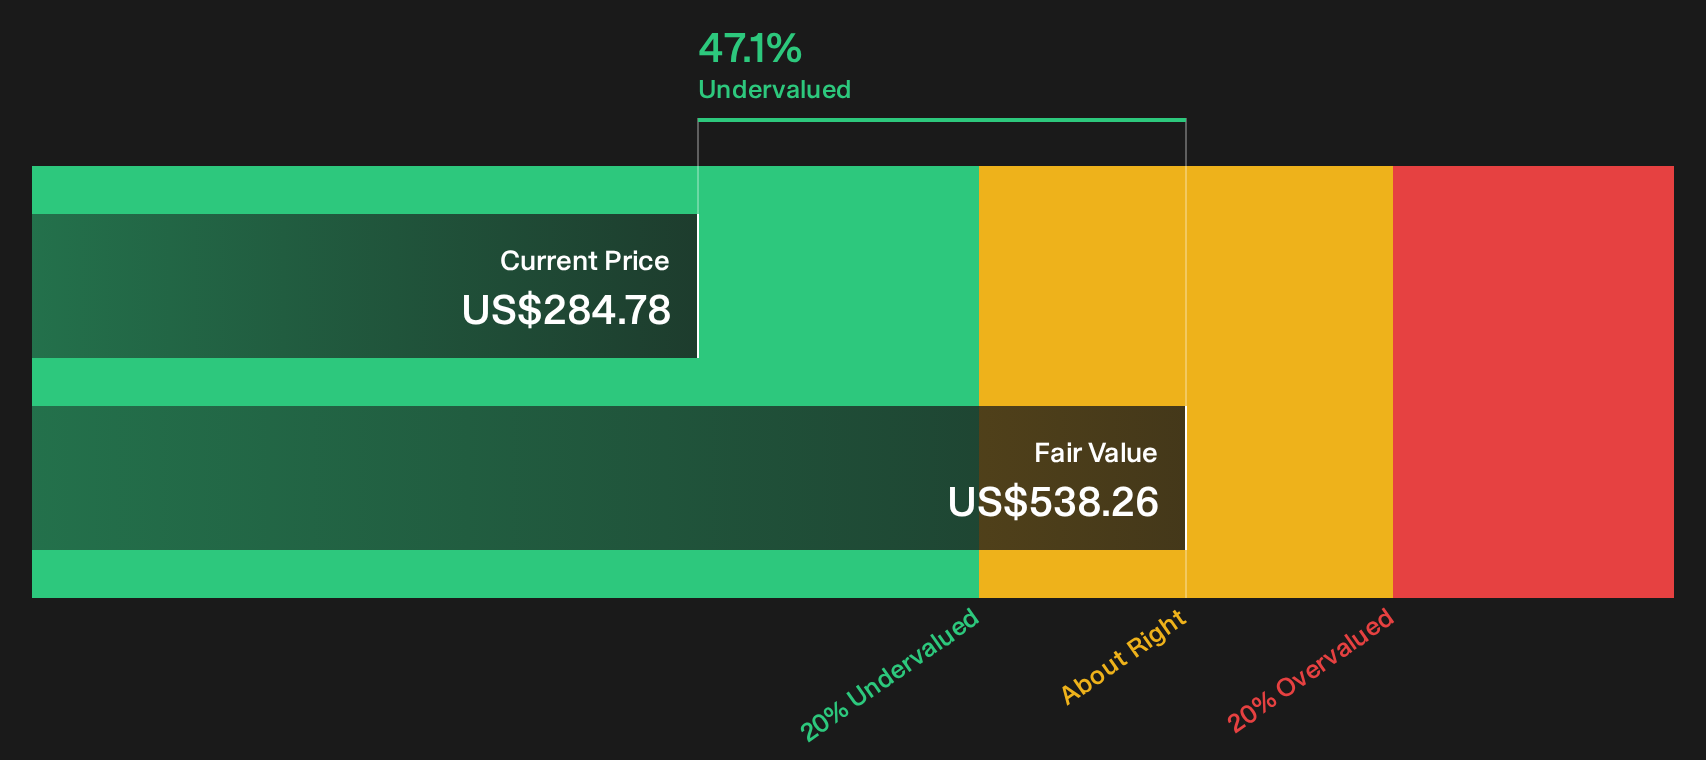
Alphabet uses its global search, YouTube and Android ecosystem to fund high margin bets like Google Cloud, where AI subscriptions and infrastructure fees link directly to the cash flow theme that underpins this screen.
Alphabet generates about US$376.3b from Google Services, US$93.2b from Google Cloud and US$1.5b from Other Bets, with a market value near US$3.5t.
For this screener, Alphabet matters because its core advertising engine already throws off sizeable cash and Google Cloud’s AI tools and infrastructure add a second, more subscription driven stream that is tightly tied to usage and enterprise demand.
"Google Cloud has gone from “meh” to money-maker, now #3 globally behind AWS and Azure, with over 11% market share. Regulatory pressure: Both the US and EU are looking at Google like it’s the final boss in Monopoly."
The next leg of the Alphabet story rests heavily on how one big swing in AI infrastructure spending ultimately filters through to sustained free cash generation.
That AI spending swing is exactly what the full narrative for Alphabet breaks down, revealing how cloud momentum, regulatory risk and cash generation could be pulling in different directions.
Caterpillar (CAT)
Caterpillar is a global supplier of heavy machinery and power systems, where Construction Industries and Resource Industries equipment plus related parts and services sit at the center of the cash flow story. Those two units generate about US$30.4b and US$14.0b in revenue respectively, while Power & Energy contributes roughly US$36.0b, Financial Products adds around US$4.5b, and the group carries a market value near US$255.4b.
Caterpillar fits this cash flow focused screen through the heavy equipment that keeps construction sites, mines and power projects running, then the ongoing parts and service work that follows each sale. That combination gives the Caterpillar story a more recurring feel than a pure equipment manufacturer and sets the stage for its current backlog driven narrative.
"Record sales and revenues of US$20.5b in Q2 2026 alongside a US$72b backlog concentrated in equipment and power systems that are still to be produced and delivered give Caterpillar multi quarter visibility on future shipments, which can support revenue and earnings as this backlog converts."
What really shapes how that potential translates into shareholder returns now is how one stubborn cost pressure rubs against those future cash flows.
That cost squeeze is exactly what the full narrative for Caterpillar unpacks, showing how Caterpillar’s backlog, pricing power and capital returns could be quietly accelerating the long term cash story.

Curious About Fresh Alternatives?
Markets move fast and the next breakout trends rarely stay under the radar for long. Scan fresh ideas before the crowd, while it matters, and get in early.
- Hunt for resilient payouts that aim to keep income flying even when prices wobble by using the curated 7 dividend fortresses as your starting universe.
- Spot early momentum in companies building the backbone of tomorrow’s AI infrastructure by zeroing in on the curated 53 AI infrastructure stocks before attention spikes.
- Track potential breakout miners tied to long term copper demand stories by combing through the hand picked 16 top copper producer stocks while they are still under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com