


EN
Wacker Chemie (XTRA:WCH) Returns To Profit As Fair Value Debate Heats Up
Wacker Chemie (XTRA:WCH) just turned prior losses into profits. Third quarter net income reached €83.6 million on €1,465.7 million in sales, with nine-month earnings at €434.8 million on €4,388.9 million in revenue.
Despite the improved profitability, Wacker Chemie’s recent share price performance has been weak. The stock is down 10.79% on a 1 month share price return and 14.53% on a 3 month share price return, even as the 1 year total shareholder return sits at 17.02%. Longer term total shareholder returns over 3 and 5 years remain deeply negative, pointing to fading short term momentum after a partial rebound from earlier declines.
Scan Wacker Chemie's peers turning improved earnings into potential opportunity by zeroing in on our handpicked 222 high quality undervalued stocks.
Wacker Chemie has swung back to profit while the share price has slid again in recent months. Is this now a solid chemicals business trading at a fair valuation, or still mispriced by the market?
Most Popular Narrative: 13% Undervalued
Against the last close of €79.40, the most followed narrative puts Wacker Chemie’s fair value at €91.09, pointing to a valuation gap that hinges on cash generation and margin repair rather than aggressive expansion.
The PACE program, which targets more than €300m of annual gross savings by 2028 and has already delivered €85m in the first half of 2026, with about €200m expected in 2026, is designed to lift EBITDA margins structurally as personnel and process efficiencies feed through.
See why 30 investors see Wacker Chemie as 13% undervalued.
Result: Fair Value of €91.09 (UNDERVALUED)
Still, the whole Wacker Chemie story unravels quickly if cost savings underwhelm or if weak construction and solar demand keep key assets running below capacity.
Find out about the key risks to this Wacker Chemie narrative.
Another View on Wacker Chemie’s Valuation
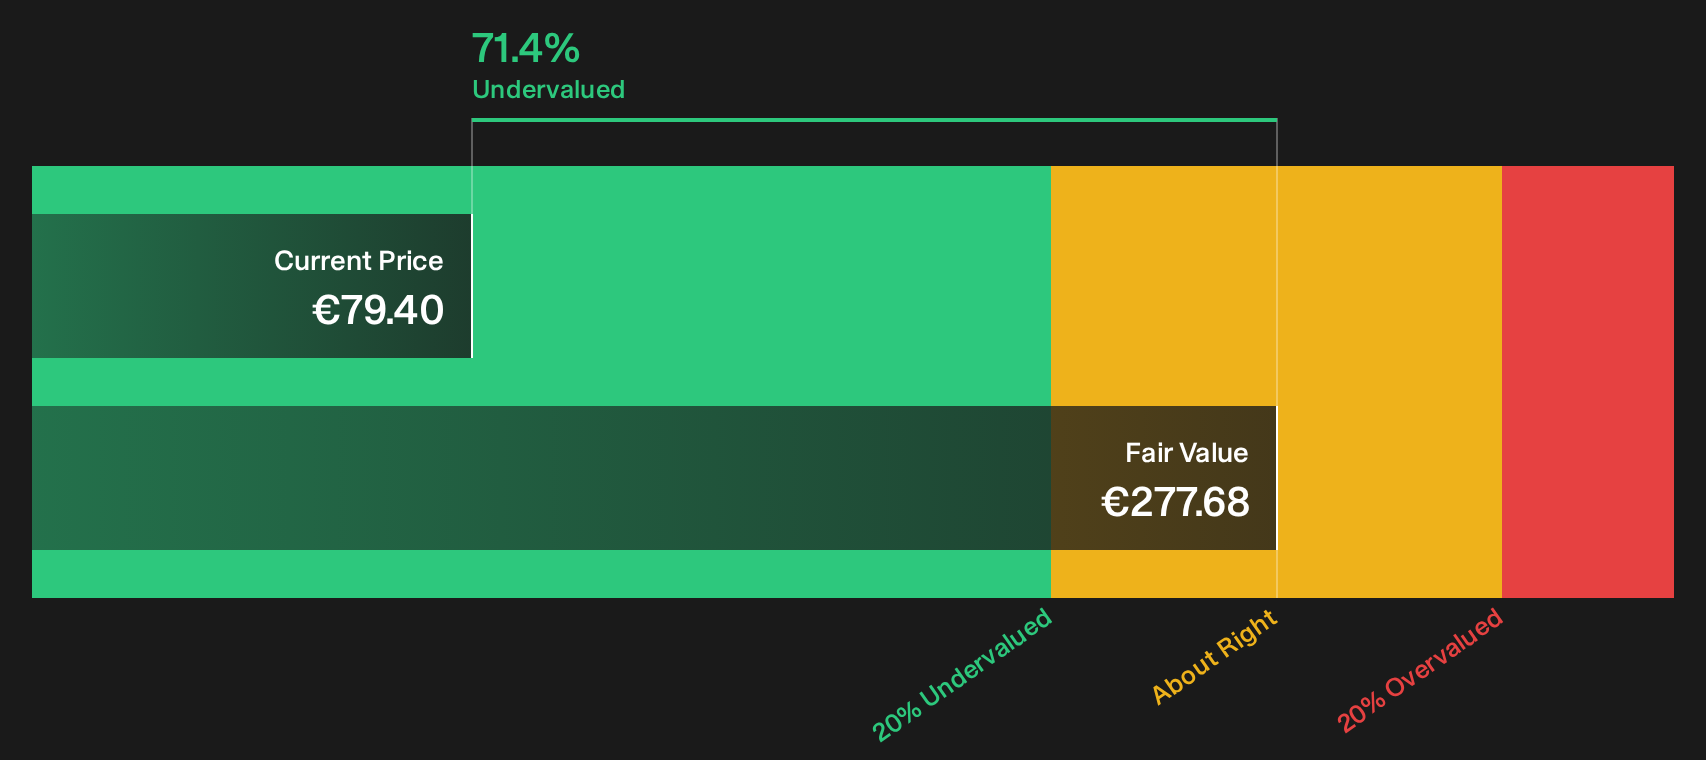
On future cash flows, the Simply Wall St DCF model points in a very different direction for Wacker Chemie. At €79.40, the shares trade about 71% below an estimated future cash flow value of €277.68, which frames the stock as heavily undervalued if those cash flow assumptions hold up.
That kind of gap raises a practical question for you as an investor. Is the market correctly discounting execution and cycle risks, or is it anchoring too much on near term earnings while the long run cash generation story gets ignored? Look into how the SWS DCF model arrives at its fair value.
Next Steps
Curious whether the market is too pessimistic or not cautious enough on Wacker Chemie right now? Move fast, review the data for yourself, then weigh those potential bright spots in the 2 key rewards.
Looking for more investment ideas beyond Wacker Chemie?
You have seen how different valuation views can reshape the Wacker Chemie story. Now widen your opportunity set by stress testing fresh ideas through targeted screeners.
- Pinpoint potential mispricings by zeroing in on companies our models flag as high quality and potentially undervalued using the 222 high quality undervalued stocks.
- Strengthen your watchlist with businesses that pair higher yields with resilient cash generation by scanning our curated set of 228 dividend fortresses.
- Limit unpleasant surprises by focusing on financially robust opportunities built on sturdy balance sheets inside our list of solid balance sheet and fundamentals (192 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com