


EN
Will Profit Return Change Marcus & Millichap (MMI) Stock Narrative
- Marcus & Millichap reported third quarter 2026 revenue of US$208.4 million and net income of US$1.0 million, with earnings of US$0.03 per diluted share from continuing operations, compared with US$0.01 a year earlier.
- For the first nine months of 2026, the firm moved from a net loss a year earlier to a modest profit, while management leaned into larger transactions, new service lines, and technology spending to reshape how the brokerage earns fees across cycles.
- We will now look at how Marcus & Millichap's investment narrative could be affected by its earnings rebound and expansion plans.
See how Marcus & Millichap’s earnings rebound compares with other commercial real estate players by reviewing our hand picked list of solid balance sheet and fundamentals (25 results), which may be positioned to benefit from the next transaction wave.
Marcus & Millichap Investment Narrative Recap
To own Marcus & Millichap, you need to believe its transaction heavy model can still work through commercial real estate cycles, while newer fee lines, like financing and auctions, make earnings a bit steadier. The latest quarter showed higher revenue and a small profit, which supports that thesis but on a modest scale so far.
The key near term swing factor is deal volume as more middle market and larger assets come to market. Interest rate volatility remains the biggest risk because it can stall transactions and pressure commission economics just as the firm is adding technology and expansion costs.
The most relevant fresh data point is the third quarter 2026 report. Revenue reached US$208.4 million with net income of US$1.0 million, and the first nine months moved from a loss a year earlier to a US$1.8 million profit. That gives Marcus & Millichap slightly more room to fund its growth priorities internally.
Management has highlighted spending on AI tools, leasing build out, and financing capabilities. It expects these initiatives to add 1% to 2% of revenue to costs over the next 18 to 24 months. For you, the real question is whether those outlays convert into more transactions and fee streams before any slowdown in commercial real estate deal activity bites into earnings again.
Marcus & Millichap's current analyst narrative points to US$1.1b in revenue and US$81.3 million in earnings by 2029. This is based on a 12.0% yearly revenue growth assumption and an earnings swing of roughly US$81.9 million from current earnings of a US$587.0 thousand loss.
Uncover why Marcus & Millichap's fair value indicates a valuation that is roughly in line with its current price.
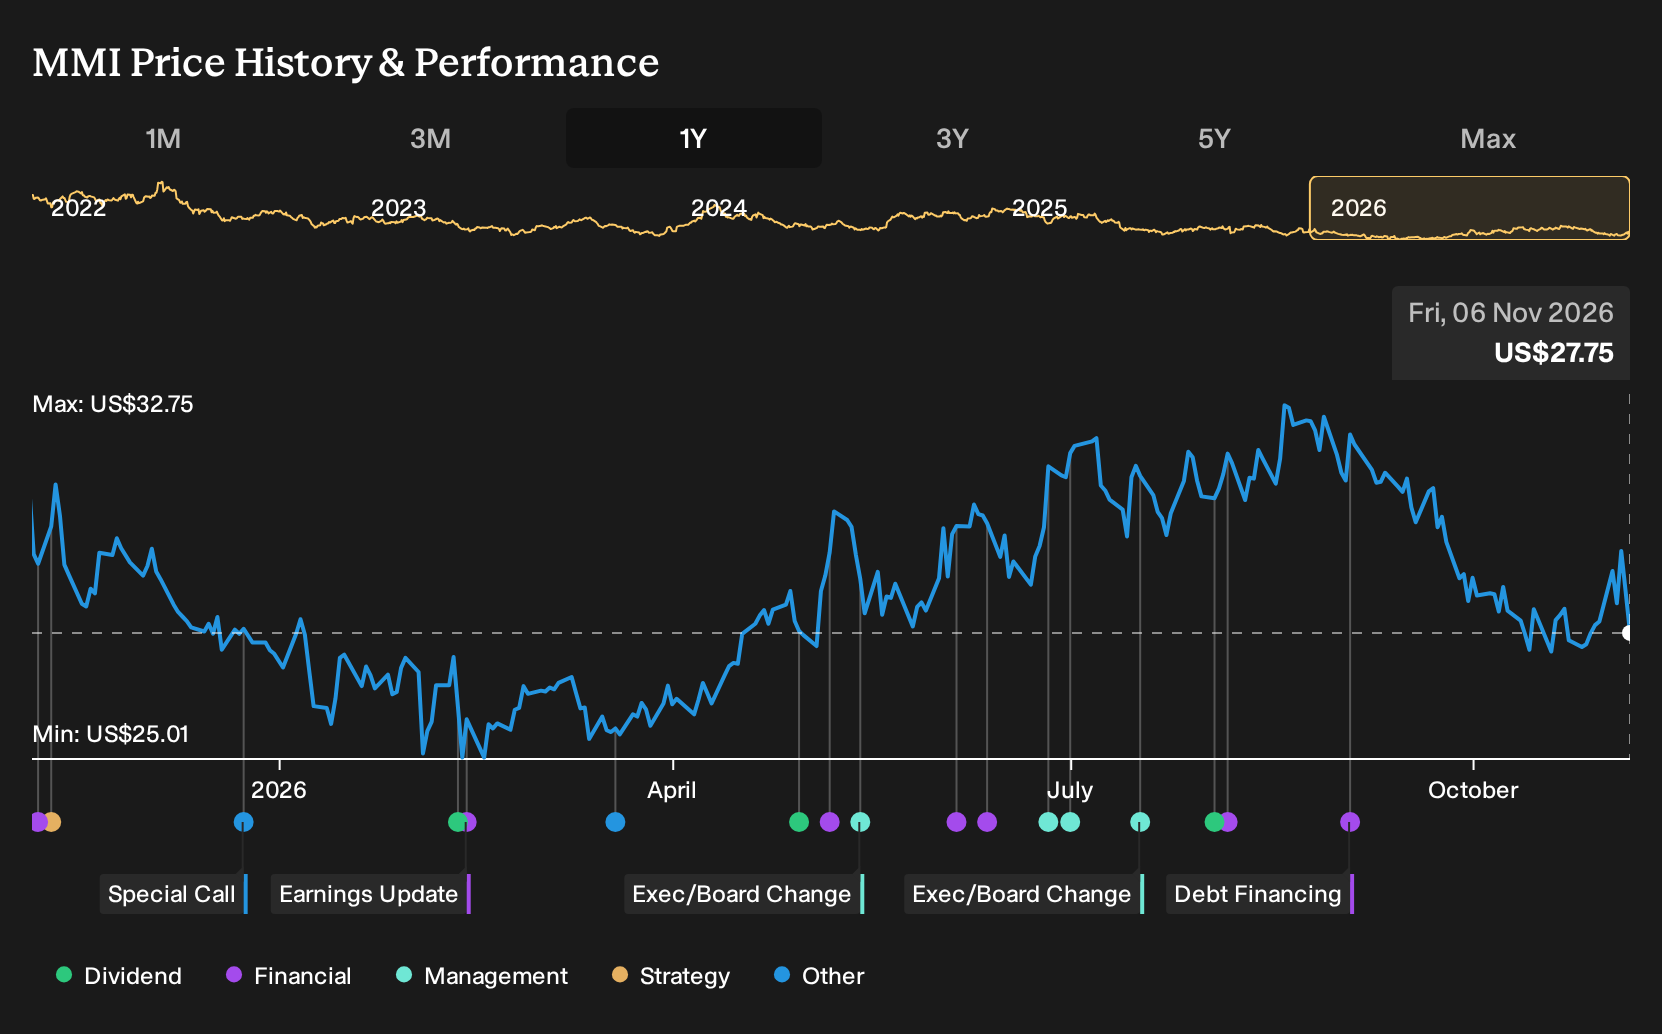
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value views for Marcus & Millichap, yet they already span a wide band from US$28 to about US$59.77 per share. You are seeing that split as interest rate volatility, fee pressure, and tech investment plans all tug on expectations for how this brokerage model holds up.
Explore another Marcus & Millichap fair value estimate, including one that suggests it could be worth just $28.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Marcus & Millichap research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Marcus & Millichap. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marcus & Millichap's overall financial health at a glance.
Looking For More Investment Ideas Beyond Marcus & Millichap?
If you want to put Marcus & Millichap in context, it helps to line it up against other companies with different balance sheet strength, dividend profiles, and valuation setups. The Simply Wall St Screener can help you surface a wider watchlist in a few minutes so you can compare quality, risk, and income potential side by side.
- For investors who care most about resilience and capital preservation, start with a 31 resilient stocks with low risk scores that score well on financial stability and lower risk profiles.
- If you prefer to focus on value and underlying fundamentals, scan a 38 high quality undervalued stocks that combine solid cash flows with what may be attractive pricing.
- Income focused readers can anchor their research around a 7 dividend fortresses that offer 5%+ yields while still aiming to keep payout strength in view.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com