


EN
How Investors Are Reacting To Prologis (PLD) Equity Sale And Warehouse Venture
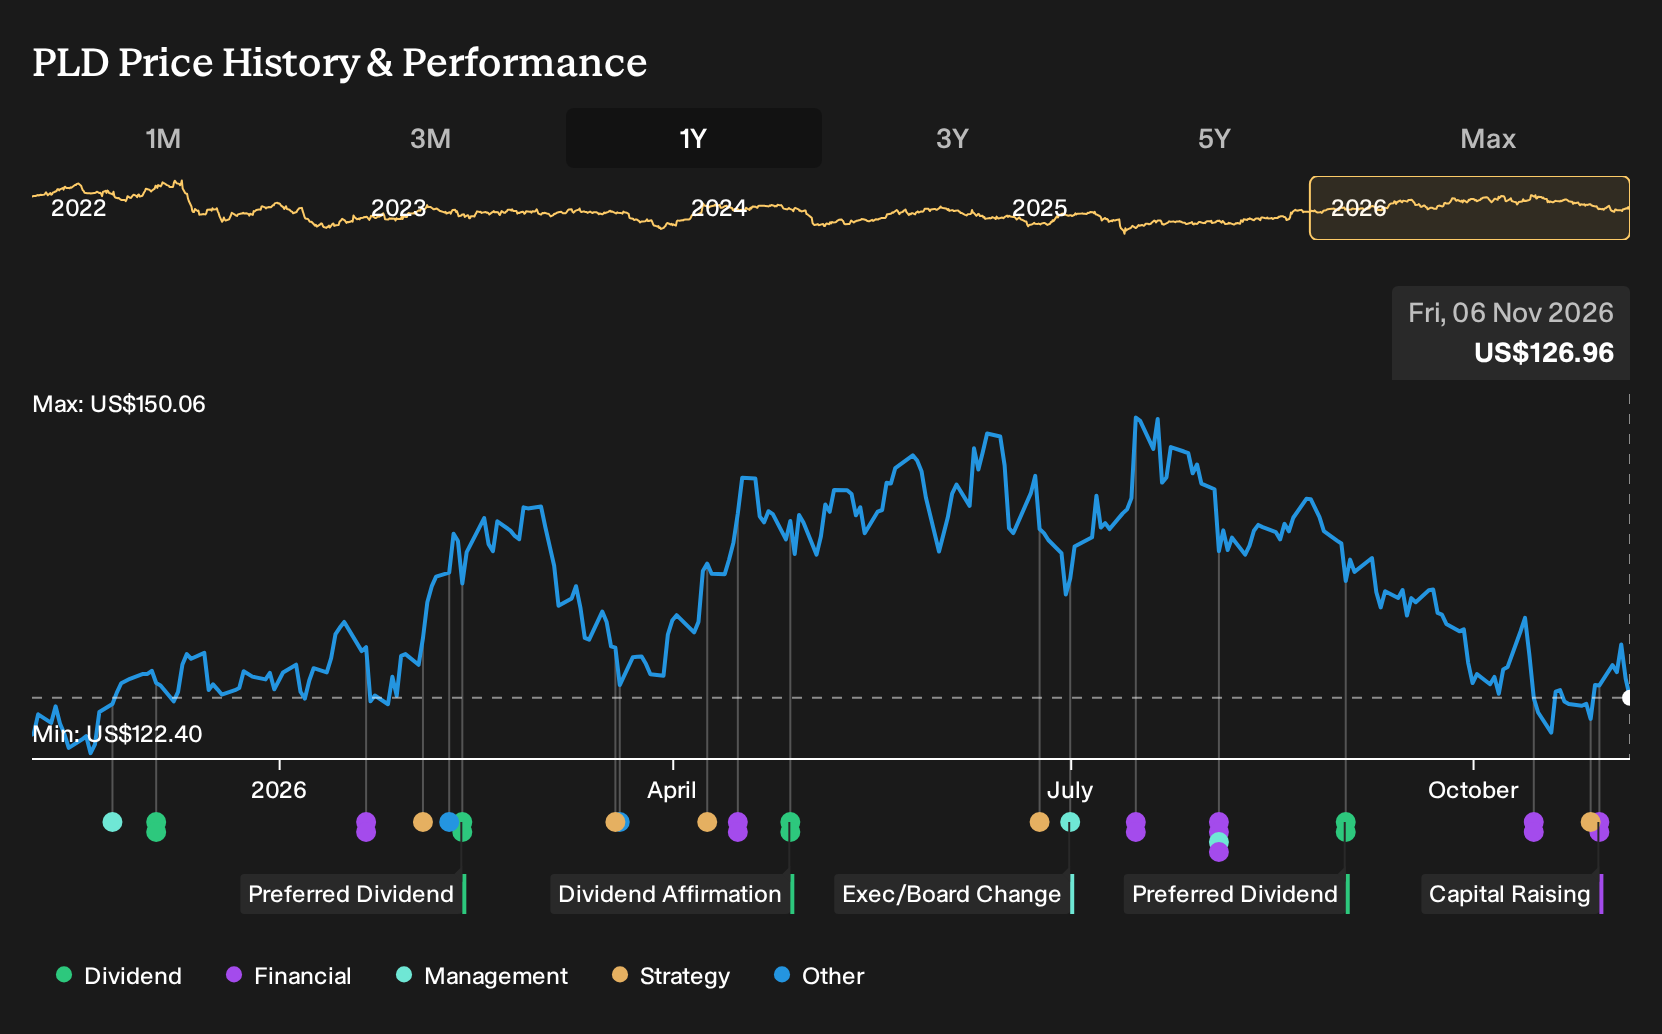
- Prologis completed a US$71.8 million at-the-market follow-on equity sale of 1,662,000 common shares and filed a separate US$5 billion at-the-market common stock program. The company also agreed to co-develop a 262-acre Class A logistics park in Joliet, Illinois with Gaming and Leisure Properties.
- The Joliet joint venture gives Prologis a large, phased development opportunity in a major Interstate 80 freight corridor, while the fresh equity capacity highlights management’s willingness to fund growth through new shares rather than relying solely on debt or retained cash.
- Investors will now be watching how Prologis's expanded at-the-market equity program could influence the existing investment narrative around capital recycling.
Scan how Prologis’ capital raise and development push compares with other real estate operators by reviewing a curated list of solid balance sheet and fundamentals (25 results).
Prologis Investment Narrative Recap
To own Prologis, an investor needs to believe that demand for logistics space, data center power and on site energy projects can keep its large asset base busy and pricing power intact. The short term swing factor is how quickly the record leasing pipeline and development projects convert into rent and fees while higher funding needs are being managed.
The fresh at the market equity capacity does not change the thesis by itself. However, it will keep dilution front of mind, especially alongside the SEGRO proposal. The bigger near term risk remains balance sheet pressure if cash flows, external capital and development or acquisition ambitions fall out of sync.
The Joliet joint venture with Gaming and Leisure Properties is the most relevant development for that thesis. It adds a multi year, 3.8 million square foot logistics park project in a key freight corridor where Prologis can apply its development, leasing and value added services platform rather than just buying finished assets.
For catalysts, this kind of phased project gives Prologis optionality. Progress on entitlements, pre leasing and construction, plus any integration of data center or energy offerings on site, will feed into how investors view the growth runway relative to dilution and the pending SEGRO decision. Execution speed and capital discipline on Joliet will be closely watched.
Prologis' current analyst framework points to US$10.6b in revenue and US$3.8b in earnings by 2029, based on an assumed 2.3% yearly top line growth rate and an earnings decline of US$0.5b from US$4.3b today.
Uncover why Prologis' fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Prologis from 2 private investors in the Simply Wall St Community cluster between roughly US$137 and US$153 per share, leaving little agreement on a single “right” number. When you set that against fresh equity issuance, the proposed SEGRO deal and the Joliet build out, you see how sharply opinions can diverge. Readers should compare these viewpoints before deciding where they sit.
Explore another Prologis fair value estimate, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your Prologis research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Prologis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prologis' overall financial health at a glance.
Looking for more investment ideas beyond Prologis?
Once you have a view on Prologis, it can help to widen the lens and compare it with other companies that match your own risk, income and quality preferences. The Simply Wall St Screener is a quick way to line up those possibilities side by side so you can pressure test your thesis against a broader watchlist.
- If capital preservation matters most, focus on businesses that score well on financial strength and balance sheet resilience with a curated 31 resilient stocks with low risk scores.
- If income is your priority, filter for companies that offer higher yields and robust payout profiles using a hand picked 7 dividend fortresses.
- If you want to spot quality that fewer investors are talking about, scan a targeted 19 high quality undiscovered gems that screens for strong fundamentals with less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com