


EN
CarGurus (CARG) Stock May Trade At A Discount As Buyback News Lands
CarGurus has delivered a 76.7% gain over the past three years, a run that naturally puts the spotlight on what investors are paying for its earnings today. With the stock most recently closing at US$33.74 and fresh financial results on the table, the open question is how well that share price lines up with the profits the business is generating.
- A 76.7% return over three years puts meaningful weight on whether the current earnings profile of CarGurus can carry that higher valuation base.
- The newly announced US$250m share repurchase plan and continued rollout of AI-enabled tools may support earnings per share if CarGurus can sustain profitable growth while reducing its share count.
- There is a second opinion on CarGurus worth weighing. See what analysts think CarGurus's shares could be worth.
The stock's next move may depend on whether CarGurus' recent earnings justify the price investors are now being asked to pay.
If you are considering CarGurus alongside other opportunities that emphasize earnings power, a focused stock screen built around 38 high quality undervalued stocks can be a useful next step.
Is CarGurus Still Cheap on Earnings?
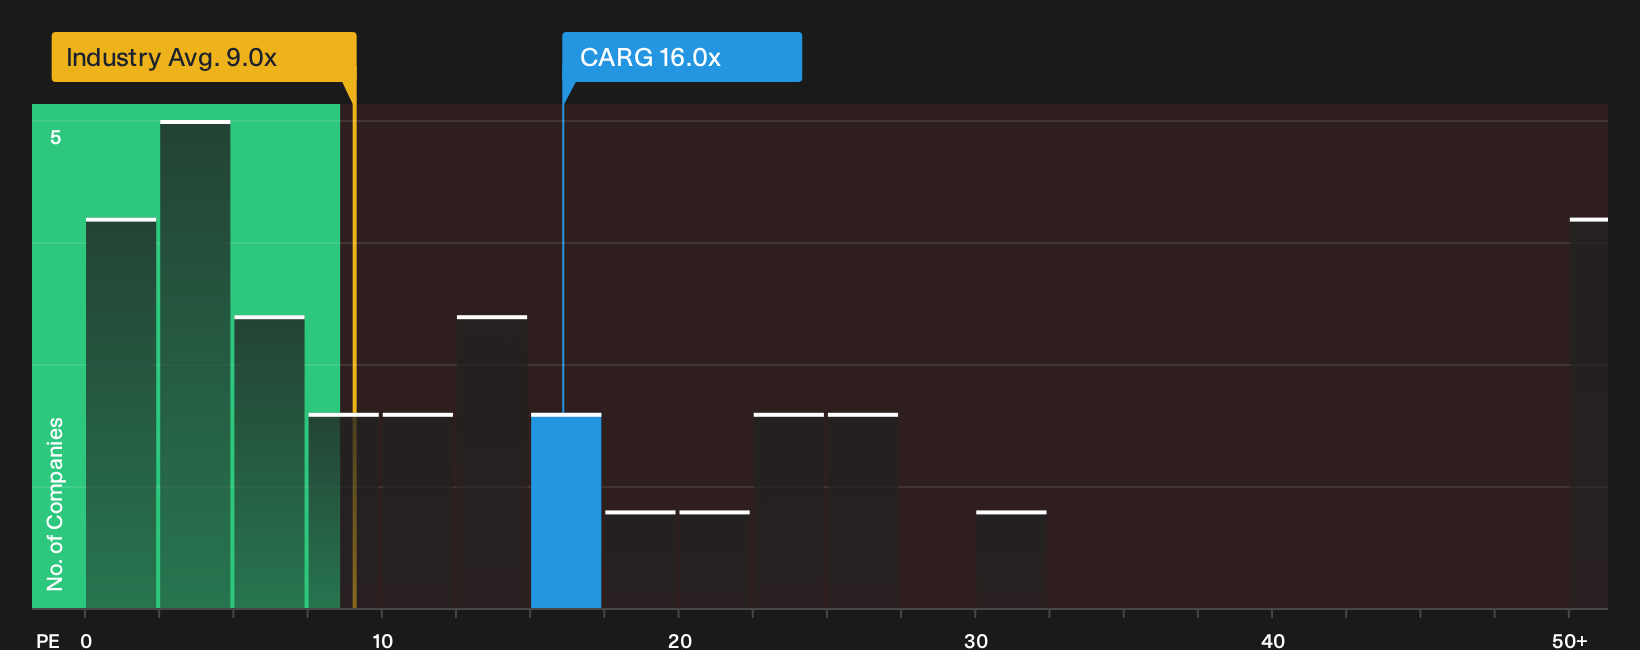
P/E suits CarGurus because earnings now play a central role in how investors judge the business. On this lens, the stock trades on a P/E of 16.0x, which is above the broader Interactive Media and Services sector on 9.0x but below the peer group closer to 26.4x. That mix indicates the market is pricing CarGurus at a premium to the average industry player while still leaving a gap to faster rated competitors.
The fair-value framework that blends the company’s growth profile, margins, scale and risk points to a higher earnings multiple than where the shares trade today. In that context, the current 16.0x sits on the cheaper side of that tailored reference point. Because the recent third quarter 2026 results and new US$250m buyback have put more attention on earnings power and share count, this discount on P/E is an important consideration for anyone weighing what they are paying for each dollar of profit. Explore the numbers behind CarGurus's P/E valuation.
The CarGurus Narrative: What Would Justify Today's Price?
CarGurus' valuation puzzle only really comes into focus once you spell out the future that would need to unfold for this price to make sense. Simply Wall St Narratives on the Community page turn that into plain language by mapping the earnings, growth and margin paths that would have to hold for the stock to sit meaningfully above or below today's level. Where a single ratio or model offers one number, these stories unpack the underlying future so you can watch how reality compares over time.
One of the top community narratives on CarGurus: 18% undervalued
"The current valuation and heavy share repurchase program imply that the market is pricing CarGurus as if its AI-led platform expansion and capital return strategy will not fully translate into higher long-term earnings power per share…"
Discover why this Narrative puts CarGurus at 18% undervalued.
One more thing about CarGurus that deserves your attention
Before you rely too heavily on the earnings multiple or buyback story, it is worth seeing what the underlying checks are flagging about CarGurus and why those risk markers could matter for future holders. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com