


EN
Primoris Services (PRIM) Beats On Q3 And Posts Record Backlog, Is It 60% Undervalued?
Primoris Services (PRIM) is back in focus after third quarter earnings outpaced expectations, paired with a record US$14.1b backlog that clarified the project pipeline even as revenue recognition practices face shareholder scrutiny.
The share price reaction has been sharp. Primoris Services jumped with a 1 day share price return of 9.81% after the earnings beat and record US$14.1b backlog, yet the stock is still down 21.77% on a 30 day share price basis and 49.93% year to date. Longer term total shareholder returns of 117.37% over three years and 167.86% over five years point to gains that are now being reassessed as investors weigh the guidance reset, dividend affirmation, board committee changes and the revenue recognition investigation.
Capture the pullback story at Primoris Services, then size it up against other infrastructure and construction plays on our curated list of 41 power grid technology and infrastructure stocks.Primoris Services now trades at a steep discount to both analyst targets and intrinsic value estimates after that sharp swing. Does that gap reflect market overreaction, or a fair penalty for guidance cuts and revenue recognition questions?
Most Popular Narrative: 59.6% Undervalued
Primoris Services closed at $65.40, while the most followed narrative pegs fair value at $161.69. The gap between price and projected worth is wide and firmly tied to how the backlog turns into cleaner earnings.
The record Q2 2026 backlog of just under $13.9b, including $3.9b of new awards across Utilities and Energy, gives Primoris Services additional room to rebalance toward higher margin work and potentially support stronger operating leverage into future earnings.
The expansion of the natural gas power generation funnel to more than $8b of identified opportunities, with 2027 gas generation revenue expected to exceed the 2026 level, creates scope for a richer mix of longer duration projects that could support Energy segment gross margins.
See why 3 investors see Primoris Services as 60% undervalued.
Result: Fair Value of $161.69 (UNDERVALUED)
Still, the securities lawsuits and the execution issues on six distressed renewables projects could easily derail the Primoris Services narrative if costs or delays deepen.
Find out about the key risks to this Primoris Services narrative.
Another View: Primoris Services Through The P/E Lens
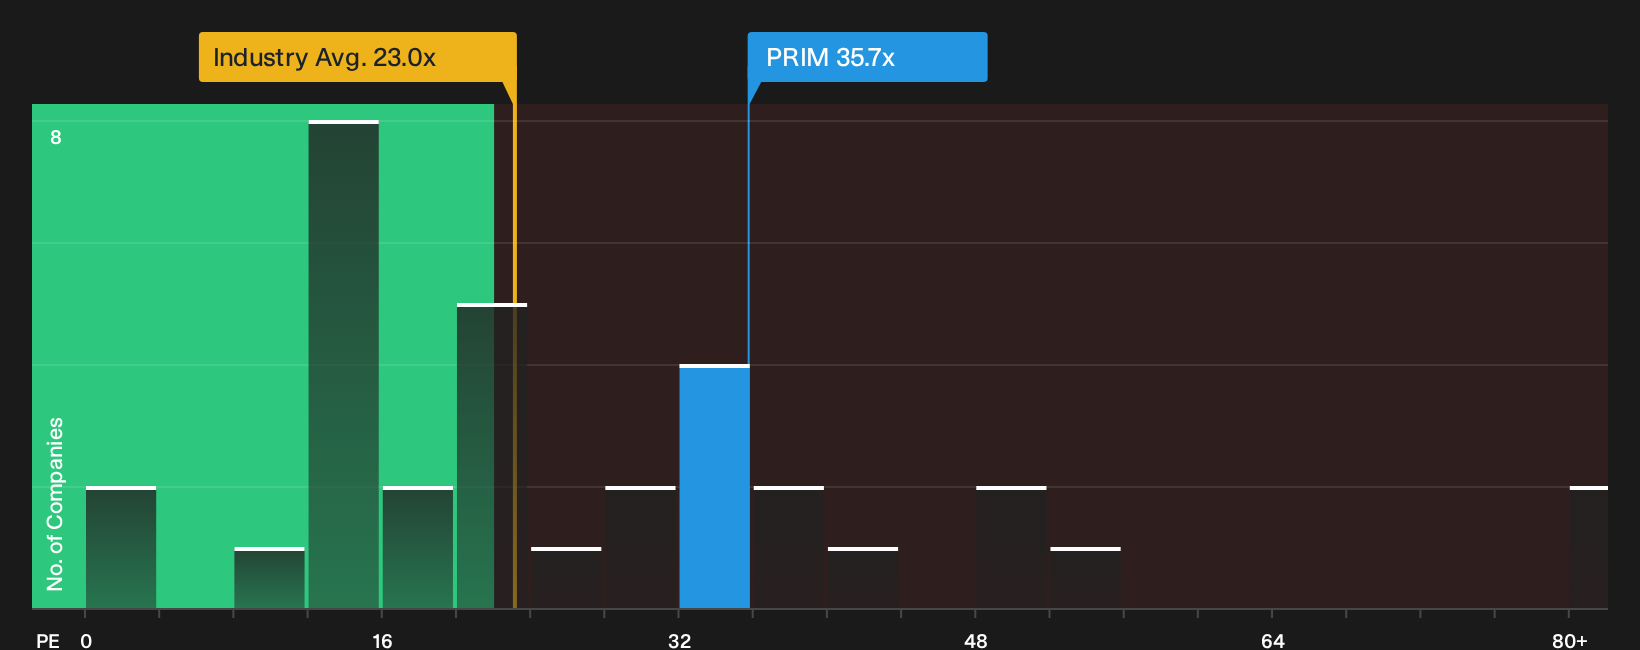
On price multiples, Primoris Services tells a very different story. The stock trades on a P/E of 35.7x, which is higher than both the US Construction industry at 23x and the peer average at 26.6x, even though the fair ratio points closer to 45.3x.
That mix of richer pricing than the sector, combined with a fair ratio that still sits above today’s level, highlights both valuation risk if expectations change and potential upside if earnings align more closely with the bullish narrative. It leaves a straightforward question for you as an investor: which side of that gap seems more likely to narrow first, the price or the profits?
See how the numbers frame this price and how it compares with the market, then explore the details in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Primoris Services is clearly split, with sharp share price swings reflecting both optimism and anxiety about what comes next. Act quickly, review the latest data for yourself, and weigh both sides of the argument through the 2 key rewards and 1 important warning sign.
Looking for more Primoris Services style investment ideas?
Do not stop with Primoris Services. Use this pullback as a prompt to refresh your watchlist, test new themes, and pressure test your current convictions.
- Target resilience by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on companies with sturdier funding and cleaner obligations than the broader market.
- Hunt for pricing gaps with the 38 high quality undervalued stocks and see which businesses currently trade below their assessed worth before attention shifts and pricing adjusts.
- Lock in income ideas using the 7 dividend fortresses so you do not miss companies combining higher yields with relatively stable payout histories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com