


EN
What Société Générale Shareholders Got Right
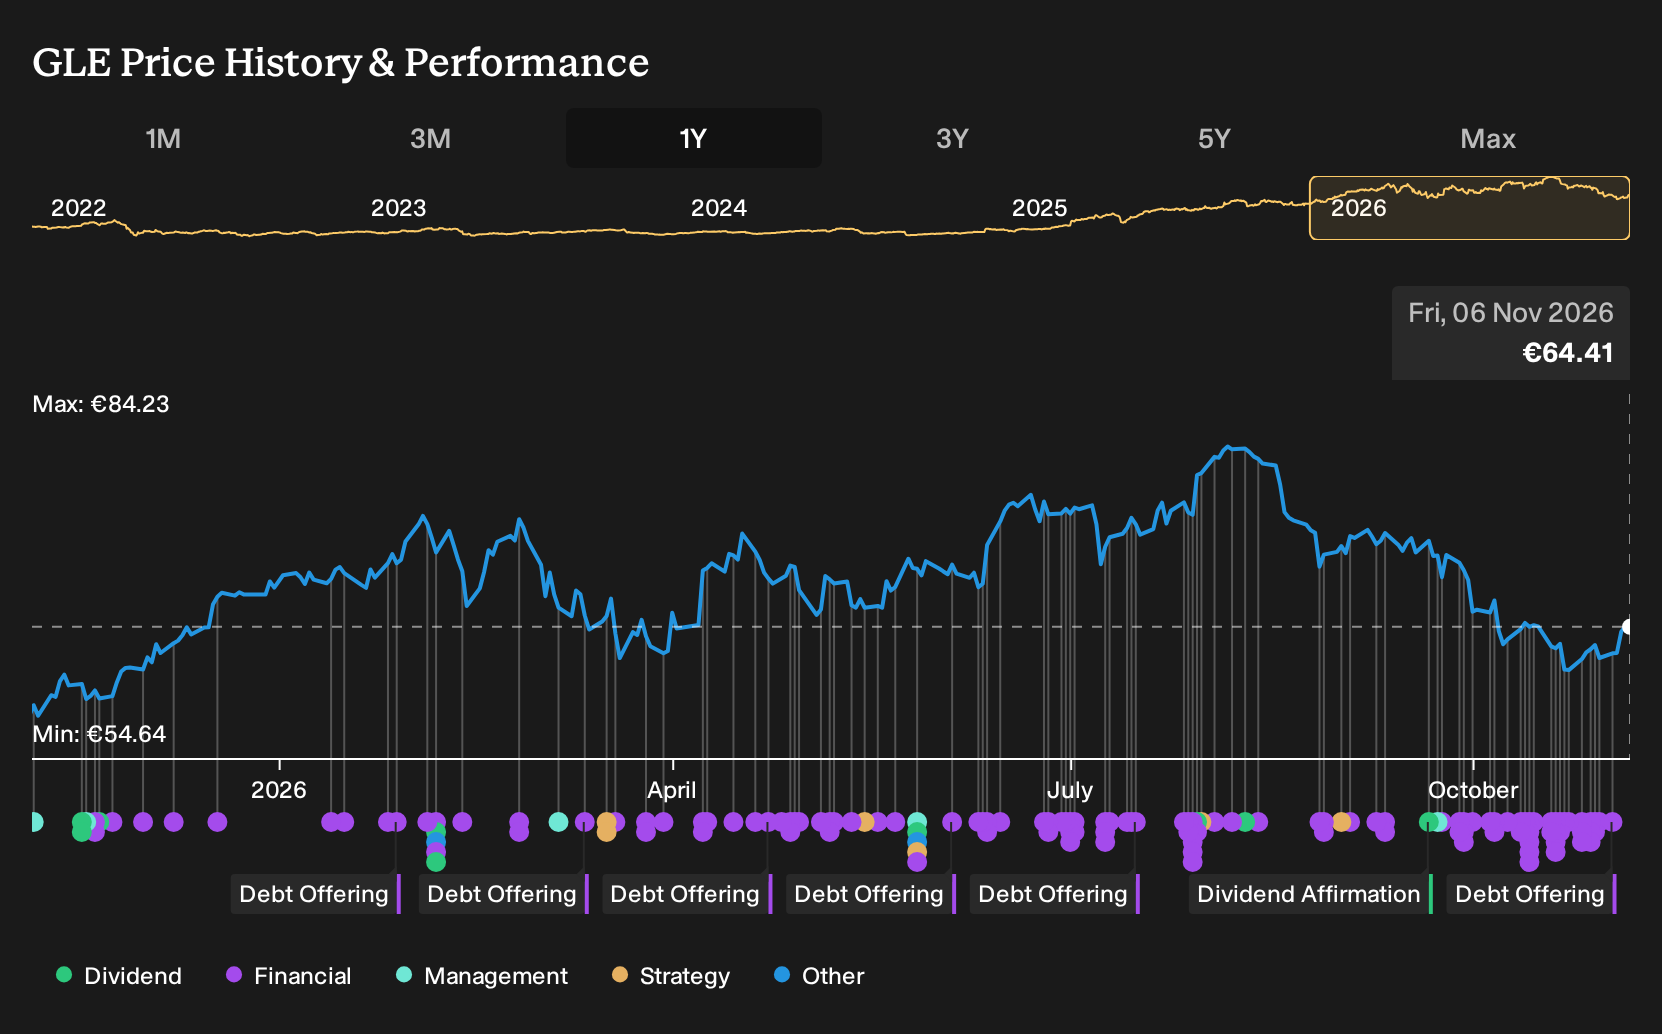
Societe Generale did not move markets with a headline acquisition or a blockbuster product launch. It quietly pushed forward a €1.5b share buy-back that shrank the share count and signalled confidence in its own balance sheet. For Société Générale Société anonyme shareholders, the return over the past year was 20.9%, including dividends. If you were deciding on 6 November 2025 whether to buy, what did you need to believe about this bank before that news landed?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Société Générale Société anonyme has already moved. See which of 222 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Weighed On Société Générale
The shares cost €55.8 at the start of the period. Anyone looking at Société Générale had to choose between two very different but reasonable stories about what came next.
The bullish Narrative put Fair Value at €62.47. It leaned on revenue growth of 4.2% and a profit margin of 20.1%, with a future P/E of 9.6x as the key upside assumption.
The bearish view set Fair Value at €46. It focused on digital disruption and rising regulatory costs as threats that could push margins down to 14.7% over time.
What The Results Changed For Société Générale
The clearest development was Société Générale’s later report that Q3 2026 revenue reached €6,765m with net income of €1,697m, and net margin of 25.1% versus 22.0% a year earlier. That combination of higher sales, higher profit, and wider margin supported the bullish case that assumed margin resilience and earnings power, rather than the cautious story of erosion.
The lesson is simple. When a bank like Société Générale is in question, anchor the thesis on reported net margin and return on equity targets, then see if later filings move those ratios toward or away from the original claim.
What You Are Paying For In Société Générale Today
Société Générale now trades at €64.41, with this bullish Narrative arguing that its Fair Value sits above the current price. The focus is on whether cost cuts, digital French retail, and capital-light activities can keep supporting return targets and shareholder payouts.
Your key test is whether Société Générale can actually deliver the planned cost base reduction and IT and AI savings so that group cost to income falls below 55% while CET1 stays above 13%.
"The main thing that has to go right is that Société Générale Société anonyme delivers the planned further cost base reduction, IT and AI savings, and French retail transformation so that group cost to income moves below 55% while maintaining a CET1 ratio above 13% and a cost of risk near 25 to 30bp."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Société Générale
Once you understand Société Générale, it is natural to look sideways. Another large lender is quietly pursuing a related angle.
Instead of French retail restructuring, this institution leans on digital channels and AI tools to reach customers and streamline support.
The same kind of client who wants smoother online banking with Société Générale also wants quicker decisions, richer insights and fewer manual steps elsewhere.
An American institution is trying to meet that demand by tying together deposits, cards, wealth tools and workplace access inside one tech heavy ecosystem.
If that approach resonates, the open question is how much value more engaged, multi product relationships might ultimately shape for everyone involved.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 28% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com