


EN
NCR Voyix (VYX) Stock Looks Fully Priced After Its Rebound
NCR Voyix has bounced hard in recent weeks, yet the longer track record is still weak, which raises a simple question for anyone looking at the chart today. Is the current share price giving you a fair deal based on what the business earns?
- The stock is down 63.7% over 5 years, so the key issue is whether the earnings now support a recovery from that kind of drawdown.
- Recent news points to lower hardware exposure and more software and payments activity, which can shift how investors think about the durability and growth potential of NCR Voyix's profit pool.
- The analysts covering NCR Voyix have run their own numbers. See what analysts think NCR Voyix's shares could be worth.
The stock's next move may depend on whether NCR Voyix's current earnings profile really lines up with where the market is pricing the shares today.
If you are weighing NCR Voyix after this earnings driven rebound, it can help to cross check your thesis against a wider set of software and payments focused companies using a focused screen such as our screener containing 19 high quality undiscovered gems.
Has NCR Voyix Run Too Far on Earnings?
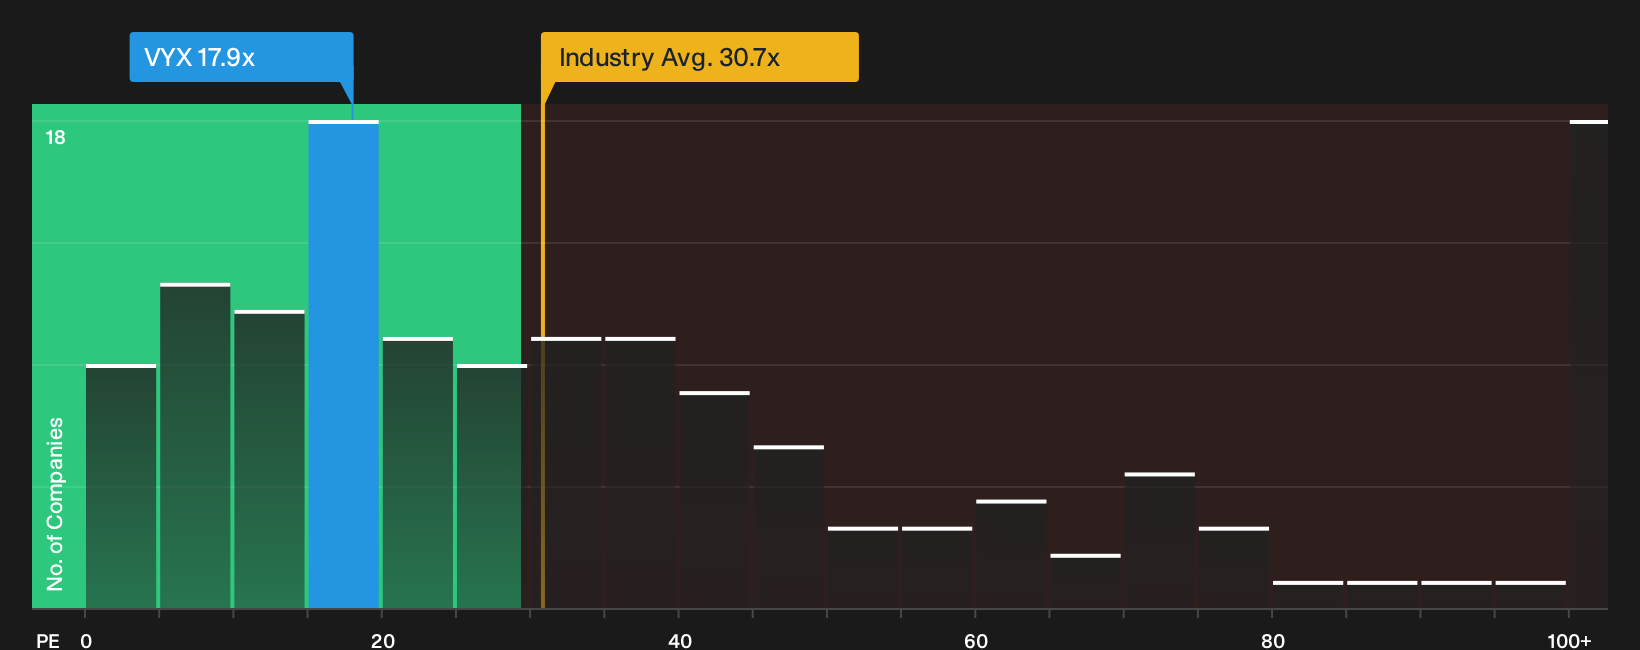
The P/E ratio fits NCR Voyix because the story the market cares about right now is earnings rather than asset backing. On this metric, the stock trades at about 17.9x earnings, compared with roughly 30.7x for the wider software group and a peer average near 33.4x. That gap indicates investors are putting a lower earnings tag on NCR Voyix than on many software and payments peers.
The fair multiple implied by the valuation model comes in lower than where NCR Voyix currently trades, so on this framework the shares screen as overvalued. Because the latest quarterly update showed revenue under pressure while profitability improved and contract value expanded, the current P/E appears more like a bet that the earnings mix shift toward software and payments holds together. If you are weighing that trade off against the implied premium to the fair benchmark, it is worth stress testing whether the recent earnings rebound and contract wins are enough to justify paying this P/E. Explore the numbers behind NCR Voyix's P/E valuation.
The NCR Voyix Narrative: What Would Justify Today's Price?
NCR Voyix Narratives pick up where the P/E puzzle leaves off by explaining which assumptions about future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today's quote. These narratives are available on Simply Wall St's Community page. Each narrative treats fair value as a thesis about NCR Voyix's business that you can watch play out over time, rather than a one-off snapshot.
Bullish and bearish NCR Voyix narratives both focus on the shift toward software and payments, yet they reach very different conclusions on what that mix is worth.
Bull case: 35% undervalued
"Execution on the approximately US$90 million 2026 cost program together with about a 20% payroll reduction since the ATM spin opens room for NCR Voyix to reweight spending toward product and go to market initiatives..."
Discover why this Narrative puts NCR Voyix at 35% undervalued.
Bear case: 20% overvalued
"Although adoption of the Voyix Commerce Platform and Aloha Next includes 25 signed customers and hundreds of millions of contracted value, the fact that this still represents a small share of the installed base means any slowdown in converting trials and labs into full rollouts could limit software ARR growth and keep total revenue closer to flat..."
Explore why this Narrative puts NCR Voyix at 20% overvalued.
Before acting on NCR Voyix's valuation, there is one more piece to check
The people steering NCR Voyix, how they are rewarded and what they prioritize can heavily influence whether any valuation thesis holds up over time. See who runs NCR Voyix and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com