


EN
Lumentum (LITE) Stock Still Seems Fully Priced On Sales
Lumentum Holdings has seen its share price move sharply in recent years, and the agreed all stock takeover by Marvell now puts an even brighter spotlight on what investors are paying for each dollar of its sales. With such a large deal on the table and a volatile trading record around it, the open question is whether the current valuation of Lumentum is well aligned with the scale and quality of its revenue base.
- Over the past 3 years the stock has delivered a gain that is well into double digit multiples, which puts substantial weight on whether that move is backed up by its sales performance.
- The planned US$115b all stock acquisition by Marvell, including a 23.9% premium for Lumentum investors, ties the future value of the business to how its lasers and optical products can convert current contract wins and AI related demand into sustained revenue streams.
- The analysts covering Lumentum Holdings have run their own numbers. See what analysts think Lumentum Holdings's shares could be worth.
The issue now is whether the price investors see on screen today is justified by Lumentum Holdings' sales when judged against the Fair Ratio benchmark.
If you want to test the same Fair Ratio question on AI infrastructure plays beyond Lumentum Holdings, scan the 53 AI infrastructure stocks.
Has Lumentum Holdings Run Too Far on Sales?
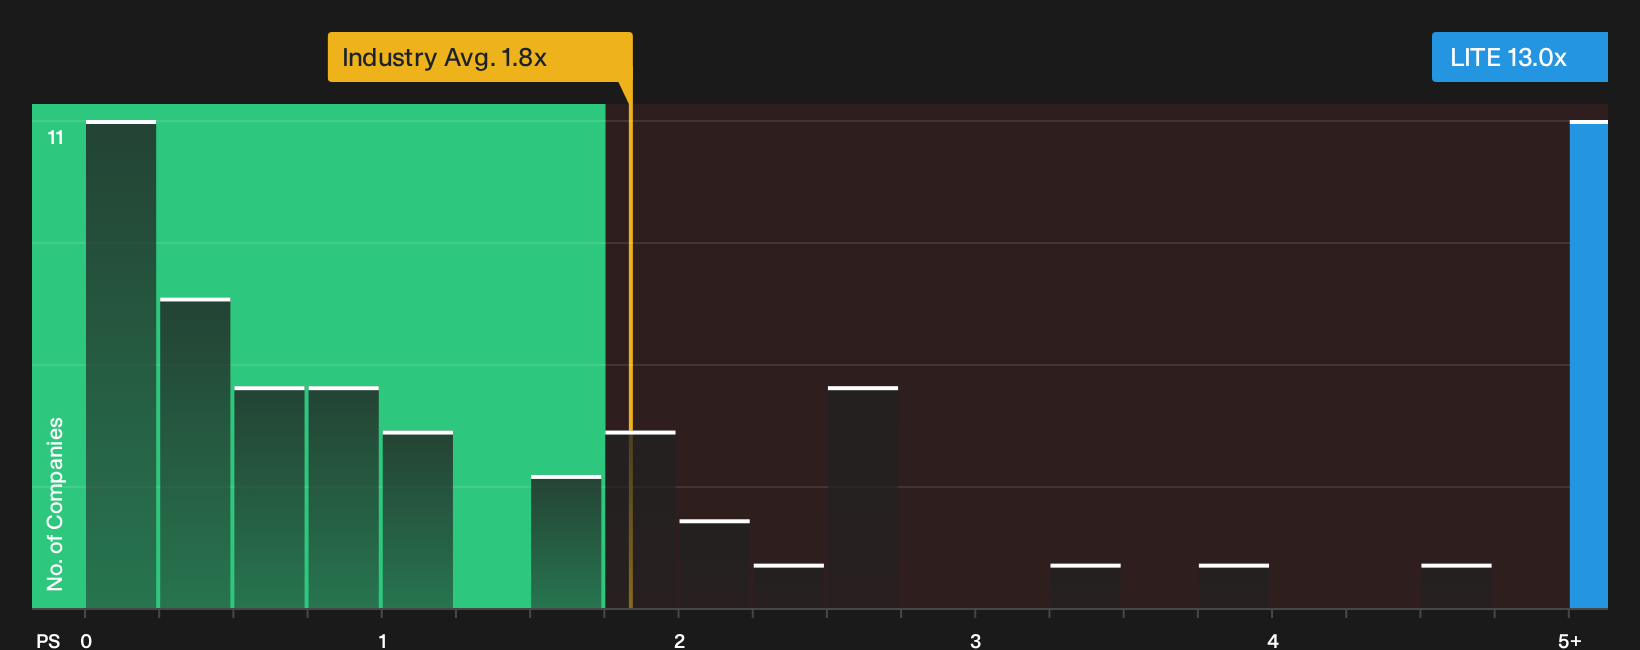
The P/S ratio suits Lumentum Holdings because investors are currently focused on how much they are paying for its optical and AI-related revenue stream. On this metric, the stock trades on a P/S of 13.0x, which is well above the Communications industry average of 1.8x and meaningfully higher than the 10.2x peer group level.
Marvell’s planned all-stock takeover at a premium has likely helped anchor that rich multiple, since the agreed terms effectively validate a higher revenue tag for Lumentum than most sector players achieve. Even so, the current P/S sits above the Fair Ratio benchmark you would expect for this business based on its size, margins and risk profile, which points to Lumentum Holdings looking overvalued against this tailored sales-based yardstick. Explore the numbers behind Lumentum Holdings's P/S valuation.
The Lumentum Holdings Narrative: What Would Justify Today's Price?
Narratives for Lumentum Holdings pick up where the valuation puzzle leaves off, spelling out which paths for future growth, profitability and earnings power would need to play out for the stock to be worth meaningfully more or less than it is today on Simply Wall St's Community page. Instead of a single output from a ratio or model, they unpack the future business conditions that result would rely on, so you can watch how those assumptions hold up over time.
One of the top community narratives on Lumentum Holdings: 89% undervalued
"For long-term value, the key variable to track is whether Lumentum can convert the current demand surge into sustainable free cash flow..."
Discover why this Narrative puts Lumentum Holdings at 89% undervalued.
Before you move on from Lumentum Holdings, there is one more factor to weigh
Lumentum Holdings is more than its P/S tag and takeover terms, because our broader checks have flagged specific concerns that could matter a lot to long term outcomes. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com