


EN
How Investors Are Reacting To Republic Services (RSG) Buyback Expansion
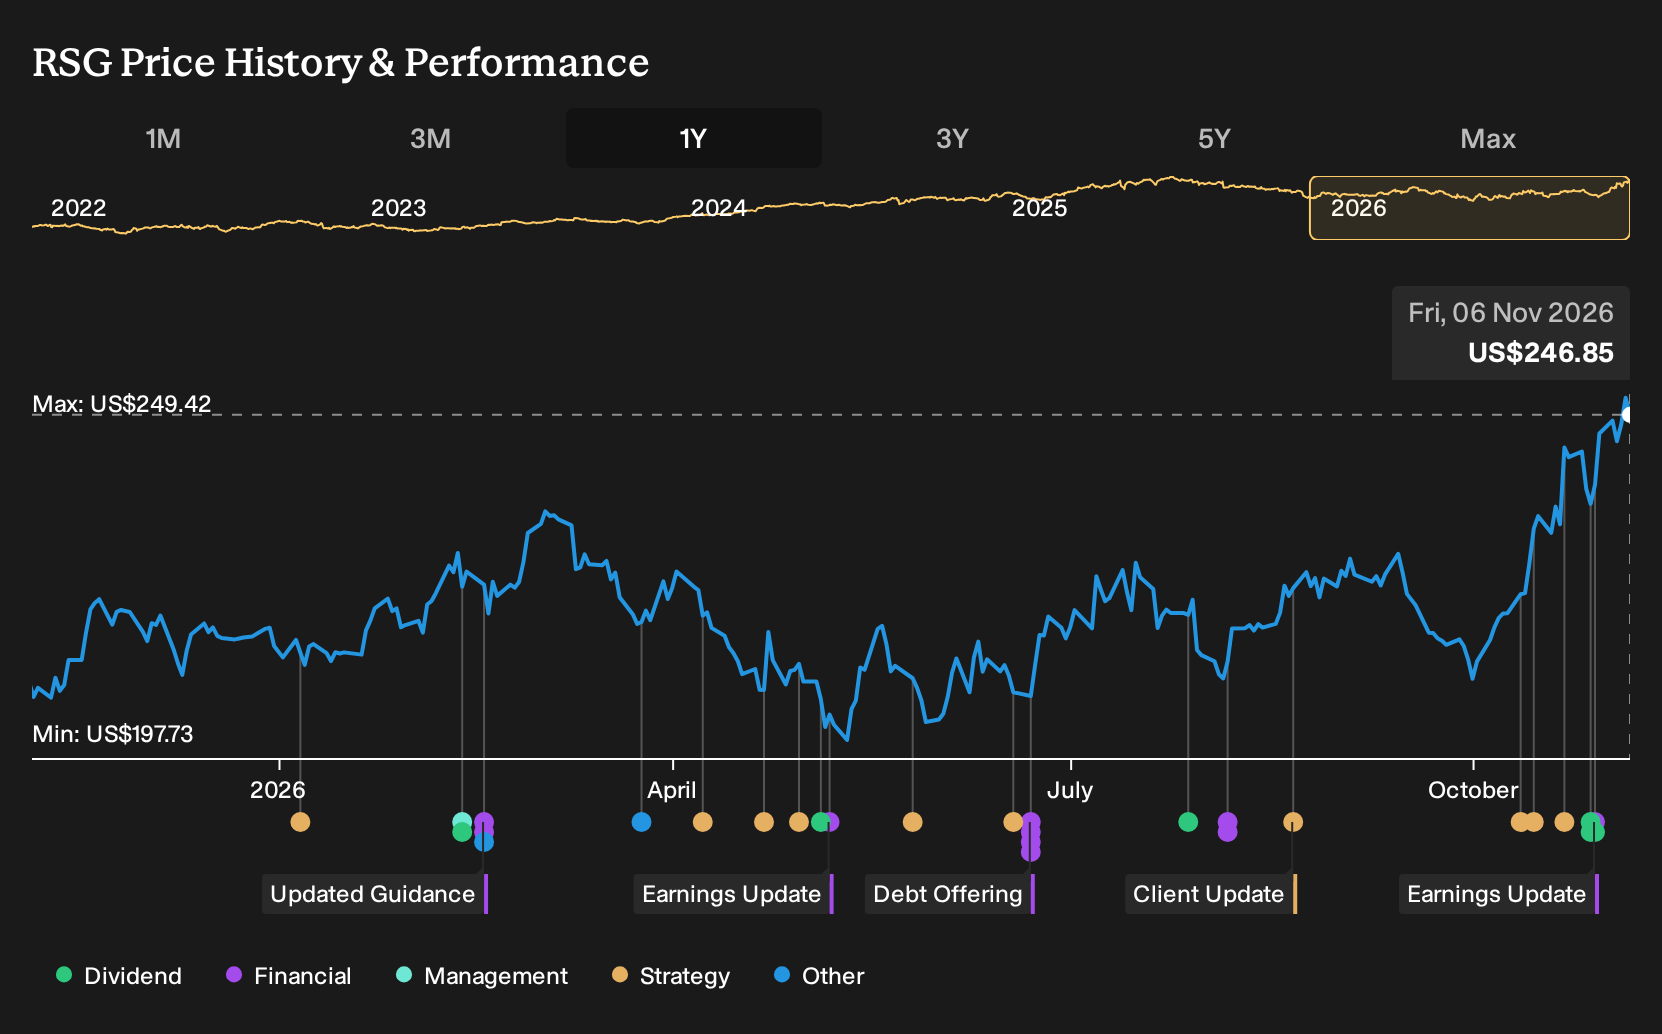
- Republic Services reported third quarter 2026 sales of US$4,559 million and net income of US$592 million, alongside a new US$5b share repurchase authorization that runs through December 2029 and an affirmed quarterly dividend of US$0.67 per share payable in January 2027.
- The combination of higher quarterly earnings per share from continuing operations, fresh buyback capacity, and ongoing cash dividends illustrates how Republic Services is currently balancing reinvestment needs with direct capital returns to shareholders.
- We will examine how Republic Services' expanded US$5b share repurchase plan could reshape the existing investment narrative around cash generation.
See how Republic Services' combination of buybacks, earnings and dividends compares with other companies using similar strategies by reviewing the list of solid balance sheet and fundamentals (25 results).
Republic Services Investment Narrative Recap
To own Republic Services, you need to be comfortable with a waste and environmental services business that leans on steady cash generation, efficiency gains from digital tools, and ongoing investment in recycling and renewable projects. The third quarter 2026 results, with higher sales and earnings per share than a year ago, support that operating story rather than changing it.
The key short term swing factor remains how effectively Republic Services manages softer organic volumes, contract churn in recycling, and potential labor disruptions while integrating acquisitions and executing on sustainability and RNG projects. The latest earnings do not remove those risks, but they suggest the business is currently absorbing them without a visible break in profitability.
The new US$5b share repurchase authorization through December 2029 is the most relevant update for this story. It sits alongside the affirmed US$0.67 quarterly dividend and ongoing capital spending on Polymer Centers, RISE digital tools, and renewable natural gas projects that are already outlined in the longer term narrative.
For you as a shareholder, this means the short term focus is whether Republic Services can keep funding that buyback and dividend while dealing with contract losses, high debt levels, and any wage or strike related pressure. Execution on earnings quality and cash generation will largely determine how meaningful that repurchase capacity becomes over time.
What The New Forecasts Assume For Republic Services
Republic Services' narrative projects US$19.9b revenue and US$2.8b earnings by 2029. Analysts are building this on 4.9% yearly revenue growth and an earnings increase of about US$0.6b from US$2.2b today.
Uncover why Republic Services' fair value indicates a 3% potential upside to its current price. This gap could narrow faster than many investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$253 and US$290, so retail investors already span a tight but meaningful range on Republic Services. You can weigh that against risks such as prolonged labor disputes or recycling contract pressure, which could influence how much of the recent buyback plan ultimately converts into durable performance.
Explore 2 other Republic Services fair value estimates, including one that suggests potential upside of as much as 17% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Republic Services research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Republic Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Republic Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Republic Services?
Once you have a handle on Republic Services, it helps to compare its profile with other companies that share similar strengths or offer a very different mix of risk and return. The Simply Wall St Screener can surface those alternatives quickly so you can pressure test your thesis and widen your watchlist.
- For investors who care most about balance sheet strength and fundamentals, review a list of solid balance sheet and fundamentals (25 results) that may offer a similar focus on financial resilience.
- If value is your priority and you want candidates where quality and pricing both matter, scan a 38 high quality undervalued stocks that combine robust financials with potentially more appealing valuations.
- When income is the goal and you want payouts that play a central role in your returns, consider companies in a 7 dividend fortresses that concentrate on higher-yield distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com