


EN
Axon Enterprise (AXON) Could Be 31% Undervalued As Guidance Cuts Test The Growth Story
Axon Enterprise (AXON) has been in focus after third quarter results missed market expectations, full year 2026 revenue guidance was trimmed due to delayed federal Dedrone projects, and a new US$1.2b Skydio drone investment was unveiled.
The immediate reaction has been sharp. The 1 day share price return declined 18.18% and the 7 day share price return fell 26.83%, contributing to a 44.45% share price decline year to date. However, the 3 year total shareholder return is still 43.62% and the 5 year total shareholder return is 83.67%. This points to longer term holders experiencing gains, while short term momentum has clearly faded as investors reassess Axon Enterprise after the guidance cut and Skydio commitment.
Spot opportunities around Axon Enterprise's reset by comparing it with a hand picked 38 high quality undervalued stocks that also pair strong balance sheets with meaningful cash generation.Axon Enterprise is still putting up growth numbers and leaning hard into drones and software, yet the share price has just been reset by almost half this year. Is that reset giving you a fair entry, or is it still a rich one?
Most Popular Narrative: 31% Undervalued
On the numbers, Axon Enterprise’s most followed narrative pegs fair value at $453.59 against a last close of $313. That gap puts the recent selloff in a different light and frames the current debate around how durable the growth and margin story really is.
Axon Enterprise continues to report revenue growth above 30% for multiple quarters and has now reached US$904 million in a single quarter, while future contracted bookings of US$15.1b support a long pipeline of deployments. If this sustained demand leads investors to place more weight on realized execution than on concerns around hardware margins or capital structure, the share price could trend higher than the bearish earnings and P/E assumptions imply, affecting both revenue and earnings expectations.
See why 8 investors see Axon Enterprise as 31% undervalued.
Result: Fair Value of $453.59 (UNDERVALUED)
Still, Axon Enterprise’s narrative could be tested if federal Dedrone delays persist, or if hardware heavy deals dilute margins faster than software can offset.
Find out about the key risks to this Axon Enterprise narrative.
Another Take On Axon Enterprise’s Valuation
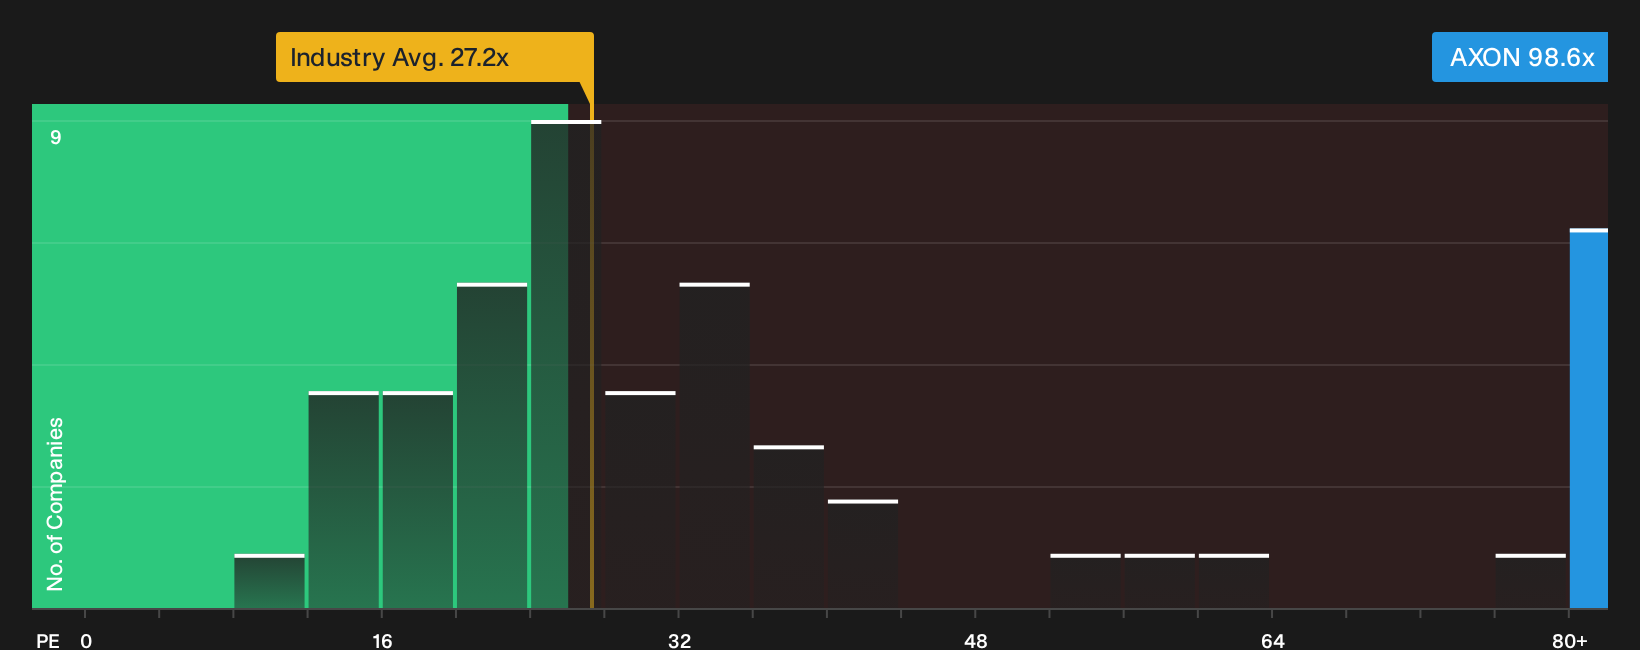
The fair value of $453.59 is based on analyst earnings forecasts and a rich P/E profile. On that same metric, Axon Enterprise trades at 98.6x earnings versus 27.2x for the US Aerospace & Defense group and a fair ratio of 38.6x, which points to clear multiple risk. Is the premium giving you comfort or concern?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling mixed on Axon Enterprise after this reset, or pulled in both directions by the data? Move quickly and weigh the 3 key rewards and 1 important warning sign against your own view before the narrative shifts.
Looking for more ideas beyond Axon Enterprise?
Axon Enterprise might be front of mind today, but your portfolio benefits when you line it up against other clear, numbers driven opportunities that fit your goals.
- Target potential mispricing by scanning a focused pool of opportunities through the 38 high quality undervalued stocks.
- Strengthen downside protection by filtering for companies with healthy finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for future leaders early by sorting through the 19 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com