


EN
Korn Ferry (KFY) Stock May Be Trading At A Discount To Earnings
Korn Ferry has delivered a strong share price run over the past few years, which puts fresh attention on what investors are really paying for its earnings today. With the stock recently closing at US$75.38, the key issue now is whether that level is well supported by the profits the business is generating.
- Over the past 3 years the share price has gained 69.1%, which raises the question of how fully the current earnings profile may already be reflected in the valuation.
- The company’s model in talent advisory and related services can influence how consistently earnings convert into cash, which matters for how investors judge the sustainability of the current profit base.
- There is a second opinion on Korn Ferry worth weighing. See what analysts think Korn Ferry's shares could be worth.
The stock’s next move may depend on whether Korn Ferry’s current price looks aligned with what its earnings can justify.
If you are evaluating Korn Ferry based solely on its earnings and are interested in other ideas built around clear valuation angles, a focused starting point is our 38 high quality undervalued stocks.
Does Korn Ferry Look Undervalued on Earnings?
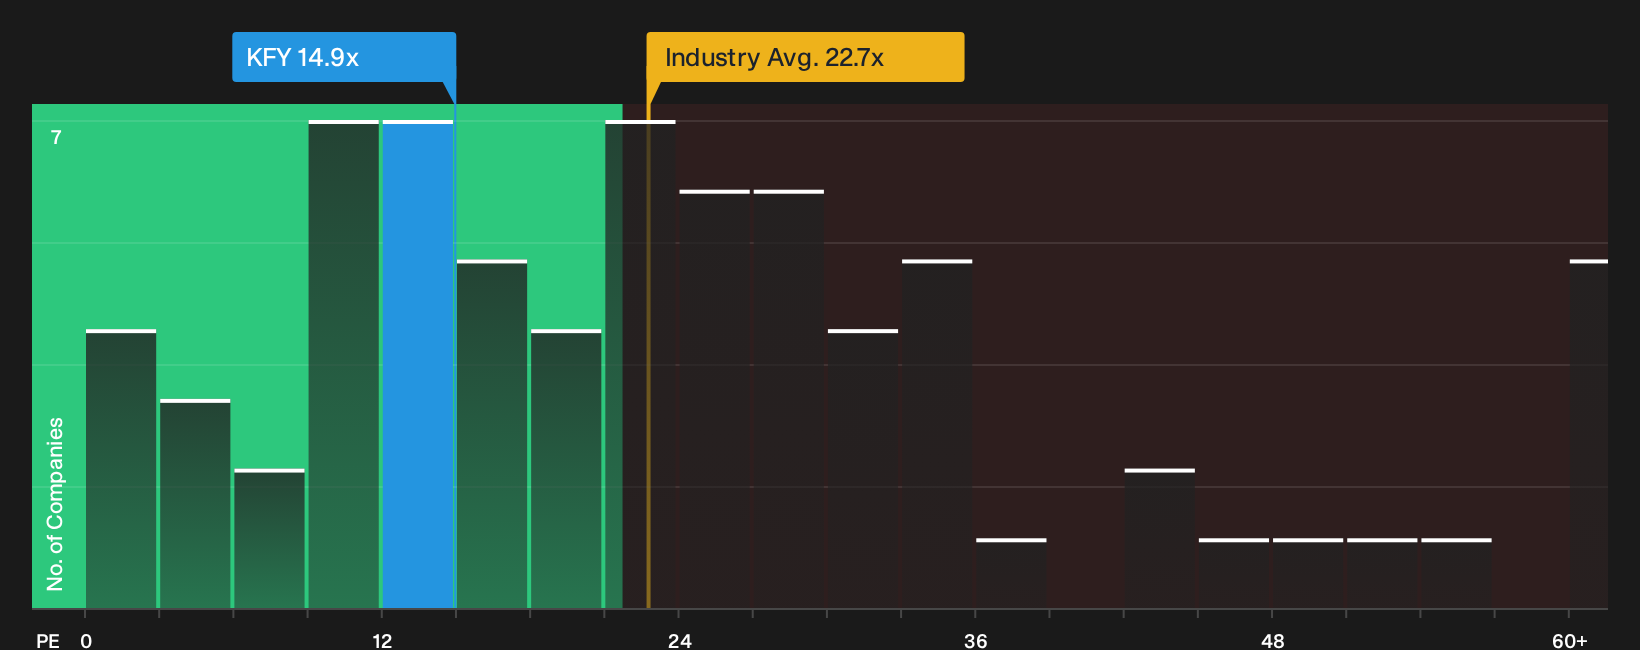
The P/E ratio suits Korn Ferry because earnings remain a core reference point for how investors judge professional services groups. At roughly 14.9x, Korn Ferry’s P/E sits well below the broader Professional Services average of about 22.7x and also under the peer group level near 40.9x. That gap indicates that the market is currently assigning a lower price tag per dollar of earnings than many similar listed firms receive.
The fair P/E that would typically be expected for Korn Ferry, based on its business profile and risk mix, comes out higher than where the shares trade today. Since the current multiple is below that tailored reference point, the pricing leans toward undervalued on this earnings lens, although the picture still depends on how you rate the quality and resilience of those profits. For anyone weighing Korn Ferry against other options, this kind of discount on the P/E line can be a useful starting signal rather than a conclusion. Explore the numbers behind Korn Ferry's P/E valuation.
The Korn Ferry Narrative: What Would Justify Today's Price?
Narratives for Korn Ferry pick up where the P/E puzzle leaves off by spelling out in plain terms which paths for revenue, margins and earnings would need to play out for the current share price to look meaningfully high or low. Instead of a single number from a ratio or model, they lay out the future that number relies on so you can watch how closely Korn Ferry's actual progress tracks that implied story over time on Simply Wall St's Community page.
One of the top community narratives on Korn Ferry: 16% undervalued
"The current valuation implies that the market is discounting Korn Ferry’s growing contracted backlog, AMS EBITDA ambitions, and rising cross solution referral rates..."
Discover why this Narrative puts Korn Ferry at 16% undervalued.
Before deciding what Korn Ferry is worth, look at who is steering it
Price multiples only tell part of the story, because the people setting priorities, taking capital decisions and rewarding themselves can tilt future outcomes in ways the P/E cannot show on its own. See who runs Korn Ferry and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com