


EN
Is Mueller Industries (MLI) Undervalued As Earnings Miss And Probe Raise Fresh Questions?
Mueller Industries (MLI) is back in focus after third quarter 2026 earnings per share came in below consensus and profit margins narrowed, prompting law firm Pomerantz LLP to open a securities investigation.
Recent trading tells a mixed story. Mueller Industries shares closed at US$52.96, with the 1 month share price return down 12.77% and the 3 month share price return down 23.14% after the earnings miss and investigation headlines. At the same time, the 3 year total shareholder return of about 187% and 5 year total shareholder return of about 272% still signal a long run record that many holders will compare against this year’s softer momentum.
Contrast Mueller Industries with other industrials that have been screened for resilient fundamentals and balance sheets by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
Mueller Industries now sits at a price that reflects both the recent stumble and a long stretch of strong total returns. After this pullback, the question is whether the bigger share of the valuation opportunity is already used up or still in front of you.
Price-to-Earnings of 13.4x: Is it justified for Mueller Industries?
At a P/E of 13.4x, Mueller Industries is priced well below both its Machinery industry peers and several fair value reference points, even after the recent share price drop to $52.96.
The P/E ratio compares what investors pay today to the earnings the business generates. For a manufacturer like Mueller Industries that produces copper, brass, and aluminum products across plumbing, HVAC, and industrial markets, earnings are a key yardstick because cash generation and profitability drive the investment case more directly than hype or optionality.
Here, the gap is wide. Mueller Industries trades at a P/E of 13.4x, while the US Machinery industry averages 23.2x and direct peers sit around 30.8x. Against an estimated fair P/E of 22.6x, the current level suggests the market is assigning a materially lower multiple than the earnings profile might support. This is a valuation gap that could close in either direction as sentiment and results evolve.
Explore the SWS fair ratio for Mueller Industries.
Result: Price-to-Earnings of 13.4x (UNDERVALUED)
Still, the securities investigation and the recent earnings miss could pressure sentiment further if disclosures change investor confidence in Mueller Industries or in its reported profitability.
Find out about the key risks to this Mueller Industries narrative.
Another View on Mueller Industries Using Cash Flows
Price tells one story for Mueller Industries. The SWS DCF model adds another by valuing the business on estimated future cash flows, which points to a fair value of about $66.85 per share versus the current $52.96. That gap looks like a discount, but it also raises a question about how durable those cash assumptions really are for you as an investor.
Look into how the SWS DCF model arrives at its fair value.
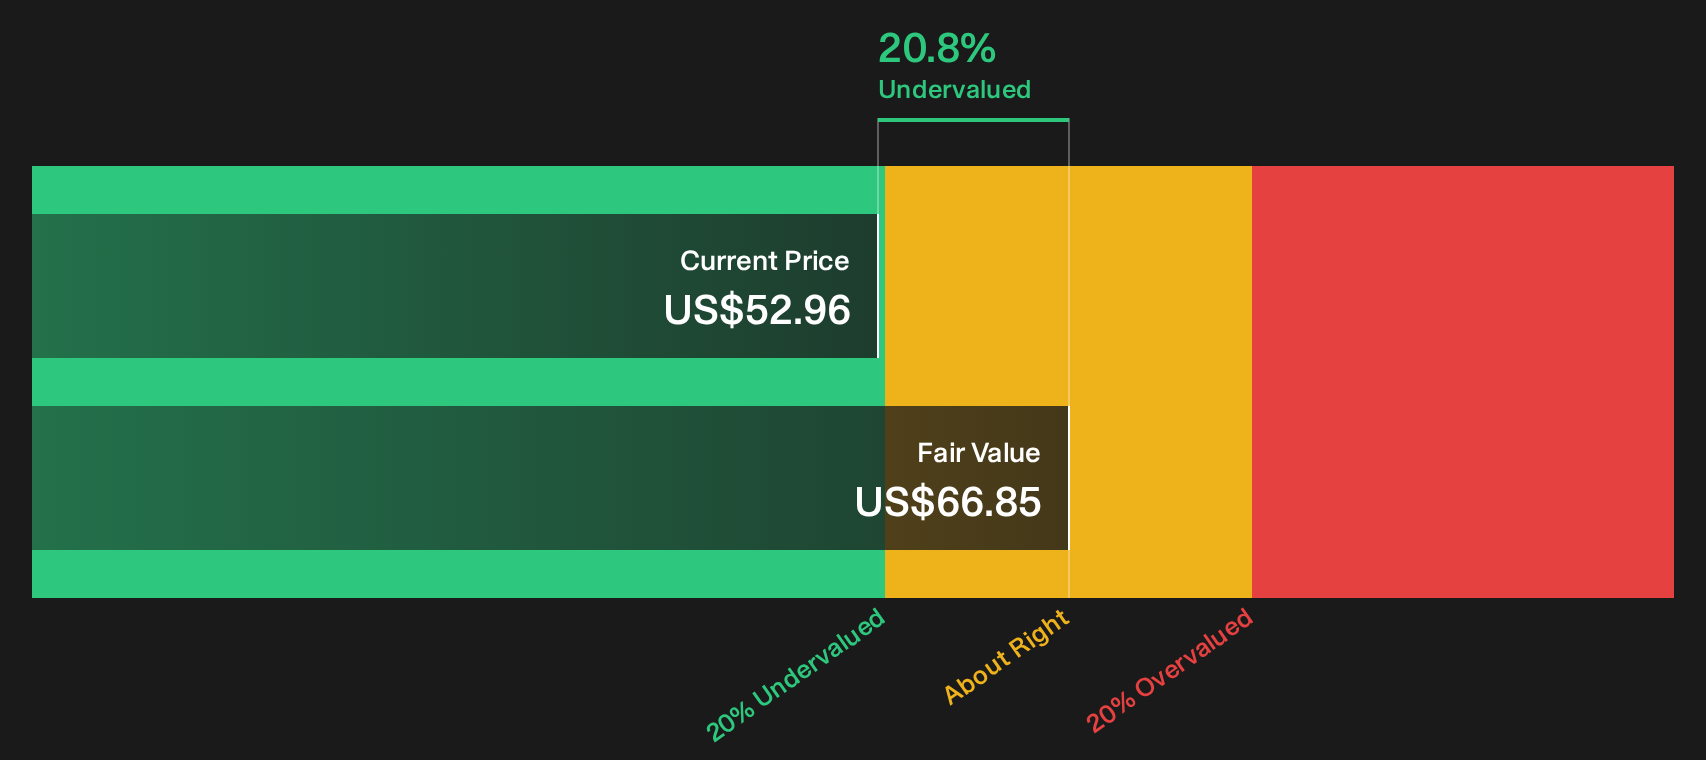
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mueller Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 38 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mueller Industries can feel messy. Act while the facts are fresh and build your own view using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mueller Industries?
If Mueller Industries has sharpened your attention on valuation and quality, do not stop here. Use focused screens to surface other opportunities that fit your style.
- Target potential mispricings by scanning for quality companies trading at a discount using our 38 high quality undervalued stocks.
- Build an income focused watchlist by zeroing in on companies with higher yields through the 7 dividend fortresses.
- Prioritize resilience by filtering for businesses with sturdier finances using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com