


EN
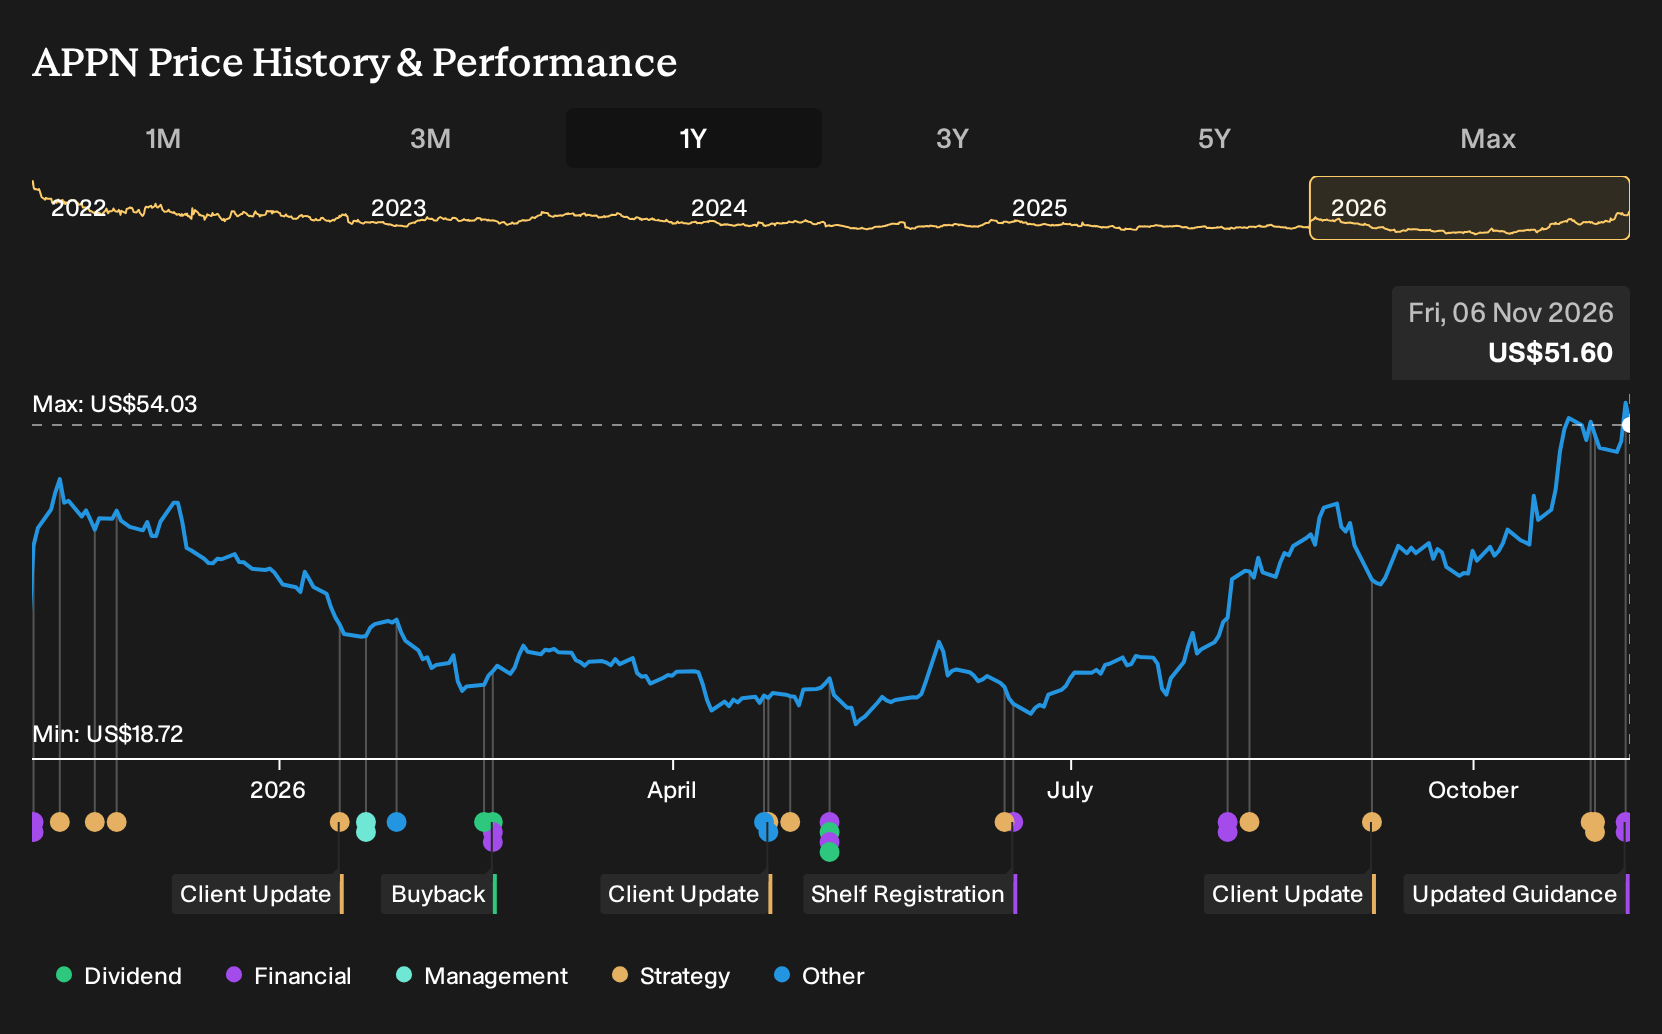
Earnings Beat Will Impact Appian Stock Investors
- Appian reported Q3 2026 revenue of US$234.63 million and net income of US$12.34 million, and issued Q4 and full year 2026 revenue guidance that points to continued expansion of its subscription driven platform.
- The business also secured Impact Level 5 authorization for Appian Defense Cloud and supported the US Army's rapid rollout of its new TACTMIS munitions system, highlighting growing mission critical usage in highly regulated public sector workloads.
- Next comes an assessment of how Appian's raised guidance and expanding AI heavy cloud deployments could influence the existing investment narrative around the stock.
Appian Investment Narrative Recap
To own Appian, you need to believe its low code and AI platform can keep winning larger, mission critical workflows in regulated sectors while turning that traction into steadier profitability. The raised Q4 and 2026 revenue outlook, alongside Q3 net income of US$12.34 million, keeps that execution story intact in the near term.
The key short term catalyst is continued cloud subscription and AI tier adoption that supports the new revenue guidance range of US$873 million to US$877 million. The biggest risk is still that heavy spend on product and sales, combined with customer downsells, caps margin progress and leaves the business exposed if demand softens.
The most relevant fresh data point for that thesis is the new guidance itself. Management now expects Q4 2026 revenue between US$233 million and US$237 million and full year revenue between US$873 million and US$877 million. Those figures sit alongside a nine month loss of US$1 million, which keeps profitability finely balanced.
For you as an investor, this means execution risk is shifting from pure growth to the mix of growth and discipline. The guidance, combined with Q3 profitability, gives Appian a chance to show that expanding AI heavy cloud workloads and regulated sector wins can support both recurring revenue and the margin improvement many holders are watching closely.
Analysts expect Appian's revenues to reach US$1.1b and earnings to reach US$141.0 million by 2029, implying forecast annual revenue growth of 10.6% and an earnings swing of roughly US$151.6 million from a current loss of US$10.6 million.
Uncover how Appian's fair value indicates a 33% potential downside to its current price, a premium that may not be sustainable.
Exploring Other Perspectives
One bullish twist on Appian focuses on profitability, not just AI wins. Before this guidance and Defense Cloud news, the most optimistic analysts were already modeling profit margins rising toward 21.5% and earnings reaching about US$235.3 million by 2029, far above consensus. That stronger earnings story may evolve again once this new data is fully priced into forecasts. Use it as a cue to compare several viewpoints, not to anchor on a single narrative.
Explore 3 other Appian fair value estimates, including one that suggests potential upside of as much as 16% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Appian research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Appian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Appian's overall financial health at a glance.
Looking for more investment ideas beyond Appian?
If Appian's mix of AI heavy cloud workloads and tight execution has your attention, use that same framework to scan the wider market. The Simply Wall St Screener can help you quickly filter for other businesses that fit the balance of quality, resilience, and price that matches your own risk profile.
- If capital preservation is a priority, focus on resilience first and see which companies qualify as 31 resilient stocks with low risk scores that may suit a more cautious approach.
- If balance sheet strength matters most, start with financial robustness and work through the list of solid balance sheet and fundamentals (25 results) to find businesses with room to invest through different cycles.
- If you are hunting for underappreciated opportunities, scan for quality at a discount using the 38 high quality undervalued stocks and build a watchlist of ideas to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com