


EN
What Vodafone Group Bulls Got Right
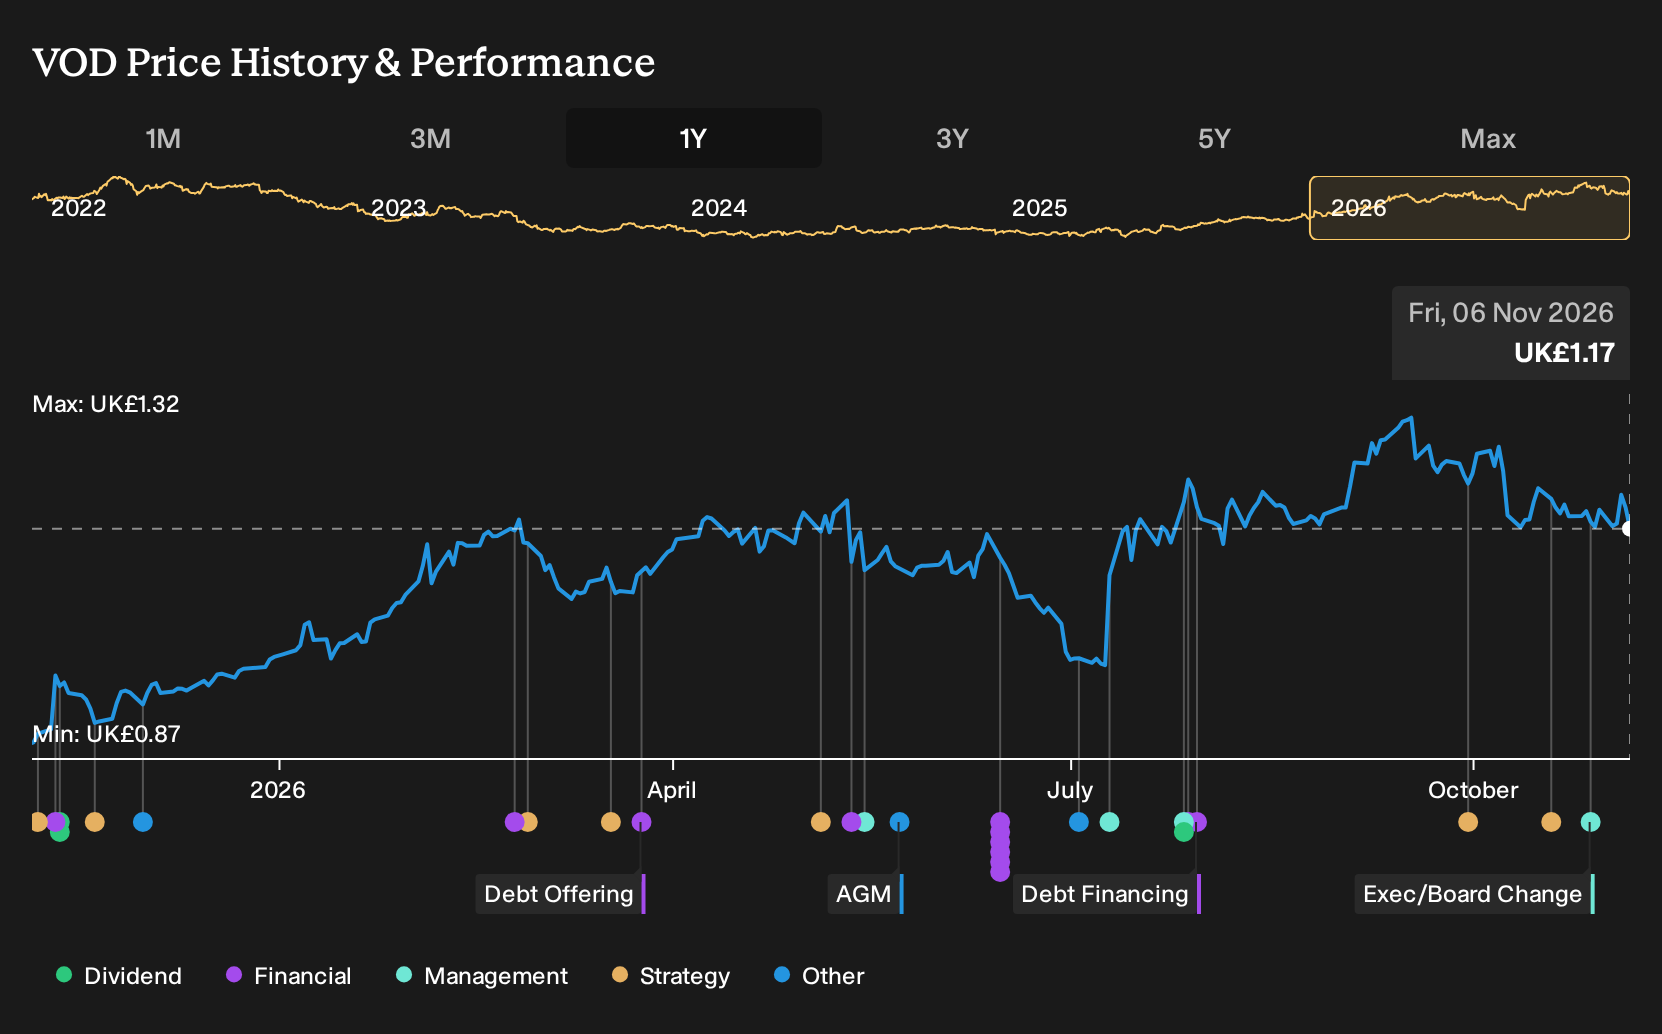
Vodafone Group has been busy reshaping itself, right down to buying out CK Hutchison’s remaining stake in VodafoneThree UK and pushing harder into 5G and digital services. Holding Vodafone Group over the past year would have returned 37.1%, including dividends. If you had been deciding back on 6 November 2025, what conviction about those merger synergies, IoT ambitions and European headwinds would you have needed to act with confidence?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Vodafone Group. See which of 41 power grid technology and infrastructure stocks may still merit a closer look.
The Two Vodafone Group Stories Investors Had To Weigh
The shares cost £0.87 at the start of the period, and Vodafone Group sat between two sharply different stories about what might come next.
On the upbeat side, the bull narrative put Fair Value at £1.36, based on the view that IoT, 5G services, and asset-light digital platforms could support sustained high-margin revenue and cash flow growth.
The more cautious bear narrative pointed to a Fair Value of £0.60, stressing that rising European compliance costs and declining legacy voice and SMS income could erode profitability despite efficiency efforts.
What The Results Changed For The Vodafone Group Story
Vodafone Group’s H2 2026 report showed revenue at €40,461m and a much smaller loss of €289m, so net margin moved from an 11.1% loss to a 0.7% loss. That shift supported the bull case on operational progress, yet keeping profitability in the red left the cash generation and high margin promise only partly backed. Overall, the evidence cut both ways.
The key assumption here was margin repair. For another telecom stock, you would track net margin and absolute profit across several periods and test whether management’s efficiency and integration claims show up in those two lines.
What Vodafone Group’s Price Already Bakes In
Vodafone Group now trades at £1.17, and this Narrative’s Fair Value sits below that level, so the valuation view leans cautious even after a 37.1% gain over the past year.
The Narrative hinges on whether Vodafone converts German repair, Africa momentum and VodafoneThree UK integration into sustained free cash flow growth. A buyer today would be assuming that execution lands. How do the flagged German EBITDA and pricing risks weigh on that cash flow story?
"Although Vodafone Group points to continued good growth in adjusted EBITDAaL and free cash flow and has set an ambition for double digit free cash flow growth, the expectation that Germany's EBITDA will decline again in FY 27 due to TV and mobile pricing headwinds introduces a risk that group earnings fall short of these goals if the largest European market does not stabilise as assumed."
One Narrative disagrees with today's price. → See where this Narrative says Vodafone Group should trade
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 33% below our estimate - raise long term capital into renewable and regional private equity mandates.
- Company 2 - 28% below our estimate - win larger geotechnical contracts as complex infrastructure projects demand tighter risk and cost control.
- Company 3 - 41% below our estimate - advance a late stage drug portfolio intended to offset patent expiries without major acquisitions.
That is three of the list. See every one of the 14 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com