


EN
Does Soft Third Quarter Earnings Change The Bull Case For Vulcan Materials (VMC)?
- Vulcan Materials reported past third quarter 2026 results showing sales of US$2,184.6 million and net income of US$362.3 million, with earnings per share from continuing operations slightly below the prior year quarter.
- The nine month 2026 figures showed higher sales of US$6,096.3 million and net income of US$851.2 million, which points to resilience in Vulcan Materials' aggregates focused operations despite softer third quarter performance.
- We will now see how Vulcan Materials' investment narrative is influenced by steady nine month earnings despite softer third quarter sales.
Scan how Vulcan Materials stacks up against a hand picked 38 high quality undervalued stocks that pairs solid fundamentals with prices that may not fully reflect their underlying earnings power.
Vulcan Materials Investment Narrative Recap
For a shareholder in Vulcan Materials, the core belief is that aggregates demand from public projects and large private builds will keep supporting the quarry-heavy model, while pricing and cost control do the heavy lifting on earnings. The latest quarter showed slightly softer sales and earnings per share, but nine-month results still point to operational resilience rather than a break in that thesis.
In the near term, the key swing factor remains how pricing and efficiency offset diesel, labor and other operating costs as infrastructure work ramps through Vulcan Materials' markets. The main risk is that end market volumes or government spending come in weaker than expected, which would limit shipments, pressure margins and reduce operating leverage on the existing asset base.
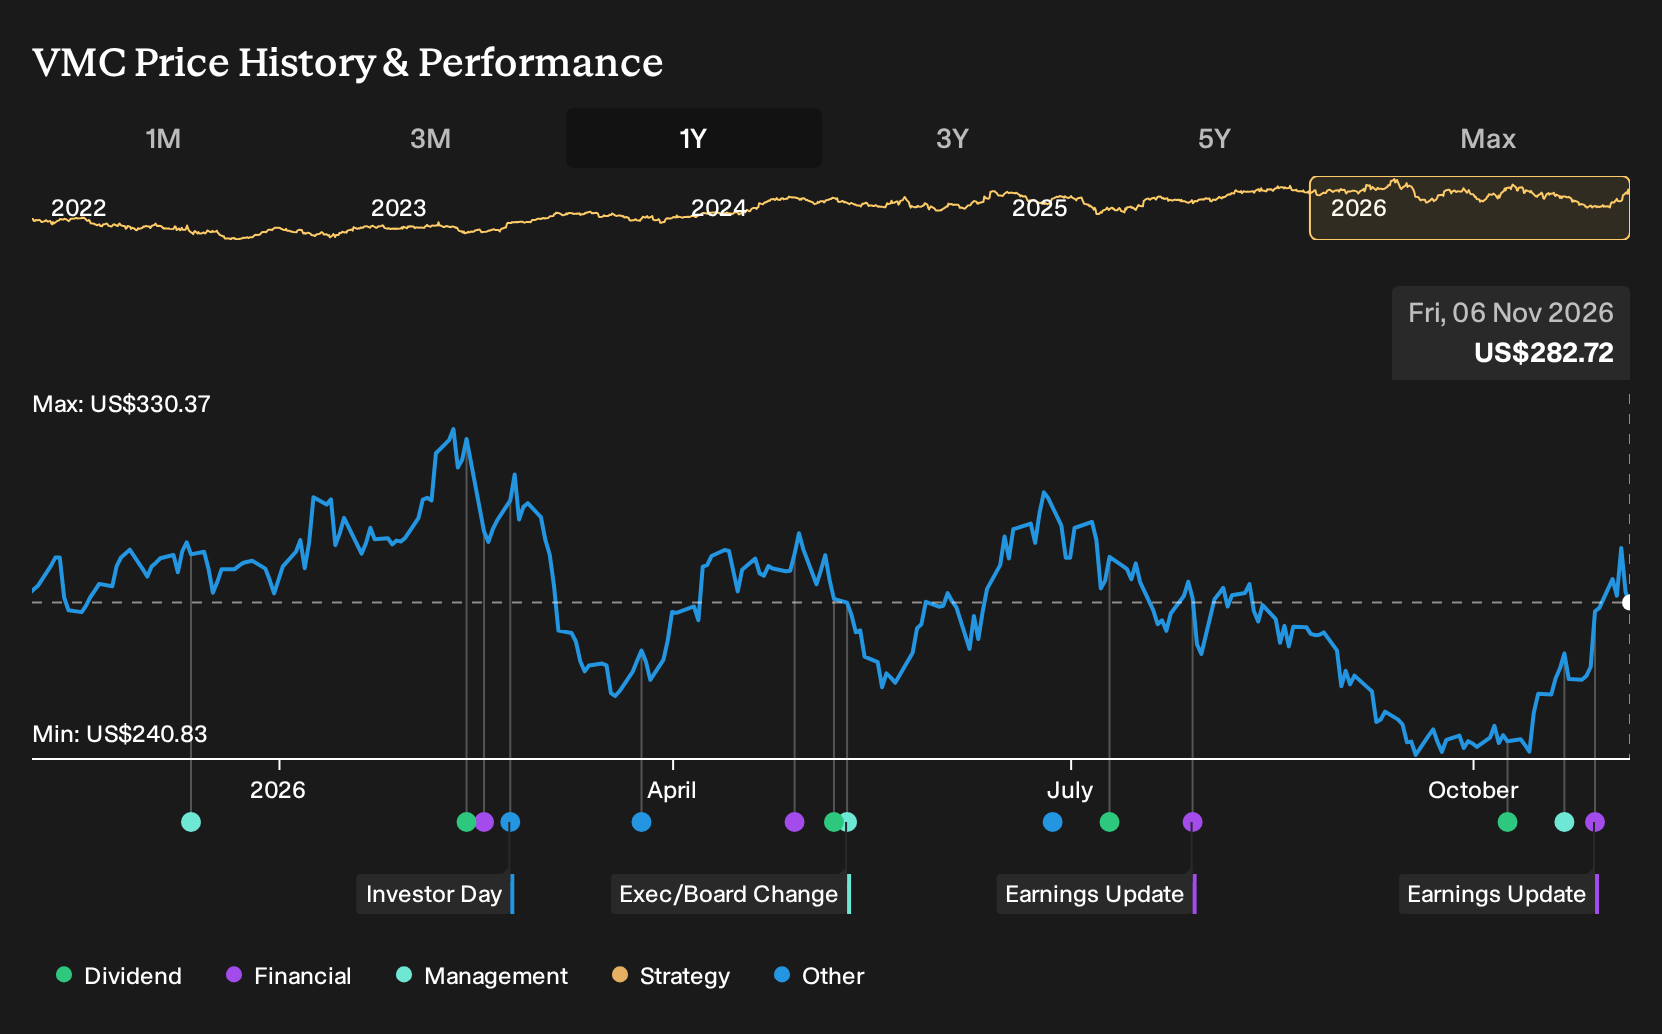
The most relevant update for this story is the third quarter and nine-month 2026 earnings release itself, since it refreshes your view on how Vulcan Materials is handling costs and mix while leaning into infrastructure and nonresidential work. Sales of US$2,184.6 million for the quarter, with net income of US$362.3 million, show a business that is still solidly profitable even in a softer patch.
Across the first nine months, revenue of US$6,096.3 million and net income of US$851.2 million suggest that pricing, portfolio focus on aggregates and prior efficiency moves continue to matter more than a single quarter’s volume wobble. For catalysts, the link to large project backlogs and infrastructure awards remains important, while risks such as diesel inflation, high debt funding and any slowdown in awards can quickly change how those earnings translate into cash and shareholder value.
Vulcan Materials’ narrative projects US$9.4b revenue and US$1.5b earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about US$400m from US$1.1b today.
Uncover why Vulcan Materials' fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts treated infrastructure exposure as a powerful catalyst for Vulcan Materials, assuming revenue could reach about US$10.1b and earnings about US$1.8b by 2029. You can see how that upbeat view, set before this latest earnings release, might now be tested and potentially revised in very different ways.
Explore 4 other Vulcan Materials fair value estimates, including one that suggests there could be as much as 29% potential upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vulcan Materials research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vulcan Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vulcan Materials' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vulcan Materials?
If this Vulcan Materials review has sharpened your thinking but you want a broader hunting ground, the Simply Wall St Screener can help you line up other companies that match your risk tolerance and return goals. Use it to compare balance sheets, income profiles and dividends side by side so Vulcan Materials sits in context, not in isolation.
- For investors who care most about valuation and fundamentals, scan a curated 38 high quality undervalued stocks, where cash flows and balance sheets do more of the talking than the share price.
- If capital preservation and smoother sleep matter more than chasing the highest upside, filter for a 31 resilient stocks with low risk scores that scores well on financial health and volatility.
- When you want quality businesses that the market may not be fully focused on yet, use the 19 high quality undiscovered gems to surface underfollowed stocks with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com