


EN
How Third Quarter Losses At International Paper Stock Have Changed Its Investment Story
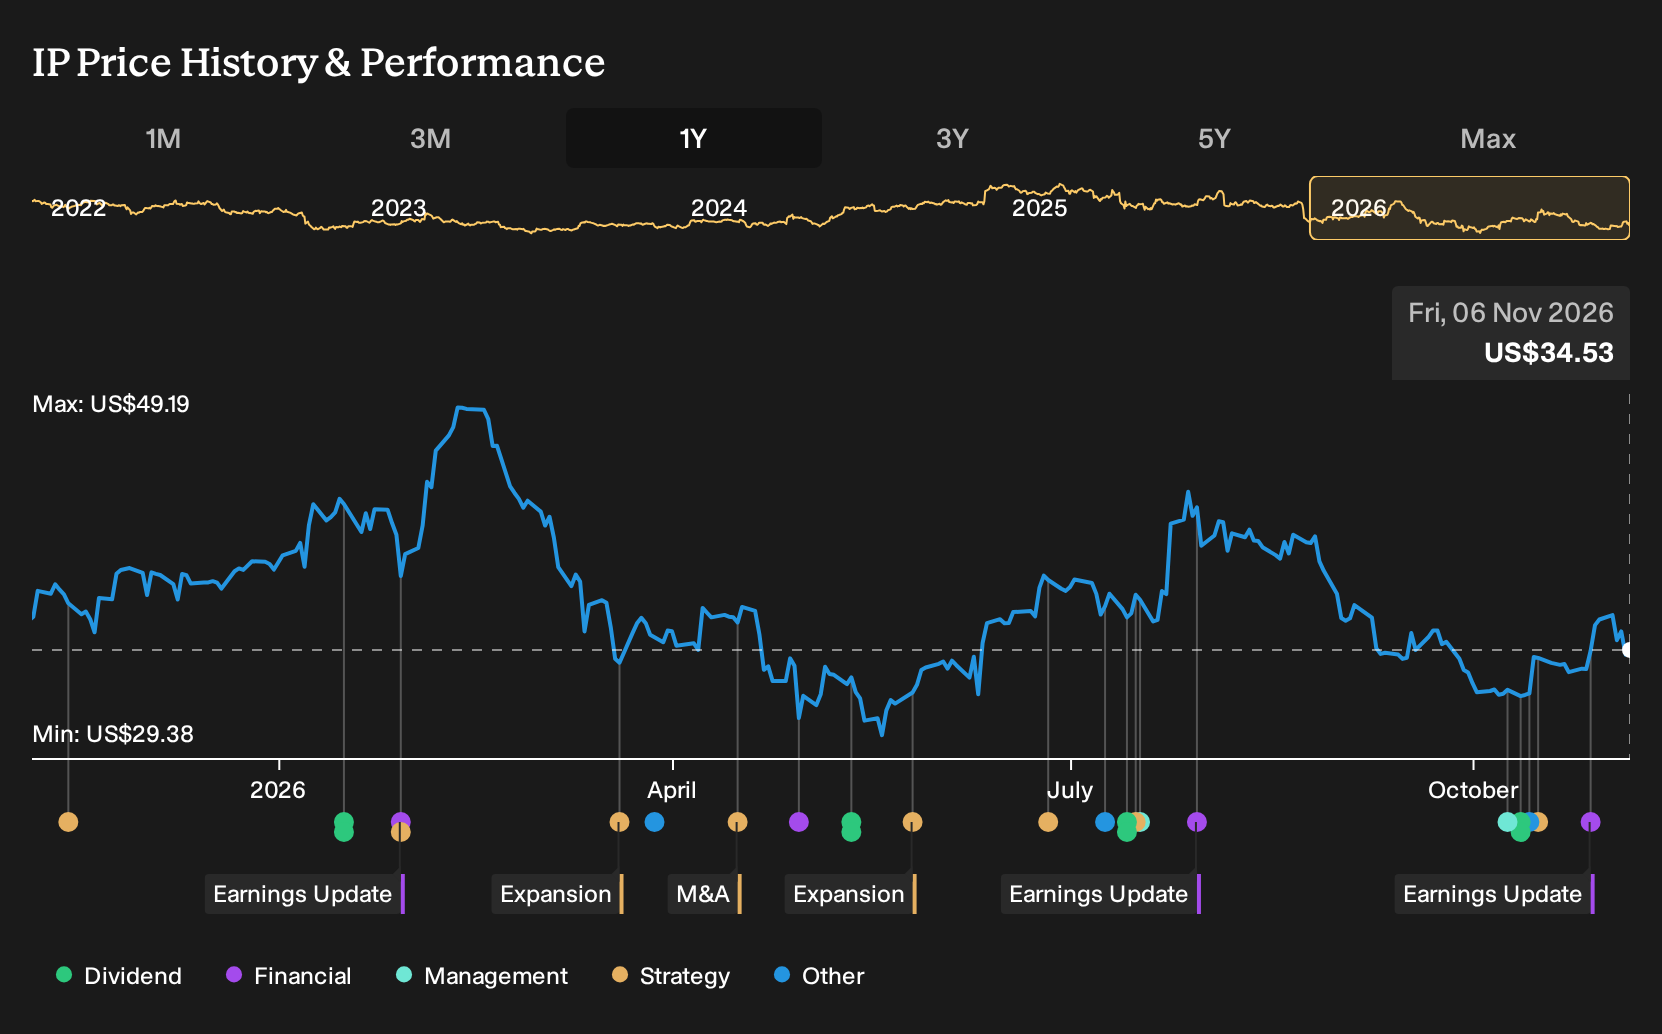
- International Paper reported third quarter 2026 sales of US$6,197 million and a net loss of US$1,126 million, with basic loss per share from continuing operations of US$2.07.
- The business generated higher nine month 2026 sales of US$18,172 million compared with the prior year period, while still recording a loss and higher loss per share from continuing operations, highlighting ongoing pressure on profitability despite top line resilience.
- This article reviews how International Paper's investment narrative relates to these third quarter losses from continuing operations and discusses the potential implications.
Scan beyond International Paper's latest loss, and compare it with other materials and industrials stocks that currently screen as list of solid balance sheet and fundamentals (25 results).
International Paper Investment Narrative Recap
To own International Paper, you need to be comfortable with a packaging business that is still loss making but tied to everyday demand for boxes, shipping containers and fiber based packaging. The big near term swing factor is whether cost inflation, especially energy and transport, eases enough for pricing and cost savings to show up cleanly in results.
The latest quarter keeps that tension front and center. Sales held close to last year, yet the loss from continuing operations widened on a per share basis, which keeps pressure on margins and interest coverage. The key risk right now is simple. Profitability may stay weak if macro and cost headwinds persist longer than the cost out and footprint changes take to deliver.
The third quarter earnings release is the key reference point. International Paper reported US$6,197 million in sales and a net loss of US$1,126 million, with basic loss per share from continuing operations of US$2.07. Nine month revenue reached US$18,172 million, while the business still reported a loss and a higher loss per share from continuing operations compared with the prior year.
Those numbers keep the spotlight on execution of the packaging footprint overhaul and structural cost removal plans that management has laid out. For you as a shareholder, the operational question is whether steady top line performance can eventually meet lower unit costs, more reliable mills and tighter containerboard supply, or whether persistent inflation and muted demand keep earnings and cash generation under strain.
What Analysts Are Building Into The International Paper Story
Analysts are effectively asking you to weigh International Paper as a business that is loss making today but modeled to move back into the black over the next several years. The assumptions behind that pivot are specific rather than vague sentiment, which gives you some concrete markers to track against the third quarter loss from continuing operations.
On the top line, the consensus view folds in 3.7% yearly revenue growth over the next three years. That pace is being linked to corrugated packaging demand, mix, and the impact of footprint changes rather than a sharp cyclical rebound, so it is worth treating it as a working model rather than a given outcome.
Earnings expectations are far more aggressive than the revenue path. Analysts frame "earnings today" for International Paper at a loss of about US$3.4b and then project a swing to US$1.8b of profit by 2029. That is an earnings change of roughly US$5.2b from current levels, which is a very large shift in absolute terms and hinges on margins moving from a reported loss position of about 14% to a positive margin of 6.8% in three years.
Valuation work in the consensus report ties these operating assumptions directly to a potential 2029 financial snapshot. For the forecasts to line up with analyst models, International Paper would need to be generating around US$27.0b of revenue and US$1.8b of earnings by 2029 while trading on a P/E of 15.1x. That implies the market would be paying a multiple below the current packaging industry average if the margin rebuild and volume expectations in those models hold together.
International Paper's narrative projects about US$27.0b of revenue and US$1.8b of earnings by 2029. This set of assumptions builds in 3.7% yearly revenue growth and an earnings increase of roughly US$5.2b from current earnings of a US$3.4b loss.
Uncover why International Paper's fair value points to a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on International Paper focuses heavily on execution risk. The lowest analysts were already penciling in slower 2.7% annual revenue growth and a move from a US$2.7b loss to US$2.4b in earnings by 2029 before this latest loss. That is far more cautious than consensus, and it shows how far opinions can spread. Use this earnings report as a chance to compare those more pessimistic assumptions with your own view. Consider several viewpoints before deciding what story you find most convincing.
Explore 3 other International Paper fair value estimates, including one that suggests it could be worth just $42.30!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your International Paper research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for International Paper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate International Paper's overall financial health at a glance.
Looking For More Investment Ideas Beyond International Paper?
If International Paper's story has you rethinking how you spread risk and opportunity across your portfolio, use this earnings update as a catalyst to widen the search. The Simply Wall St Screener helps you scan the market using the same kind of fundamentals that underpin this analysis so you can line up alternatives side by side before committing fresh capital.
- If capital preservation is high on your list, start with companies that combine balance sheet strength with steady fundamentals through our 31 resilient stocks with low risk scores.
- If you are hunting for mispriced opportunities backed by solid cash flows and financial discipline, the 38 high quality undervalued stocks can surface ideas that fit a value focused approach.
- If you prefer to back less crowded situations where the story is still developing, target potential future leaders with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com