


EN
The Call Newmont Bulls Got Right
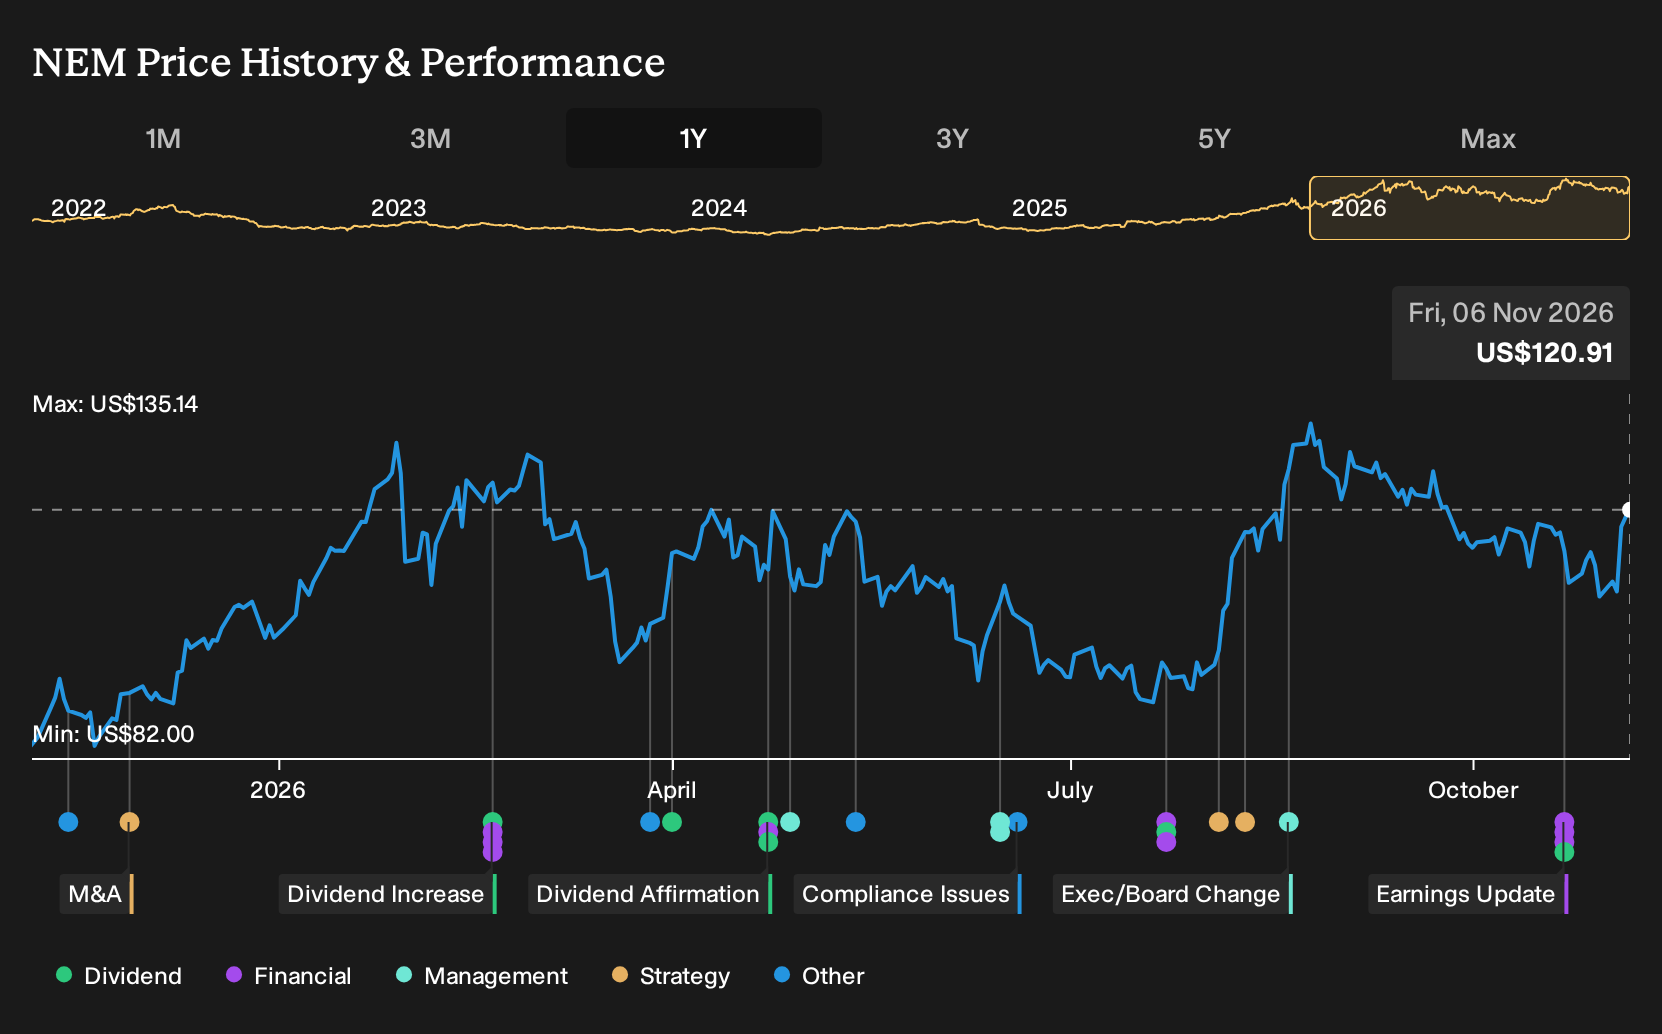
If you only glanced at Newmont’s headlines this year, the story might look messy, with record free cash flow on one side and cost pressure, downgrades, and Ghana tax changes on the other. Holding Newmont over the past year would have returned 46.4%, including dividends. If you had put money in on 6 November 2025, how much of that payoff was really visible in the early automation, ESG, and de-dollarization debates?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Newmont has already moved. Pinpoint other ways to investigate the theme among 34 elite gold producer stocks.
The Argument You Would Have Been Weighing Up On Newmont
The shares cost US$82.53 at the start of the period. Anyone looking at Newmont then had to choose between two well-argued stories rather than a single obvious takeaway.
The bullish Narrative put Fair Value at US$96.99, 18% above the start price. It leaned on assumptions that revenue could grow 8.1% a year with profit margin edging up to 30.6%, helped by automation and portfolio integration.
The bearish view pointed to Fair Value of US$51.36, 38% below the start price. That case accepted a 12.9% revenue growth assumption but focused on concentrated assets and high capital spending as key risks.
What The Results Changed For The Newmont Argument
Newmont reported Q3 2026 revenue of US$6,363m and net income of US$2,475m, with net margin at 38.9% versus 33.2% in Q3 2025. Record free cash flow in Q1 and Q2 2026 and large buybacks supported the bullish focus on strong cash generation and automation driven cost control. Rising cost guidance, Ghana tax changes, and higher capital spending at projects like Red Chris challenged the idea of friction free margin expansion. The evidence cut both ways.
The hinge assumption here was profitability quality, not just gold exposure. For any other miner, a reader can stress test similar claims by lining up revenue, net income, and net margin a year apart around the decision date, then comparing those against the promised benefits from automation, portfolio integration, or major project spending.
What Newmont's Price Already Assumes After The Run
Newmont now trades at US$121 after a 46.4% gain over the past year, and the selected Narrative’s Fair Value sits below that level. The focus has shifted toward whether strong cash generation can comfortably support a heavier, multi year project bill.
A buyer today effectively banks on Newmont turning its growth pipeline into dependable, cost controlled output, so the Narrative’s emphasis on capital intensity and energy sensitivity becomes the key tension to examine.
"The numbers imply that Newmont’s current share price already assumes successful delivery of its portfolio growth, cost control and joint venture plans despite ongoing macro headwinds and rising development intensity. While Newmont highlights a multi asset growth pipeline that is expected to support production for decades, the forecast increase of about US$500 million in development capital in 2027 together with the Red Chris block cave estimate of US$4.2 billion to US$4.8 billion on a 100% basis raises the risk that capital intensity outpaces cash generation and compresses future free cash flow and returns on invested capital."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 43% below our estimate - focuses on building a higher margin aviation aftermarket platform via acquisitions and partnerships.
- Company 2 - 47% below our estimate - uses digital lending and checking tools to deepen small business banking relationships at scale.
- Company 3 - 18% below our estimate - supplies high bandwidth memory and storage that help relieve capacity constraints in AI data centers.
That is three of the list. See every one of the 38 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com