


EN
Weyerhaeuser (WY) Beat Expectations And Expanded Clean Energy Plans, Is It Still Undervalued?
Weyerhaeuser (WY) moved after its third quarter 2026 earnings, as the forestry REIT paired better than expected results with plans to sell timberland, build a biocarbon facility, and expand solar and geothermal projects.
Weyerhaeuser’s share price has been volatile this year, with a 1 month share price return of 9.84% but a 90 day share price return that declined 17.04%, while the year to date share price return is down 11.85% as enthusiasm around its Q3 initiatives competes with weaker recent momentum. Over a longer horizon, total shareholder return has also been under pressure, with the 1 year total shareholder return down 5.79% and the 5 year total shareholder return down 30.65%. This suggests that investors are still reassessing the balance between new growth projects and perceived risk.
Capitalize on the renewed interest in Weyerhaeuser’s clean-energy and resource projects by scanning a curated set of resilient infrastructure focused plays through our 41 power grid technology and infrastructure stocks.Bulls see Weyerhaeuser’s clean energy push and asset sales as underpriced, while bears focus on choppy returns and softer earnings. Which story does the valuation actually support next?
Most Popular Narrative: 21% Undervalued
The most followed narrative for Weyerhaeuser pegs fair value at $26.64, above the last close at $20.98. This frames the stock as undervalued if those assumptions hold up.
The current valuation implies that the market is not fully pricing in the potential cash generation from Weyerhaeuser’s targeted 75 to 80% Adjusted FAD capital return framework, the higher EBITDA contribution from Strategic Land Solutions and Climate Solutions, and the expected earnings uplift from lumber supply tightening and new engineered products such as Monticello TimberStrand.
See why 28 investors see Weyerhaeuser as 21% undervalued.
Result: Fair Value of $26.64 (UNDERVALUED)
Still, a weak Oriented Strand Board segment and housing activity described as stuck in second gear could both undermine the bullish Weyerhaeuser narrative if they persist.
Find out about the key risks to this Weyerhaeuser narrative.
Another View: What Weyerhaeuser’s P/E Is Telling You
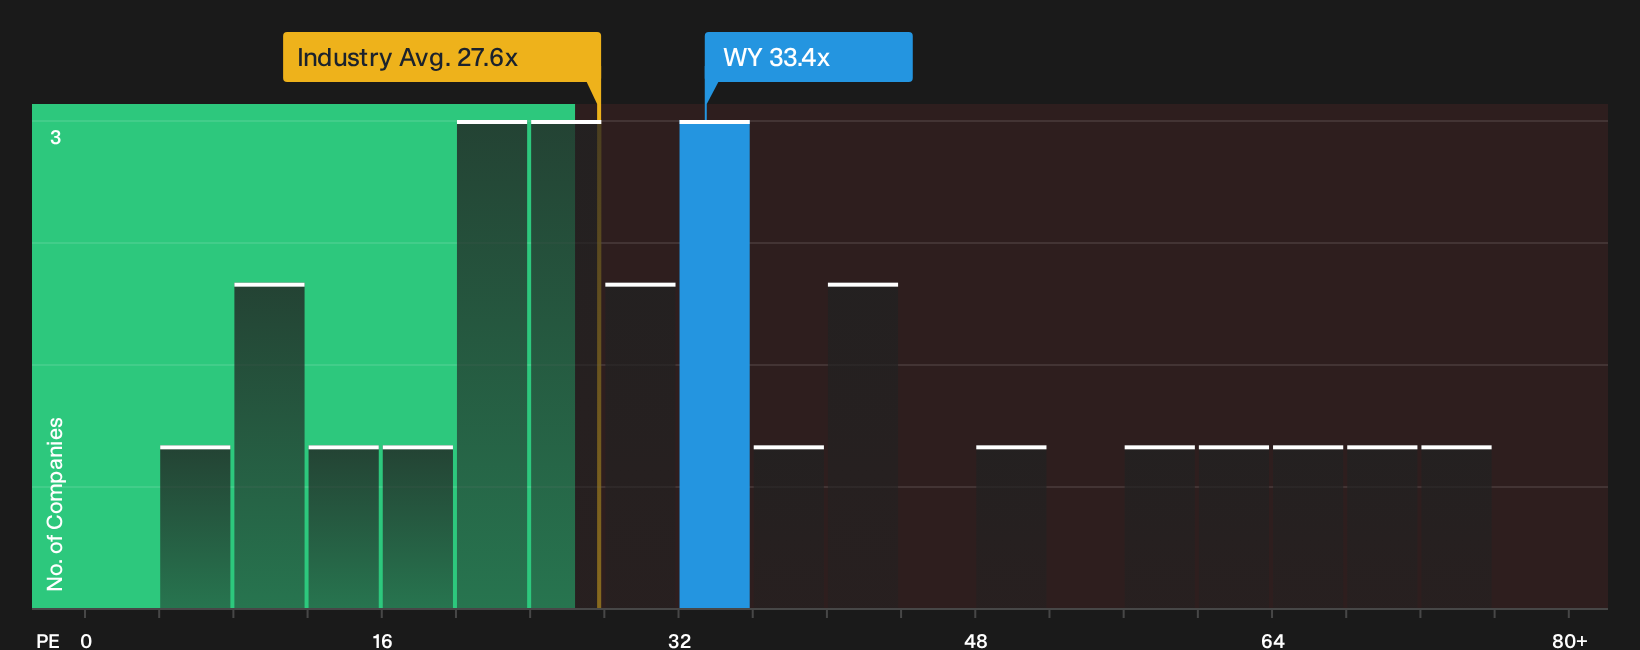
The story looks different when you shift from fair value estimates to the plain P/E ratio. Weyerhaeuser trades on 33.4x earnings, compared with 25.1x for peers and 27.6x for the wider Specialized REITs group. The stock also sits just under a fair ratio of 35.4x.
That mix points to a higher earnings multiple than sector averages, yet still a discount to where the fair ratio suggests the market could move. For anyone weighing the DCF style upside against this richer P/E, the open question is how much valuation risk feels acceptable if earnings progress stalls.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment runs through the Weyerhaeuser story right now, with both concern and optimism in play. Consider acting promptly and review the numbers yourself through 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Weyerhaeuser?
If Weyerhaeuser has sharpened your focus on where capital is working hardest, do not stop here. Broaden your opportunity set with a few targeted screens that surface clear, data driven ideas across very different styles of investing.
- Target predictable compounding by scanning companies with resilient balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricing by reviewing a curated pool of quality businesses trading below assessed value using the 38 high quality undervalued stocks.
- Explore income focused opportunities by zeroing in on higher yielding payers screened as 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com