


EN
Reformation (REF) Could Be 6% Undervalued On Q3 Earnings Swing
Q3 earnings put Reformation under a brighter spotlight
Reformation (REF) just put fresh numbers on the table, with third quarter earnings showing higher sales alongside a swing to a small loss. This gives investors new data to reassess the stock.
The Q3 release has arrived alongside a sharp shift in sentiment, with Reformation’s 1-day share price return of 7.12% and 30-day share price return of 34.70% lifting the stock to $18.05. Momentum over the year-to-date share price return of 19.70% suggests interest is building, despite the recent swing to a small loss.
Scan for other apparel and retail stocks showing similar post earnings momentum and a balance between growth and losses by reviewing the 19 high quality undiscovered gems alongside Reformation.
Reformation’s rally has arrived just as the income statement tipped back into a small loss. Is this jump a reaction to stronger sales, or simply a mood swing in the share price that valuation now needs to test?
Most Popular Narrative: 6% Undervalued
Reformation’s most followed valuation story puts fair value at $19.25, a touch above the latest $18.05 close, which keeps the stock framed as modestly discounted rather than stretched.
Reformation's sustainability focused brand and multigenerational appeal, with 70% of 2025 revenue from repeat customers and meaningful participation from shoppers under 25 and over 50, are supporting high retention metrics such as 80% 1 year and 98% 2 year revenue retention, which can stabilize revenue and support consistent EBITDA generation.
See why 1 investors see Reformation as 6% undervalued.
Result: Fair Value of $19.25 (UNDERVALUED)
Still, Reformation’s plan to more than double its store base and its heavy reliance on full price selling could strain margins if new locations underperform or if discounting rises.
Find out about the key risks to this Reformation narrative.
Another view on Reformation’s valuation
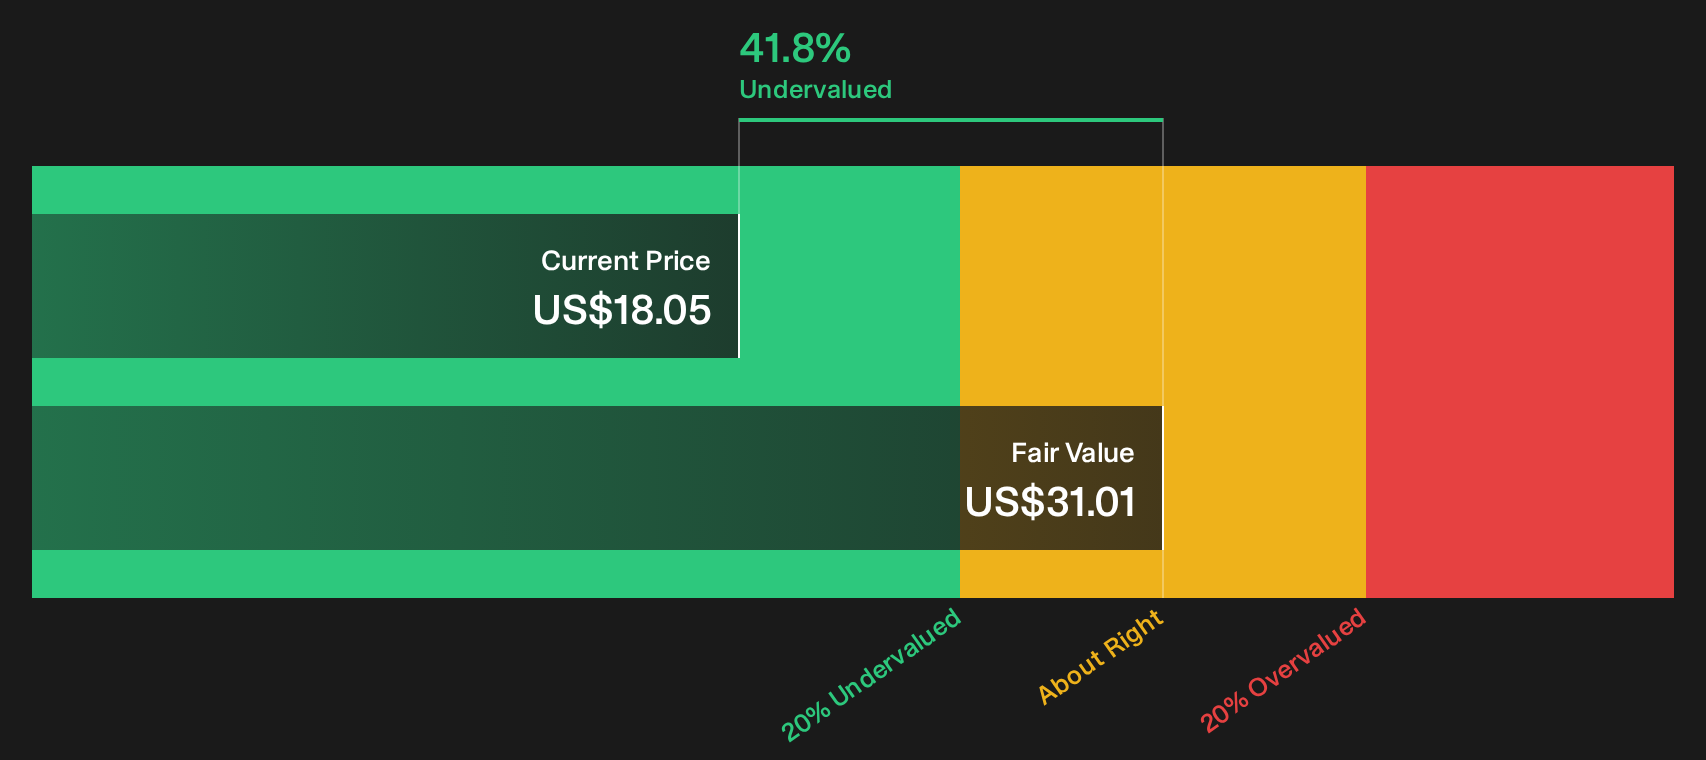
On cash flows, the story looks different. Reformation is trading at $18.05 while the SWS DCF model puts future cash flow value at $31.01, which points to the stock trading at a large discount and leans more heavily into the upside case than the $19.25 fair value narrative.
This kind of gap between price and modeled value can reflect real opportunity or simply optimistic assumptions baked into the cash flow inputs. Which side of that line do you think the stock sits on right now?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Reformation’s value story so far. If you want to move fast and decide where you stand, weigh both sides through the 3 key rewards and 2 important warning signs.
Looking for more Reformation sized investment ideas?
If Reformation has you thinking about where the next opportunity might come from, do not stop at a single ticker. Use the screeners to compare, cross check, and pressure test your ideas against a much wider field.
- Target resilient compounding potential by scanning companies with consistent payouts using the 7 dividend fortresses.
- Hunt for quality at a reduced price by filtering candidates through the 38 high quality undervalued stocks.
- Prioritize capital preservation by starting your search with the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com