


EN
What Investors Got Wrong About Autotrader Group Before The Drop
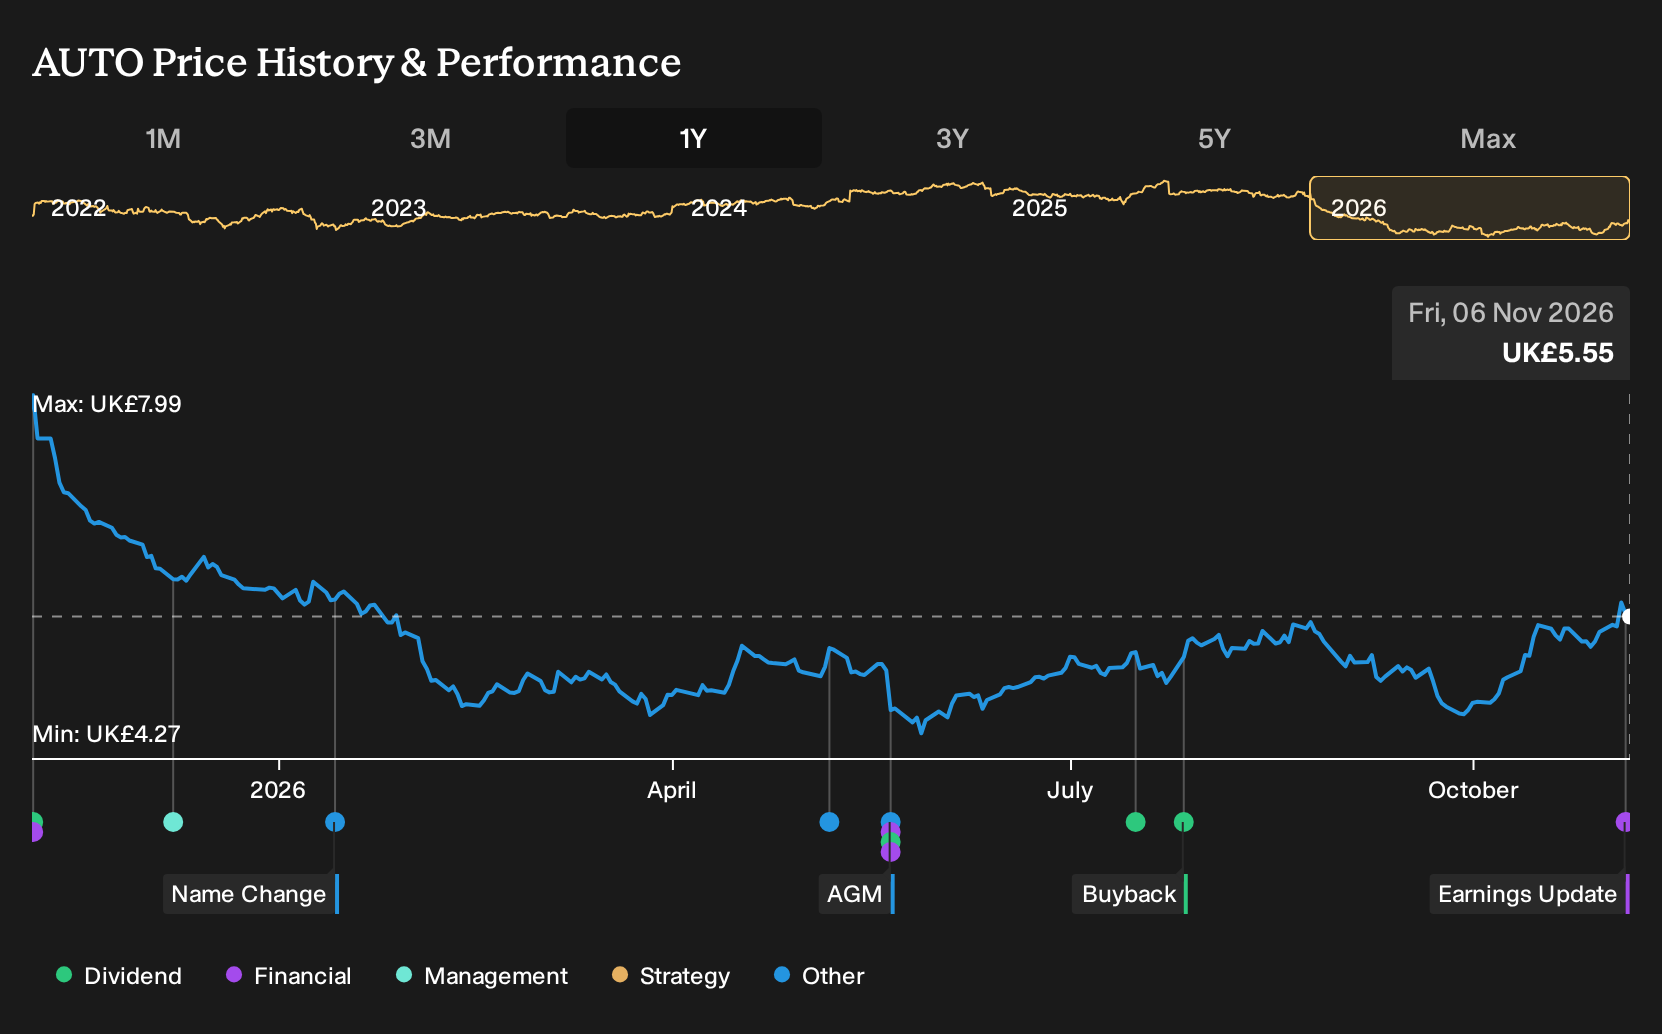
If you only glanced at headlines about Autotrader Group’s AI tools and digital retail push, the last year might have looked comfortable. Investors who held Autotrader Group over the past year are down 24.5%, including dividends. That gap between upbeat product stories and a falling share price leaves a clear puzzle. If you were deciding whether to buy at the start of that stretch, what exactly was visible in the business record that might have flagged this risk?
If the move has made Autotrader Group harder to judge, start where the gap is still open and scan 14 high quality undervalued stocks.
The Two Stories Investors Were Really Pricing In On Autotrader Group
The shares cost £7.99 at the start of the period, and Autotrader Group sat between two very different readings of the same product roadmap.
On the upbeat side, the Deal Builder and Co-Driver AI story pointed to a Fair Value of £8.53. This was a rough guide to what those assumptions implied the shares could be worth if delivered, built on expectations for 6.3% annual revenue growth and higher net margins from better customer engagement.
The cautious script put more weight on urbanisation, shared mobility and direct sales. It pointed to a Fair Value of £6.5 and a key risk that structurally lower private car ownership would shrink the long term market for used vehicle listings.
What The Results Changed For The Autotrader Group Thesis
The half year report to November 2026 showed total revenue at £313.4 million versus £317.7 million a year earlier and net income at £143.6 million versus £150.9 million. Net margin moved from 47.5% to 45.8%. That pattern challenged the upbeat Autotrader Group case that relied on higher profitability from AI tools and digital retail, so the evidence cut both ways.
The key lesson is simple. When a story leans on richer margins, keep checking the reported net margin against the pitch, then decide how much of that gap you are willing to pay for.
What You Would Be Paying For In Autotrader Group Today
With Autotrader Group now at £5.55, the selected Narrative’s Fair Value sits above the current price and leans on AI products, richer data and capital returns to explain that gap.
The crux for you is whether Deal Builder and Co-Driver really become the default UK used car journey while retailer engagement and cash generation hold up.
"The shift to Deal Builder as the default used car buying journey, with a target of full retailer penetration in FY27, opens room for Auto Trader to earn incremental fees around finance, reservations and value added services attached to each digital transaction. This would move a greater share of the used car profit pool into high margin marketplace revenue."
One Narrative disagrees with today's price. → See where this Narrative says Autotrader Group should trade
Looking One Step Beyond Autotrader
Autotrader Group is leaning hard into AI tools and richer data. You could also look at where that AI demand is processed.
Search queries, video viewing and online retail journeys all create heavy computing workloads. Those workloads need somewhere to run complex models and store information.
Another large platform sells that capacity, packaging AI tooling with cloud infrastructure. Its services help enterprises train models, analyse data and plug smart features into everyday software.
If Autotrader’s vision involves more digital journeys, this other player also serves that broader shift. The unresolved question is how much AI work ultimately runs through its environment.
One Narrative has already put a figure on it. → Uncover the company trading 34% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com