


EN
What MTN Group Doubters Missed
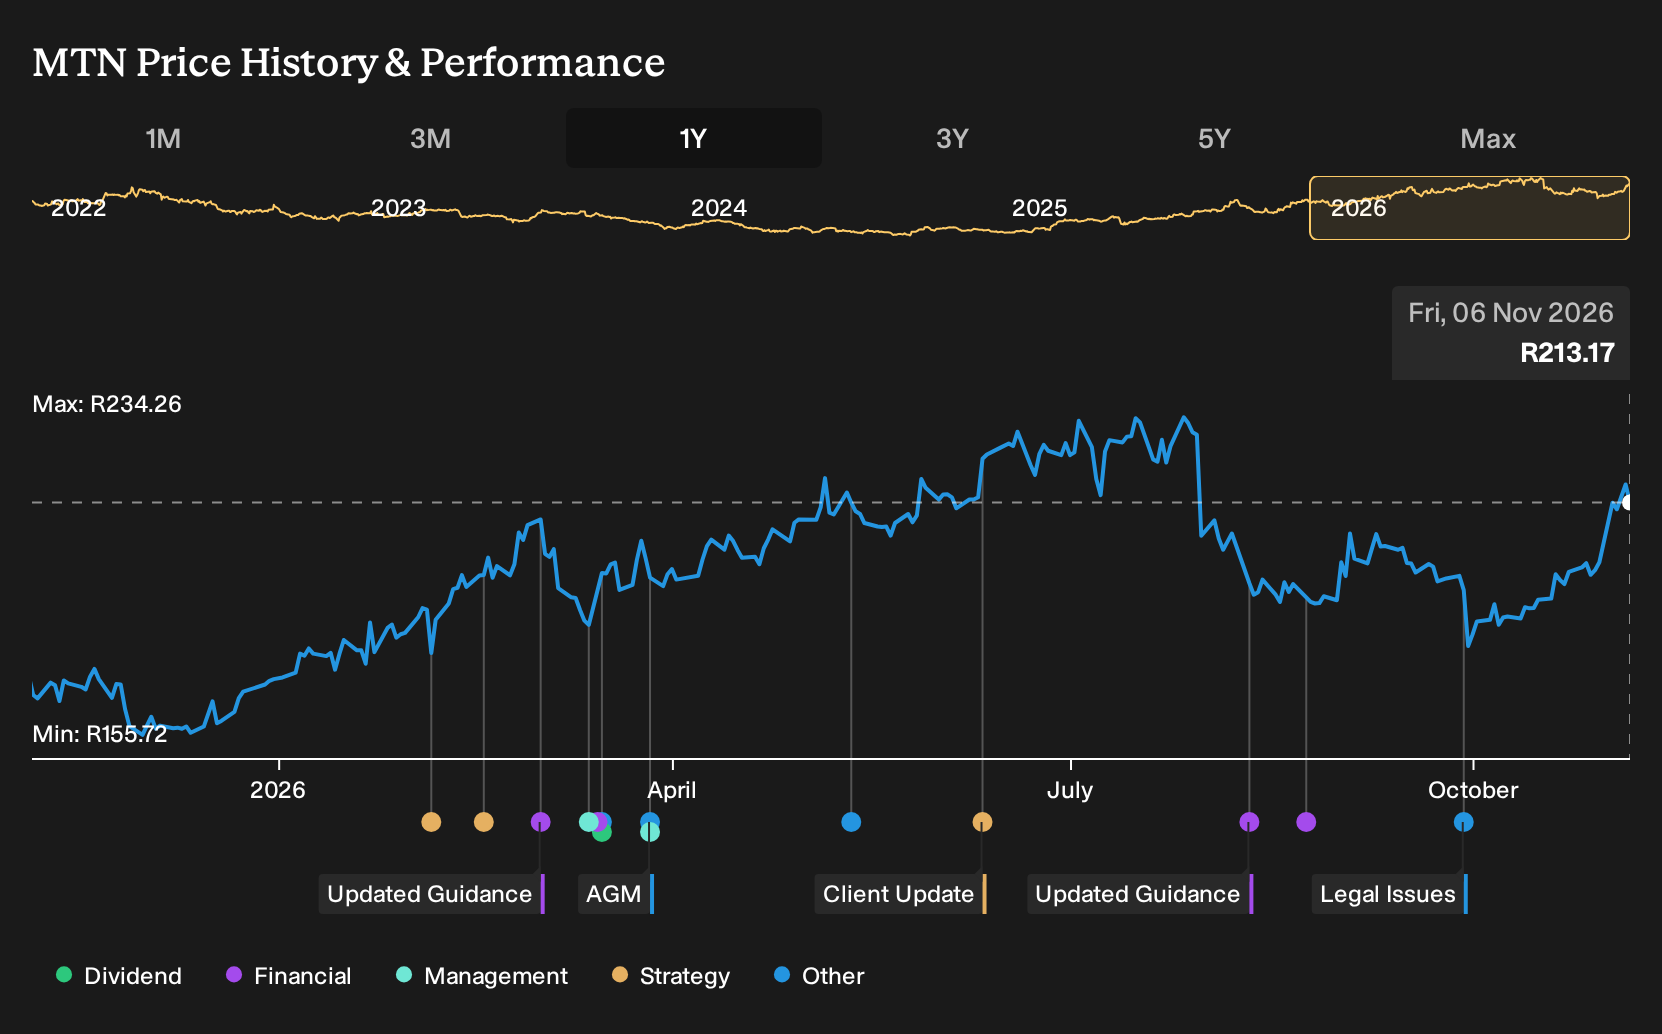
If MTN Group sat on a watchlist instead of inside a portfolio, the outcome over the last year may feel like a missed chance. Holding MTN Group over the past year would have returned 32.8%, including dividends. That result looks even more interesting given that bullish analysts were arguing in mid 2025 that mobile internet and fintech could reshape earnings power. If data and digital finance were expected to drive margins higher, what early evidence could have signalled that conviction was worth trusting?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind MTN Group. Zero in on 222 high quality undervalued stocks for companies trading below our estimates.
What MTN Group Investors Were Really Arguing About
The shares cost ZAR166 at the start of the period, and anyone interested in MTN Group had to decide which story felt more convincing.
The bullish thesis pointed to a Fair Value of ZAR220. It rested on mobile internet and fintech reshaping the revenue mix, with assumptions that advanced fintech services could become a dominant earnings driver as they scaled across MTN's large user base.
The bearish view put Fair Value at ZAR73. That camp focused on risks like Starlink and other satellite providers potentially chipping away at MTN Group's subscribers, especially in rural areas, and leaving parts of its network economically stranded.
What The MTN Group Results Put To The Test
The key fresh fact for MTN Group holders was the H1 2026 report. Revenue reached ZAR118.9b compared with ZAR109.3b a year earlier, which leaned toward the bullish data and fintech story. Net income moved to ZAR7.4b from ZAR9.9b and net margin slipped from 9.0% to 6.2%, so profitability challenged the most optimistic earnings claims. Overall, the evidence cut both ways.
The main lesson is simple. When a bullish story leans on margin expansion, you need to track net margin first, then revenue, and see if both move in the same direction over time.
What MTN Group's Current Price Already Assumes
MTN Group now trades at ZAR213, up 33% over the past year, while this Narrative’s Fair Value sits below the current price based on its own assumptions.
The Narrative leans on strong data and fintech usage but questions whether cash generation can comfortably cover higher energy, tower and regulatory pressures. A buyer today needs to judge whether MTN Group can consistently turn that usage into equity free cash flow despite those headwinds.
"The main thing that has to go right is that MTN Group converts strong data and fintech usage trends, supported by disciplined CapEx and low leverage, into sustained equity free cash flow while managing regulatory and macro shocks across its markets."
One Narrative disagrees with today's price. → See where this Narrative says MTN Group should trade
Looking Past MTN Group's Towers
MTN Group keeps your focus on ground networks and spectrum auctions. Step aside briefly and something very different appears in orbit.
Instead of extra base stations, this other business launches rockets and runs a satellite web. The same mobile users MTN targets still worry about gaps and outages.
To meet that need, it is planning direct satellite links for ordinary phones. It is also using low band signals for better indoor reach.
Above that sits growing attention on AI computing gear and custom chips. If that stack works, your idea of connectivity infrastructure could shift away from MTN's world.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 54% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com