


EN
Should Earnings Upgrade Require Action From Kimco Realty (KIM) Investors?
- Kimco Realty reported Q3 2026 results with revenue of US$546.15 million and net income of US$279.07 million, raised full year earnings guidance, increased its common dividend by 7.7%, advanced its share repurchase program, and expanded in Louisville through a US$295 million acquisition of two grocery anchored centers.
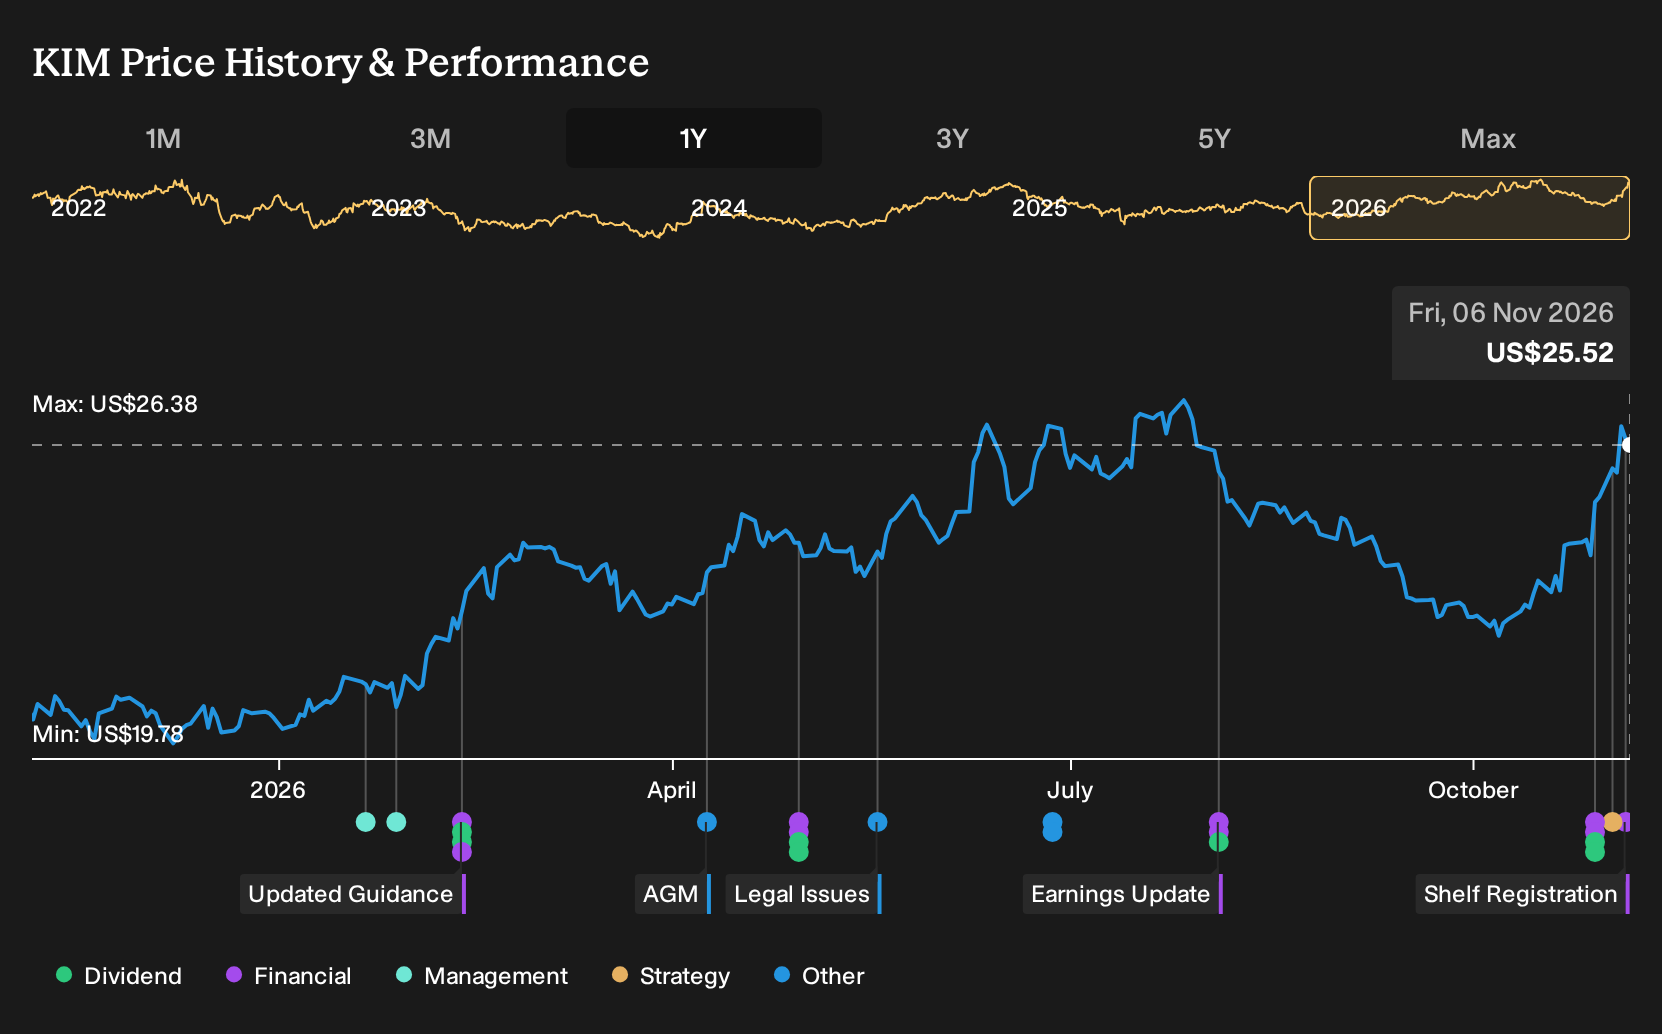
- The new US$652.31 million common equity shelf filed in early November gives Kimco Realty extra flexibility to fund further open air retail investments. The company is keeping leverage in focus after recycling capital from lower yielding assets into higher returning grocery anchored centers.
- Next, the focus will be on how Kimco Realty's investment narrative is affected by this earnings upgrade and dividend increase.
Scan how Kimco Realty's move toward grocery anchored, open air centers compares with other potential opportunities by reviewing a curated list of solid balance sheet and fundamentals (25 results) in the same space.
Kimco Realty Investment Narrative Recap
To stay invested in Kimco Realty, you need to be comfortable with a REIT leaning hard into grocery anchored, open air centers with high tenant demand and relatively tight supply. The recent earnings beat, dividend increase and Louisville acquisitions all point to that focus staying intact, with more of the rent roll tied to necessity driven traffic.
The near term swing factor is execution on leasing and remerchandising those new properties while keeping interest costs in check as 2026 debt rolls. The biggest risk remains higher refinancing costs and any legal overhang from tenant disputes, which could pressure margins even if occupancy and rents hold up.
The most relevant recent move for that thesis is the US$652.31 million common equity shelf filed in early November. It gives Kimco Realty flexibility to raise capital for more grocery anchored centers or redevelopment work without relying only on debt. This could matter if refinancing costs stay elevated versus the 2.6% coupon on 2026 maturities.
For you as an investor, that shelf sits alongside the buyback and dividend increase as a reminder that capital allocation cuts both ways. Fresh equity could support growth and keep leverage stable, yet it can also dilute per share metrics if deployed into projects that do not meet the higher return hurdles management has outlined.
Kimco Realty's consensus narrative points to revenues of US$2.4b and earnings of US$643.9 million by 2029. This assumes revenue grows at 3.3% per year and earnings rise by about US$70 million from the current US$573.8 million level.
Discover why Kimco Realty's fair value suggests a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Kimco Realty from 2 private investors in the Simply Wall St Community span a tight band, from about US$26.18 to US$33.95 per share. You are weighing those views against fresh catalysts like the Louisville expansion and the US$652.31m equity shelf, which can shift perceptions of risk and opportunity.
Explore another Kimco Realty fair value estimate, including one that suggests it could be worth just $26.18.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kimco Realty research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Kimco Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kimco Realty's overall financial health at a glance.
Looking for more investment ideas beyond Kimco Realty?
Once you have a view on Kimco Realty, it can help to compare that thesis with a few other businesses that share similar quality filters, income profiles, or risk characteristics. The Simply Wall St Screener gives you a structured way to do that side by side instead of chasing headlines one at a time.
- If you want potential upside combined with balance sheet strength, scan a curated 19 high quality undiscovered gems that meet strict fundamental checks and may not yet be widely followed.
- For investors who care most about resilience and capital protection, review a focused 31 resilient stocks with low risk scores that emphasizes lower risk scores across debt, earnings stability, and volatility.
- If dependable income is a priority, line up Kimco Realty against a hand picked 7 dividend fortresses that target yields above 5% with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com