


EN
Is Digital Realty Trust (DLR) Undervalued Following Its NextDC Stake And AI Expansion?
Digital Realty Trust (DLR) is in focus after expanding its AI focused Innovation Lab network into Latin America and taking an equity stake in Australian data center operator NextDC, moves aimed at AI ready infrastructure.
The recent AI focused expansion has landed against a softer tape, with Digital Realty Trust’s share price slipping 3.6% over the past week and 8.9% over the last 90 days, even as the year to date share price return is 12.4% and the 3 year total shareholder return is 48.1%. This mix suggests that long term momentum remains intact while shorter term sentiment has cooled as investors weigh new projects, revised 2026 earnings guidance and ongoing M&A ambitions.
Scan other AI infrastructure plays that echo Digital Realty Trust’s recent moves by reviewing the hand picked 53 AI infrastructure stocks in the same theme.
Digital Realty Trust now trades at a clear gap to both analyst targets and implied intrinsic value estimates. After the AI push and guidance reset, where does a fair price really land within that spread?
Most Popular Narrative: 22% Undervalued
On the most followed view, Digital Realty Trust’s fair value of $223.59 sits well above the last close at $174.20, which puts the current pullback in a different light and makes the underlying growth drivers more important than the short term price action.
The expanded 1.4 GW development pipeline at an expected 11.5% stabilized yield, alongside 600 MW of secured utility power from 2028 and potential for 2 GW near Kansas City, positions Digital Realty to bring additional capacity on line that could support higher revenue and cash NOI once these projects are completed and leased.
Record cash re leasing spreads above 25%, together with embedded upside as older hyperscale leases around US$140 per kW roll toward current market levels of US$160 to US$220 per kW, provide a pricing tailwind that can support revenue growth and net margin expansion as more contracts renew.
See why 71 investors see Digital Realty Trust as 22% undervalued.
Result: Fair Value of $223.59 (UNDERVALUED)
Still, the Digital Realty Trust story can break if the 1.4 GW build and US$4.25b to US$4.75b 2026 CapEx encounter softer demand or tougher funding conditions.
Find out about the key risks to this Digital Realty Trust narrative.
Another View: Expensive Multiples For Digital Realty Trust
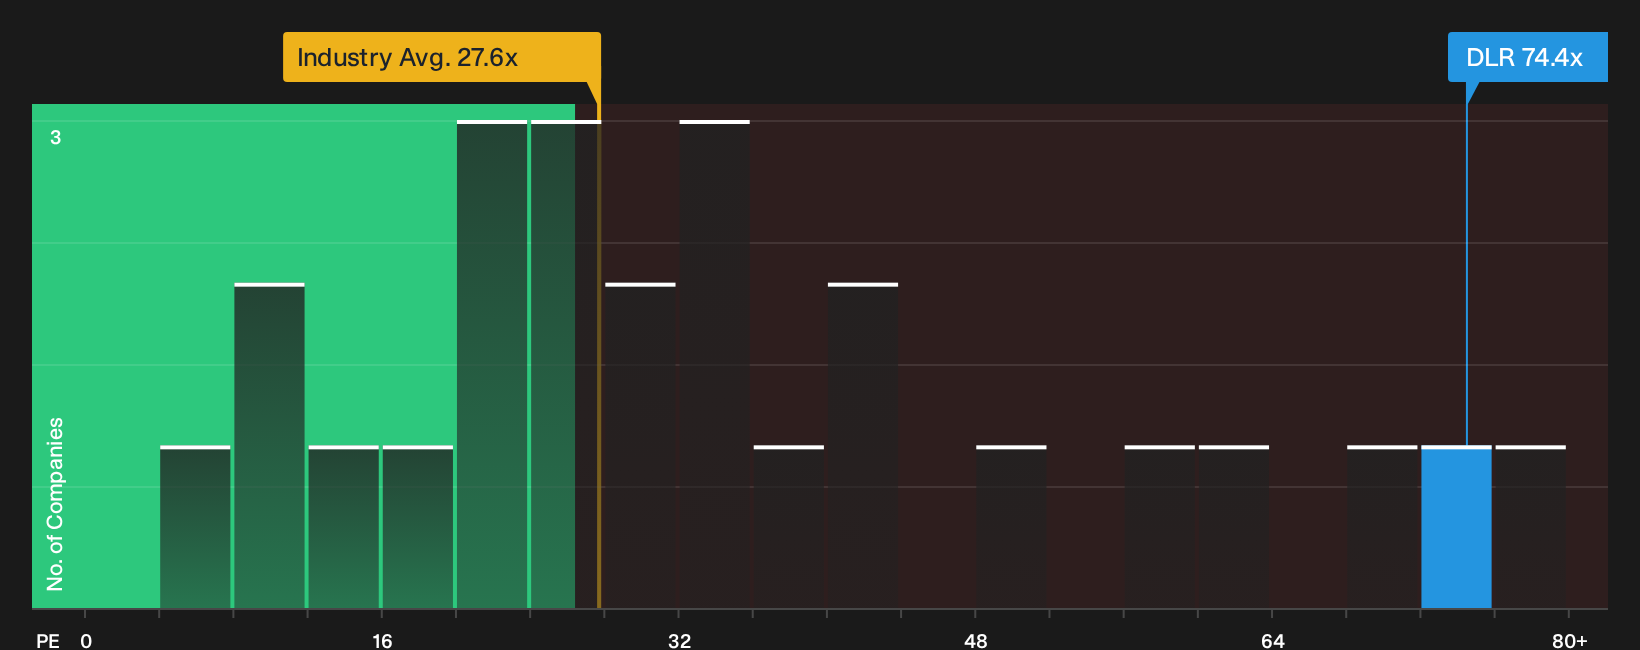
The fair value narrative paints Digital Realty Trust as undervalued, yet the market’s plain P/E math tells a tougher story. At 74.4x earnings, the stock trades well above the specialized REIT industry on 27.6x, its peer group on 48.4x and a fair ratio of 39.9x.
That gap points to valuation risk if expectations cool or earnings do not progress as analysts model. It also raises a simple question for investors weighing the AI and backlog story against today’s price tag: Which signal feels more compelling to you, the discounted cash flow work or the rich earnings multiple? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Digital Realty Trust is split, with clear risks and appealing upside both on the table. Act while the data is fresh and test the thesis for yourself by weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Digital Realty Trust?
Do not stop with Digital Realty Trust. Broaden your watchlist now, because the next opportunity you regret missing rarely shows up where everyone is already looking.
- Target resilient potential by scanning a 31 resilient stocks with low risk scores that aims to balance opportunity with lower volatility.
- Hunt for pricing mismatches using a 38 high quality undervalued stocks that focuses on strong fundamentals paired with compressed valuations.
- Zero in on quality with a list of solid balance sheet and fundamentals (25 results) that filters for sturdier finances backing each ticker.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com