


EN
Digital Turbine Stock Has a New CFO as AI Tool Adoption Builds
- Digital Turbine appointed Daniel Lentz as Chief Financial Officer and principal financial officer on 2 November 2026, while Joshua Kinsell returned to his prior focus as Chief Accounting Officer and principal accounting officer.
- The new CFO brings a mix of investor relations, finance, and operating experience from Commerce.com, Dell, RetailMeNot, and Procter & Gamble. This background aligns with Digital Turbine’s current focus on execution, cash generation, and capital allocation as it grows revenue but continues to report losses.
- We will now look at how Digital Turbine's refreshed CFO leadership could reshape the existing investment narrative around AI driven monetization.
Digital Turbine Investment Narrative Recap
To own Digital Turbine, you need to believe its AI driven ad tools and on device reach can eventually turn solid top line progress into consistent earnings and cash generation. In the near term, the key swing factor remains execution in On Device Solutions and the App Growth Platform while the firm remains loss making and works through delayed financial reporting.
The biggest risk right now sits around accounting clarity and investor trust. The appointment of Daniel Lentz as CFO may help tighten financial discipline and communication, although the leadership change by itself does not materially alter the key operational catalyst or the core risk around data quality and share price volatility.
The fresh CFO appointment matters most when set against the postponed fiscal 2027 Q2 earnings release and the pending non cash retained earnings adjustment. Investors are effectively judging Digital Turbine on two axes at once: the growth potential from DTiQ, IgniteGraph and SingleTap, and the reliability of the numbers that describe that growth.
If Lentz can sharpen forecasting, cash tracking and disclosure, it may make it easier for the market to focus on business drivers such as mobile ad demand, international device partnerships and AI monetization efficiency. Any progress here would sit directly alongside the main catalyst, better monetization of the existing platform, while also addressing the credibility risk that has weighed on sentiment.
Digital Turbine's current analyst narrative is based on projected revenues of US$862.6 million and earnings of US$106.5 million by 2029. This framework assumes revenue grows at about 12.8% a year and that earnings improve by roughly US$141.5 million from a loss of US$35.0 million today.
Uncover why Digital Turbine's fair value indicates a 64% potential upside to its current price, which could narrow quickly.
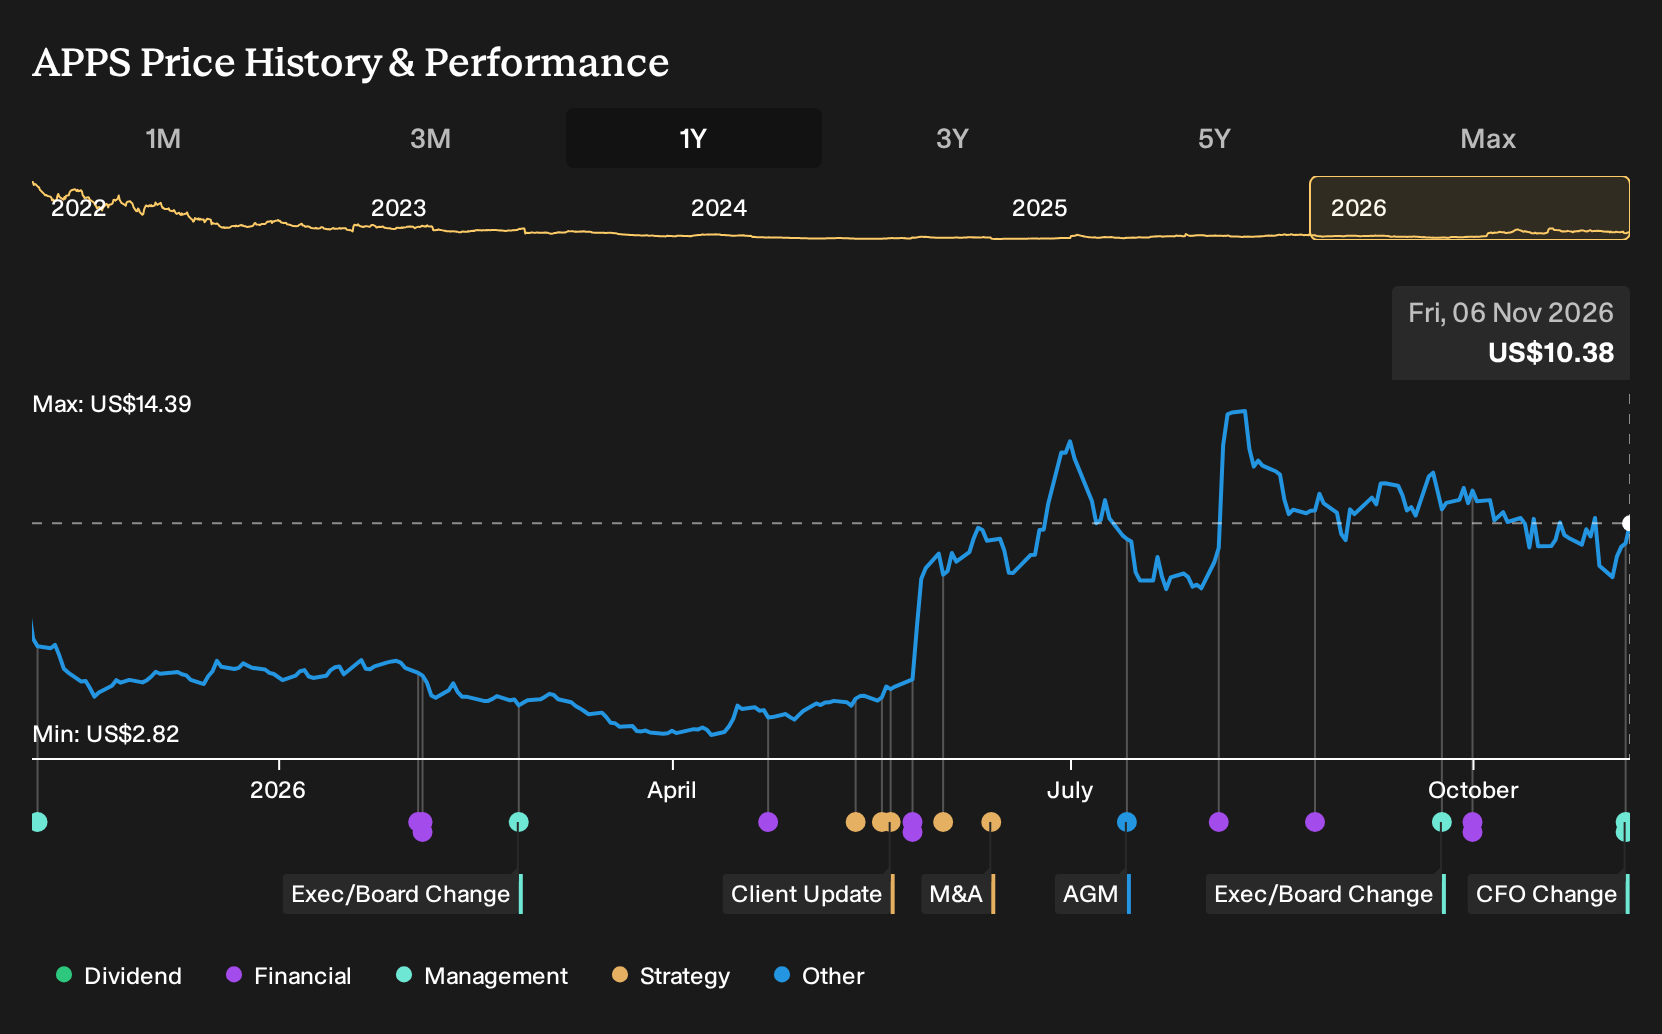
Exploring Other Perspectives
Some of the most optimistic analysts frame the Orange rollout as the real swing factor for Digital Turbine, not just the new CFO. Before this leadership change, the bullish camp was already modeling about US$902.6 million of revenue and US$131.5 million of earnings by 2029. Views differ widely, so treat this CFO move as a fresh reason to compare several competing narratives rather than anchor on just one.
Explore 4 other Digital Turbine fair value estimates, including one that suggests as much as 134% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Digital Turbine research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Digital Turbine. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Digital Turbine's overall financial health at a glance.
Looking For More Investment Ideas Beyond Digital Turbine?
Digital Turbine may be central to your thesis on AI driven monetization, but your portfolio benefits when you weigh it against a broader set of opportunities. The Simply Wall St Screener can help you quickly filter for different styles of stocks that might complement or contrast with your view on this business.
- If capital protection sits high on your list, start with a filter focused on resilience and see which companies appear in our 31 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, compare Digital Turbine to a curated 38 high quality undervalued stocks that pass both cash flow and balance sheet checks.
- Income focused readers can scan for payouts that matter, using a targeted list of 7 dividend fortresses that aim to combine higher yields with sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com