


EN
Should Weaker Earnings Require Action From Builders FirstSource (BLDR) Investors?
- Builders FirstSource reported third quarter 2026 sales of US$3,854.05 million and net income of US$60.41 million, both below the prior year, and guided full year 2026 net sales to a range of US$14.2b to US$14.6b, while executing no share repurchases under the April 30, 2026 buyback during the latest quarter.
- The sharp gap between year to date net income of US$9.1 million and the prior year’s US$403.72 million highlights how current housing demand, pricing mix and cost structure are pressuring Builders FirstSource’s earnings power, even as management continues to frame the full year outlook in terms of multi billion dollar revenue.
- We will now look at how Builders FirstSource’s weaker third quarter profitability and new 2026 sales guidance could reshape its investment narrative.
Builders FirstSource Investment Narrative Recap
To stay invested in Builders FirstSource, you need to believe the business can work through weaker housing activity while its mix shift to higher margin products, digital tools and offsite manufacturing eventually shows up more clearly in earnings. The third quarter figures and tiny year to date net income keep that belief under pressure, because profitability is thin while interest costs and housing cyclicality remain key constraints.
The most important near term catalyst remains execution on cost reductions and integration of higher value services, so that any eventual lift in demand drops through to the bottom line. The biggest risk is that softer single and multifamily starts, together with pricing and mix pressure toward smaller homes, keep revenue and free cash flow subdued for longer than investors expect.
The clearest new datapoint for that debate is Builders FirstSource setting 2026 net sales guidance at US$14.2b to US$14.6b. Management is effectively telling you to frame expectations around a mid teens billion revenue base while margins reset lower. That anchors the discussion on earnings quality rather than sheer scale and puts more weight on whether cost savings and mix shifts can rebuild profitability on that level of activity.
Pair that with the third quarter report to get a sharper picture of execution risk and timing. Net income for the quarter of US$60.41 million and US$9.1 million for the nine months against prior year levels show how far earnings have compressed even on multi billion sales. For catalysts to matter, such as digital tools, offsite components and M&A integration, investors will likely watch for any sign that future quarters convert this sales base into materially better margins without relying on more aggressive financial engineering or buybacks, which the latest zero dollar repurchase update underlines.
Builders FirstSource's current analyst narrative points to revenues of US$15.6b and earnings of US$444.2 million by 2029, based on an assumed 2.5% yearly revenue growth rate and an earnings increase of about US$341.7 million from US$102.5 million today.
Uncover why Builders FirstSource's fair value indicates an 8% potential upside to its current price before the discount narrows.
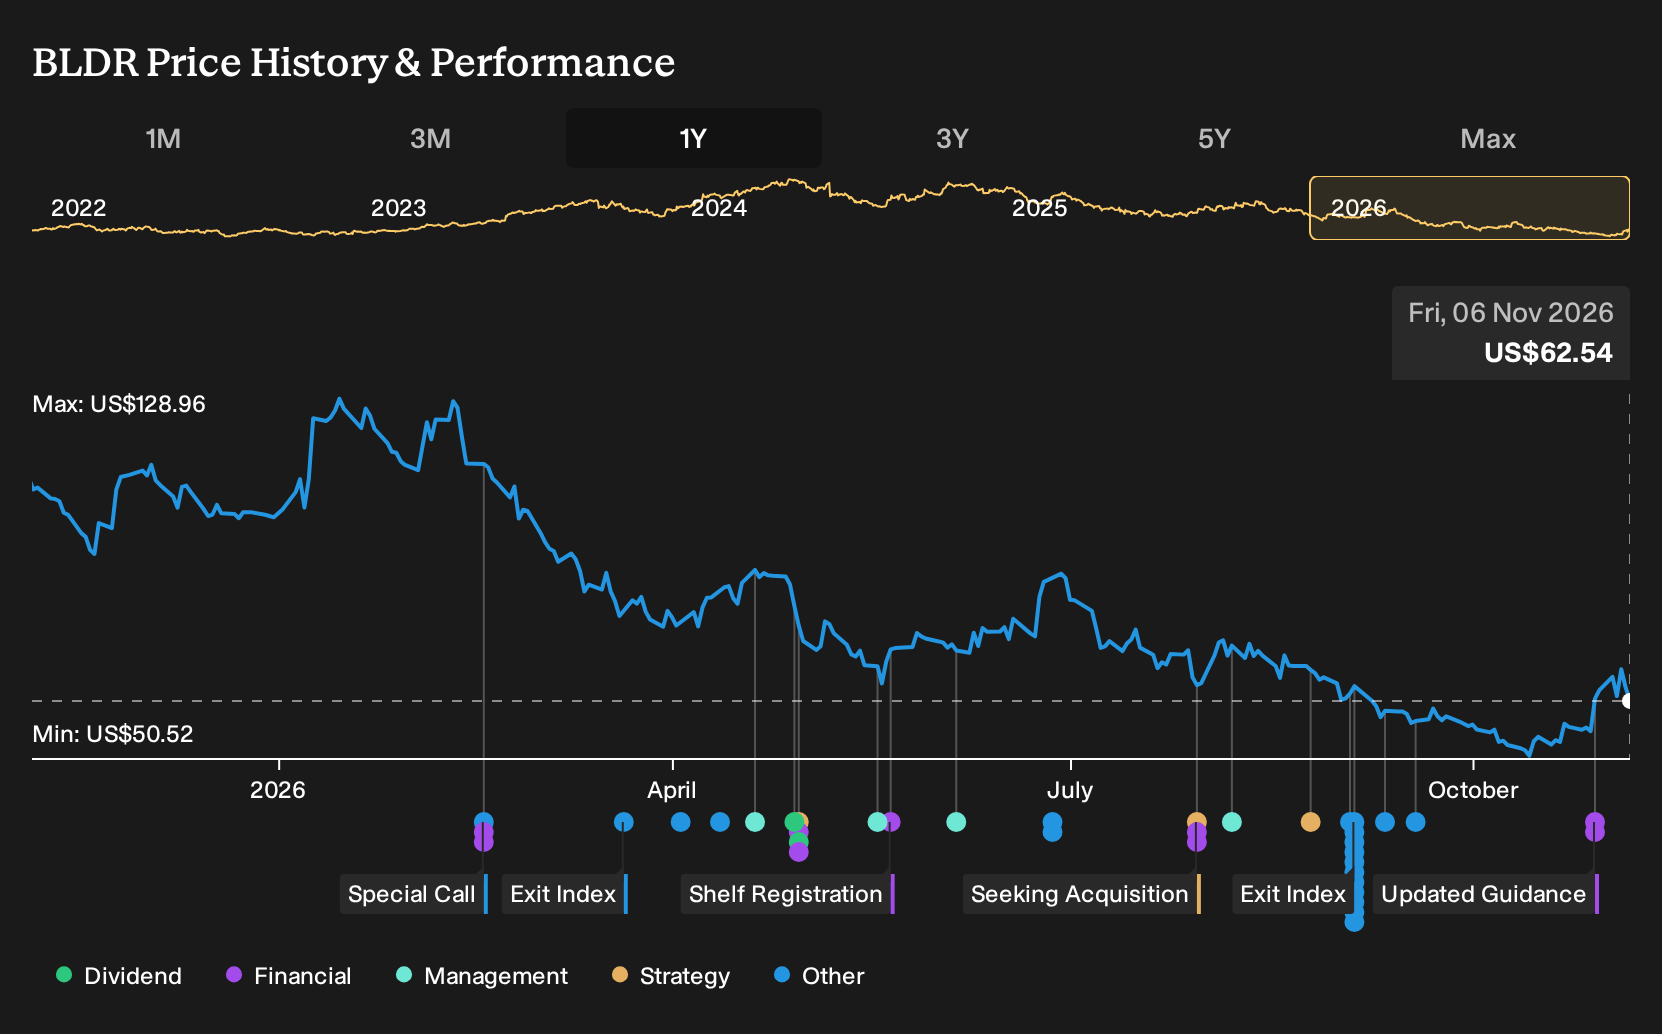
Exploring Other Perspectives
One bullish twist on Builders FirstSource focuses on cost savings rather than housing demand. The most optimistic analysts were penciling in US$15.8b of revenue and about US$797.1 million of earnings by 2029, supported by up to US$140 million of annual cost cuts. After this weaker quarter and cautious 2026 guidance, those pre news assumptions may shift, so treat them as one of several competing viewpoints to compare with your own expectations.
Explore 2 other Builders FirstSource fair value estimates, including one that suggests as much as 161% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own analysis.
- A great starting point for your Builders FirstSource research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Builders FirstSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Builders FirstSource's overall financial health at a glance.
Looking for more investment ideas beyond Builders FirstSource?
If the Builders FirstSource story has raised more questions than answers for you, it can help to widen the lens and compare it with other businesses that match the risk, quality, or income profile you prefer. The Simply Wall St Screener lets you scan the market quickly using fundamentals, so you can line up Builders FirstSource against a broader set of opportunities.
- If capital preservation sits high on your priority list, you may want to focus on companies with steadier fundamentals and review a 31 resilient stocks with low risk scores that can complement higher volatility holdings.
- For investors who emphasize underlying financial strength, it can be useful to compare Builders FirstSource to companies on a list of solid balance sheet and fundamentals (25 results) that may be better positioned to withstand tougher conditions.
- Those hunting for potential mispriced opportunities can concentrate on businesses where quality and valuation intersect by scanning a 19 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com