


EN
How Aerospace Spin Off Will Impact Honeywell Stock Investors
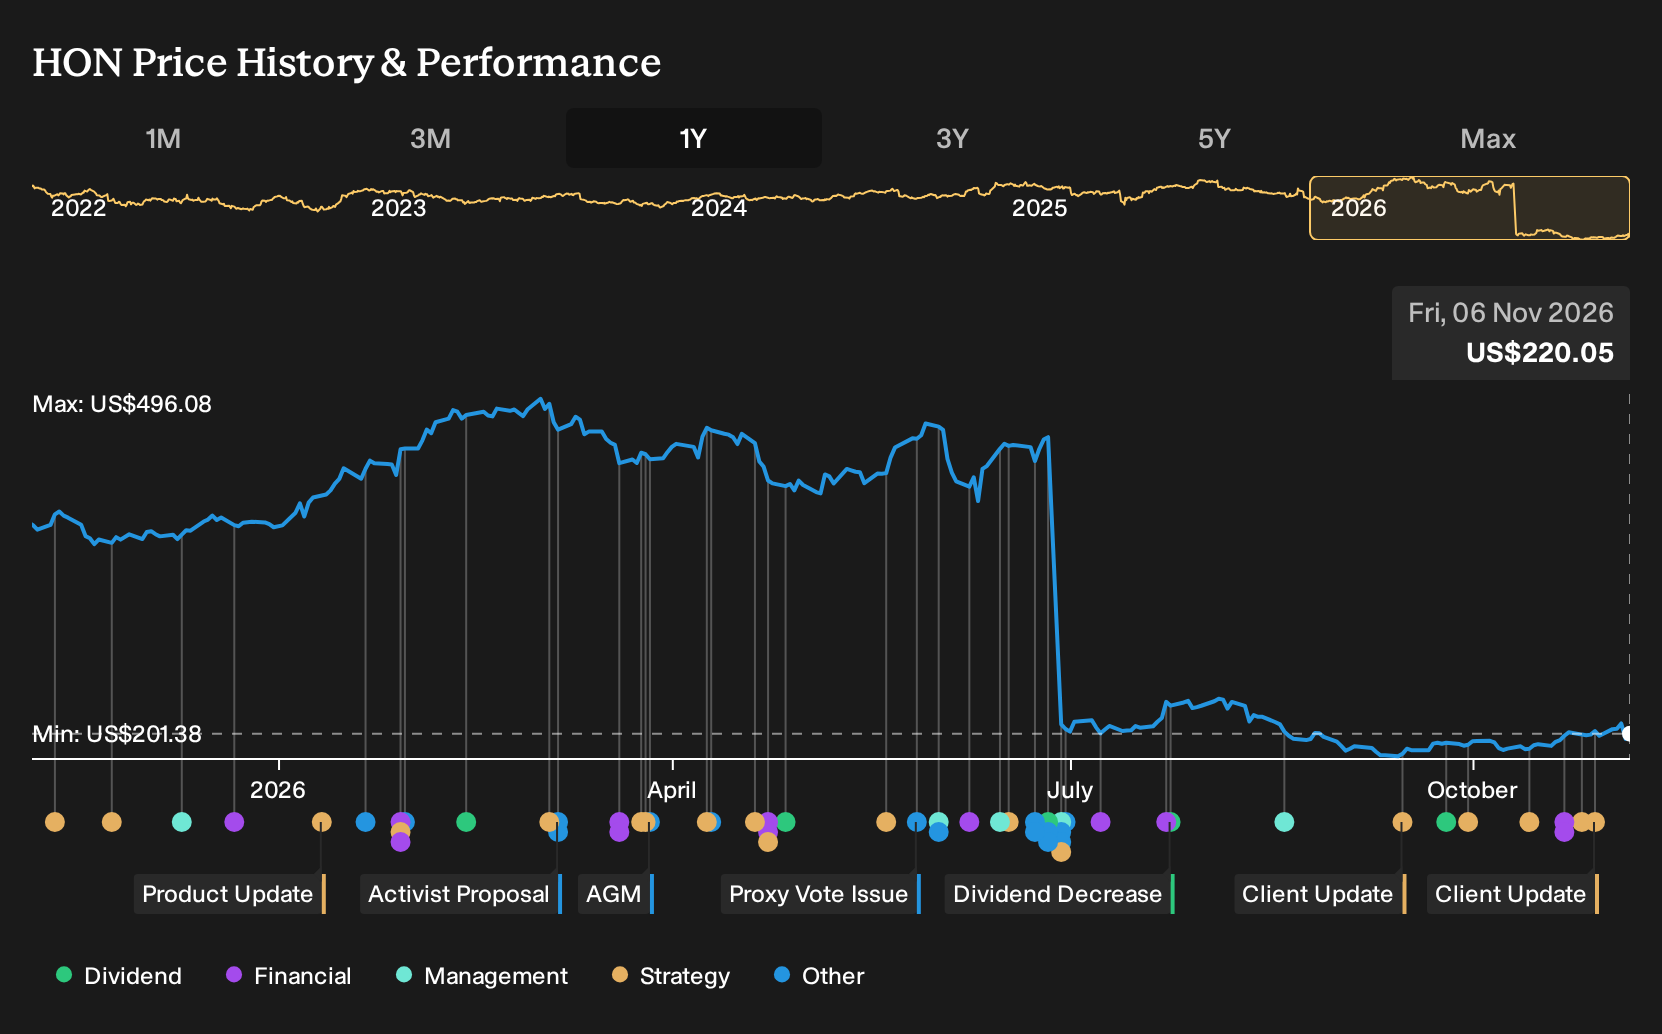
- Honeywell International has completed the spin-off of Honeywell Aerospace, introduced a smaller combined dividend, and highlighted a focus on paying down separation related debt while preserving financial flexibility.
- The shift toward debt reduction and a leaner dividend structure indicates that management is prioritizing balance sheet strength over immediate cash returns to shareholders after the Aerospace separation.
- This article examines how Honeywell International's post spin dividend reset and debt focus may reshape the broader investment narrative for investors.
Honeywell International Investment Narrative Recap
To own Honeywell International today, you need to believe in a tighter, automation-first group that can turn software, AI and energy transition projects into steadier cash generation while digesting the aerospace spin. The near term catalyst is clean execution on the new structure and debt reduction. The recent connected cabin and Forge Cognition updates mainly reinforce that operational story rather than alter it.
The biggest risk still sits in execution. Separation costs, a high bar on margin targets and analyst expectations for declining revenue and earnings create little room for slip ups. Weak macro demand across buildings, industrial and process customers would make that margin and cash flow puzzle harder.
The Forge Plant Cognition launch is the clearest link between the current news and Honeywell International’s broader thesis. It shows the firm putting its Forge Cognition AI platform to work in heavy assets like the Dangote refinery, tying process technology and software into one operational stack. That is exactly where management has been pointing investors, toward LNG, refining and higher value automation.
For you as a shareholder, the interest is practical. Successful delivery at a large complex site supports the idea that Honeywell International can use AI agents, digital twins and UOP expertise to address bottlenecks, uptime and workforce productivity. The risk is that these projects are complex, and any delays, customer pushback or muted adoption would weigh on the high growth verticals and software mix the thesis leans on.
Honeywell International's outlook projects US$22.3b in revenue and US$3.2b in earnings by 2029. This reflects analysts expecting revenue to decline by 16.4% per year and an earnings decrease of US$5.1b from US$8.3b today.
Uncover how Honeywell International's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative lens focuses on Honeywell International’s premium valuation assumptions rather than execution risk. Bullish analysts were previously willing to underwrite a P/E of 40.5x on 2029 earnings of US$2.9b, even with revenue projected around US$20.2b. You might see the Royal Caribbean and Forge updates and wonder if those already stretched expectations now look conservative or too optimistic. The key point is that opinions differ widely, so it can help to compare several narratives before deciding how this fresh automation news might shift your own view.
Explore 8 other Honeywell International fair value estimates, including one that suggests there could be as much as 46% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Honeywell International research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Honeywell International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Honeywell International's overall financial health at a glance.
Looking For More Ideas Beyond Honeywell International?
If Honeywell International has sharpened your interest in automation, industrial software and cash generative business models, you can widen your watchlist by scanning other companies with similar strengths through the Simply Wall St Screener.
- For investors hunting for quality at a discount, scan for companies that currently screen as 36 high quality undervalued stocks that may offer more for every dollar of earnings or cash flow.
- If resilience matters most to you, focus on balance sheets that look robust and funding that appears secure by reviewing the list of solid balance sheet and fundamentals (25 results).
- Income focused readers who want cash returns up front can narrow the field to companies with higher yields and sturdier payouts through a curated set of 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com