


EN
How Investors Are Reacting To PENN Entertainment (PENN) Raised Retail Guidance
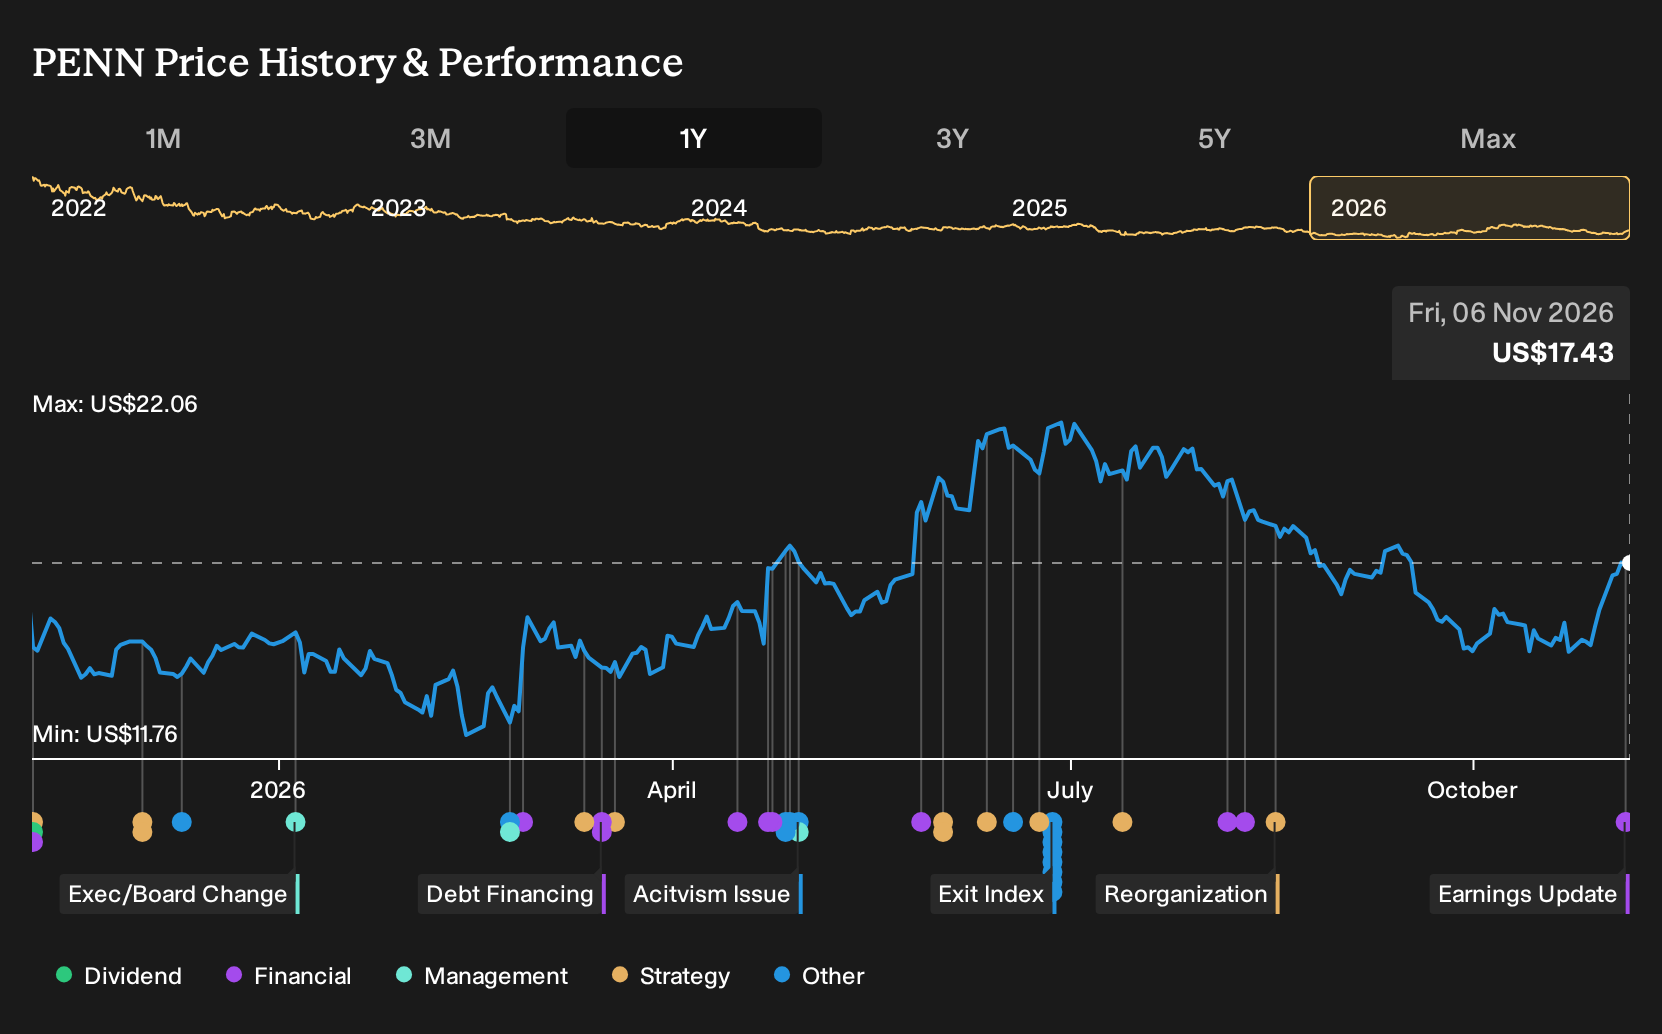
- PENN Entertainment reported third quarter 2026 revenue of US$1.84b and net income of US$33 million, compared with a loss in the prior year, and raised full year retail guidance after record casino takings and lower interactive losses.
- The shift from a large prior year loss to profitability, alongside management’s focus on debt reduction and potential Texas and Georgia expansion, suggests a business increasingly driven by existing property performance rather than heavy promotional spending.
- We will now look at how PENN Entertainment’s investment narrative could evolve as raised retail guidance influences expectations for the core casino business.
Scan how PENN Entertainment’s move back into profitability compares with peers by reviewing the curated 36 high quality undervalued stocks that may be pricing in stronger balance sheets and steadier cash flows.
PENN Entertainment Investment Narrative Recap
PENN Entertainment now asks shareholders to believe that a steady retail casino base and a smaller, more disciplined interactive arm can support consistent profitability. The latest quarter shows the business earning US$33 million of net income with record retail revenue and a narrower digital loss. The key near term swing factor is execution on retail properties and keeping promotional intensity in check.
The biggest current risk remains execution and competition in interactive, alongside tax and regulatory pressure on both sides of the business. Management’s raised retail guidance and reaffirmed path to digital profitability change expectations but do not remove exposure to new supply in weaker markets or the company’s elevated leverage.
The clearest tie back to this earnings release is PENN Entertainment raising full year 2026 retail revenue and adjusted EBITDA guidance while reiterating that interactive is targeted to reach adjusted EBITDA profitability in Q4 2026 and for the full year 2027. That links the current profit print directly to how investors think about the next 12 to 18 months.
For catalysts, that guidance makes the timing of any interactive breakeven and ongoing debt reduction the key things to watch. If the digital unit holds its path to profitability while retail properties maintain record level performance, it would support management’s focus on deleveraging before considering buybacks. Any stumble on these execution goals would quickly refocus attention on risk around regulation, competition and funding costs.
PENN Entertainment's narrative projects US$8.3b revenue and US$466.8 million earnings by 2029. This implies 4.9% yearly revenue growth and an earnings swing of about US$1.37b from current earnings of a US$906.7 million loss.
Uncover why PENN Entertainment's fair value indicates a 40% potential upside to its current price before that discount gap closes.
Exploring Other Perspectives
Some of the lowest PENN Entertainment analysts focus on a different catalyst. They worry that aggressive online promotions could keep interactive profits muted. Before this earnings beat, that group was modeling only 2.4% annual revenue growth and about US$302.9 million of 2029 earnings. You can weigh those cautious assumptions against today’s stronger headline results.
Explore 4 other PENN Entertainment fair value estimates, including one that suggests it could be worth just $23.37!
Form Your Own Verdict
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your PENN Entertainment research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for PENN Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PENN Entertainment's overall financial health at a glance.
Looking For More PENN Entertainment Sized Investment Ideas?
If PENN Entertainment has sharpened your focus on quality and risk, it can be useful to line it up against other candidates side by side. Use the Simply Wall St Screener to scan wider markets, compare fundamentals in seconds, and build a watchlist that actually reflects how you want to invest.
- If you want income to do more of the heavy lifting, check out a curated pool of dependable payers through 7 dividend fortresses.
- If resilience matters most, filter for companies that pair sturdy finances with measured risk using the 31 resilient stocks with low risk scores.
- If you prefer to back future compounders early, broaden your search with a 19 high quality undiscovered gems that may not yet be widely followed by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com