


EN
Does Raised Revenue Guidance Change The Bull Case For Garmin Stock (GRMN)?
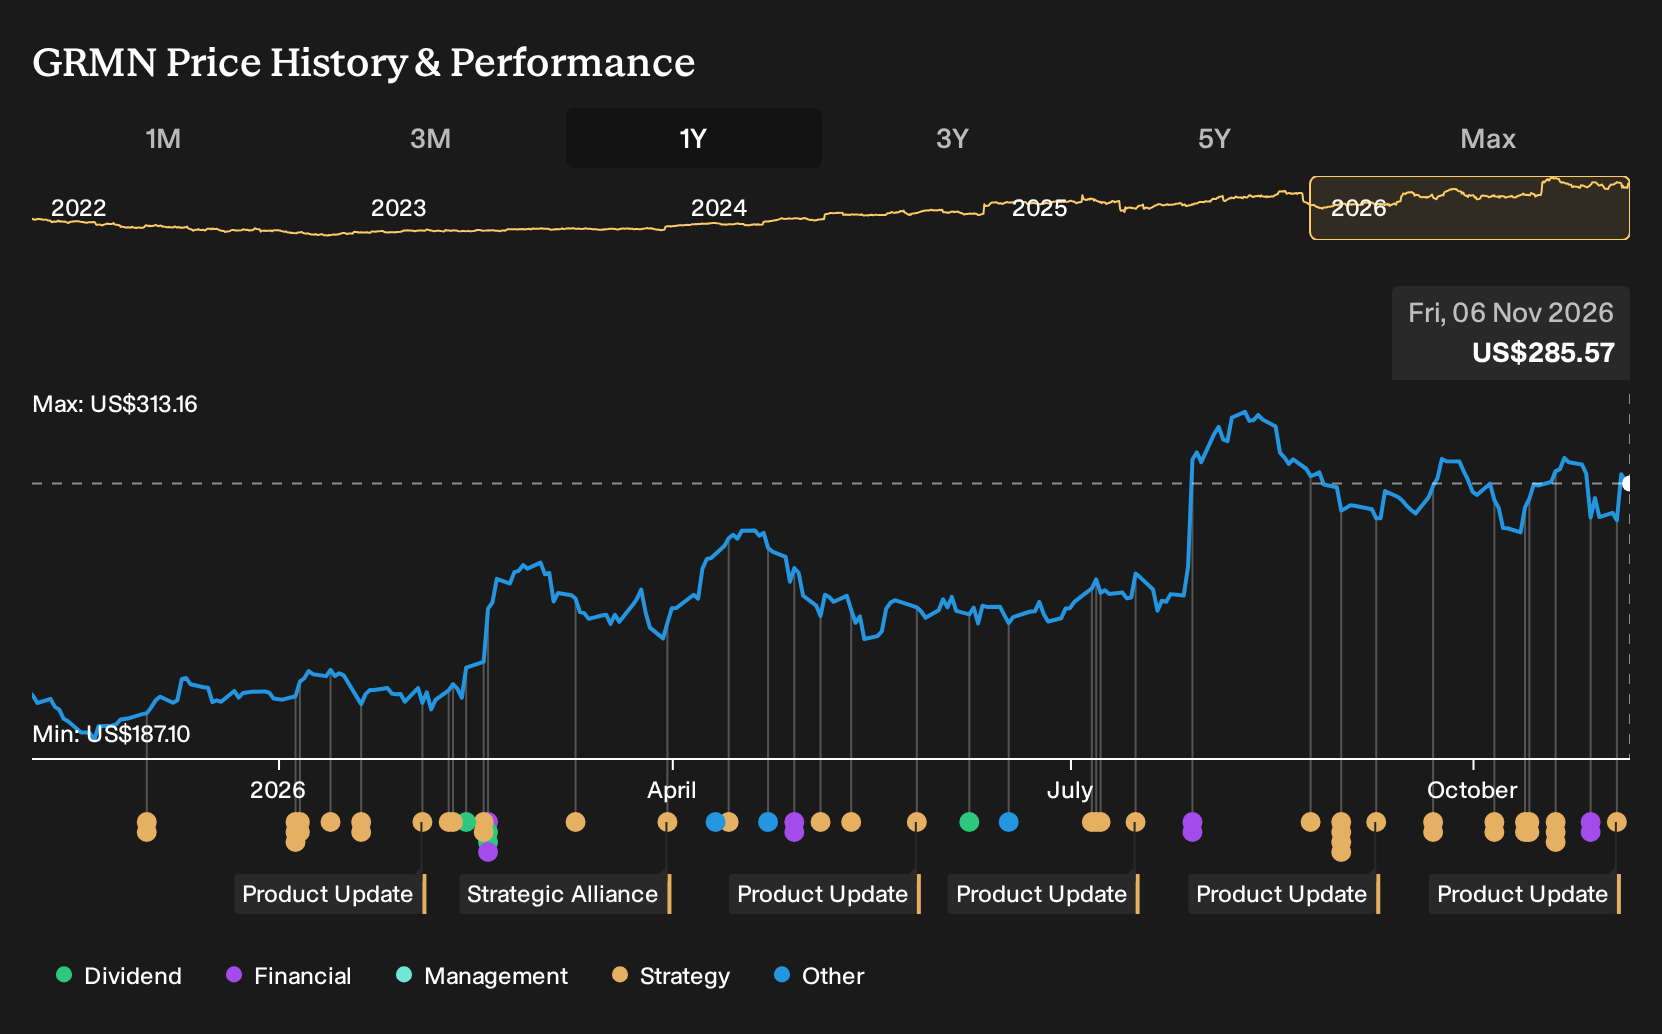
- Garmin reported third quarter 2026 sales of US$1,986.08 million and net income of US$541.66 million, then raised full year revenue guidance to about US$8.15 billion alongside ongoing share repurchases.
- The launch of the Descent X10 dive computer, built with recycled ocean bound plastics and backed by the Garmin Dive app ecosystem, highlights how Garmin connects new hardware directly to higher margin software and services.
- The focus now turns to how Garmin's stronger earnings guidance, supported by recent quarterly results, may influence the existing investment narrative.
Scan beyond Garmin to see how other hardware plus software specialists are priced and growing by checking a curated list of 19 high quality undiscovered gems in similar niches.
Garmin Investment Narrative Recap
To own Garmin, you need to be comfortable with a hardware plus services model in which wearables, outdoor devices and aviation systems feed higher margin software like Garmin Connect and Garmin Dive. The raised 2026 revenue guidance to about US$8.15b points to management confidence in current demand rather than a reset of the long term story.
The near term swing factor is execution in Fitness and services, while Outdoor softness, expected Auto OEM pressure in late 2026 and rising memory costs sit on the other side of the scale. Recent results and guidance support the catalyst, but they do not remove those operating risks.
The most relevant fresh data point is the third quarter 2026 update. Garmin reported US$1,986.08m of sales and US$541.66m of net income, with basic EPS from continuing operations of US$2.81, and raised full year revenue guidance to about US$8.15b, backed by ongoing share repurchases.
For you, that ties directly into the core catalyst. The business is signaling that Fitness, services and newer devices like Descent X10 are supporting the profit base at the same time Outdoor and Auto OEM face known headwinds and component costs are expected to rise into 2027, which keeps execution risk very real.
Garmin's current analyst narrative points to forecast revenues of US$10.0b and earnings of US$2.3b by 2029, built on expected yearly top line expansion of 9.1% and an earnings increase of about US$0.4b from roughly US$1.9b today.
Uncover why Garmin's fair value indicates a 6% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate angle to watch is how bullish analysts viewed Garmin’s capacity expansion even before Descent X10 arrived. They were working off revenue reaching about US$11.3b and earnings of US$3.0b by 2029, far above consensus. Those forecasts did not factor in this product news, so opinions could shift sharply.
Explore 4 other Garmin fair value estimates, including one that suggests as much as 30% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A useful starting point for your Garmin research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Garmin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Garmin's overall financial profile at a glance.
Looking for more investment ideas beyond Garmin?
Once you have a view on Garmin, it can help to cross check that thesis against other listed companies with different strengths and risk profiles.
- For investors hunting for stability first and returns second, start with a 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If reliable income is the priority, scan through a 7 dividend fortresses that focus on higher yields with an eye on sustainability.
- To widen the opportunity set beyond well known tickers, review a 19 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com