


EN
3 Stocks Watching The Data Center Water Fight In The US
Data centers just crashed into politics, and water sits in the crosshairs. With new rules and local pushback reshaping where and how hyperscalers expand, the quiet specialists that help heavy users recycle and treat industrial water could face very different demand patterns. This piece walks through three US industrial water management stocks exposed to that story and explains why their link to AI infrastructure might be relevant to portfolio decisions today.
The three tickers in this piece are only a sample, and the full screen on Simply Wall St surfaced 15 more industrial water management and recycling providers with equally compelling narratives that are not covered here. To identify and analyze the highest conviction industrial water plays right now, head straight to the Industrial Water Management and Recycling Providers screener.
Onterris (ONT)
Onterris fits within the Industrial Water Management and Recycling theme, combining consulting, treatment, and lab testing to help industrial and infrastructure clients address stricter water and contamination regulations tied to projects such as data centers and energy assets.
Onterris, Inc. has a market cap of about $770 million.
"Onterris is intentionally reducing lower margin pass through work from roughly one quarter of revenue to around or below 20% in 2026, which could shift a larger share of revenue into higher margin own staff projects and support a richer mix for EBITDA and earnings power."
The key variable is how this shift in Onterris’ focus ultimately affects its long term profitability.
That profitability question is exactly what the full narrative for Onterris unpacks, tying Onterris’ mix shift to where recurring demand, pricing power, and execution risk may be quietly accelerating.

MasTec (MTZ)
MasTec touches the Industrial Water Management and Recycling theme through the heavy infrastructure it builds for utilities, pipelines, and data center campuses. Its scale in power delivery and clean energy projects makes it one of the larger integrated engineering contractors tied to that story.
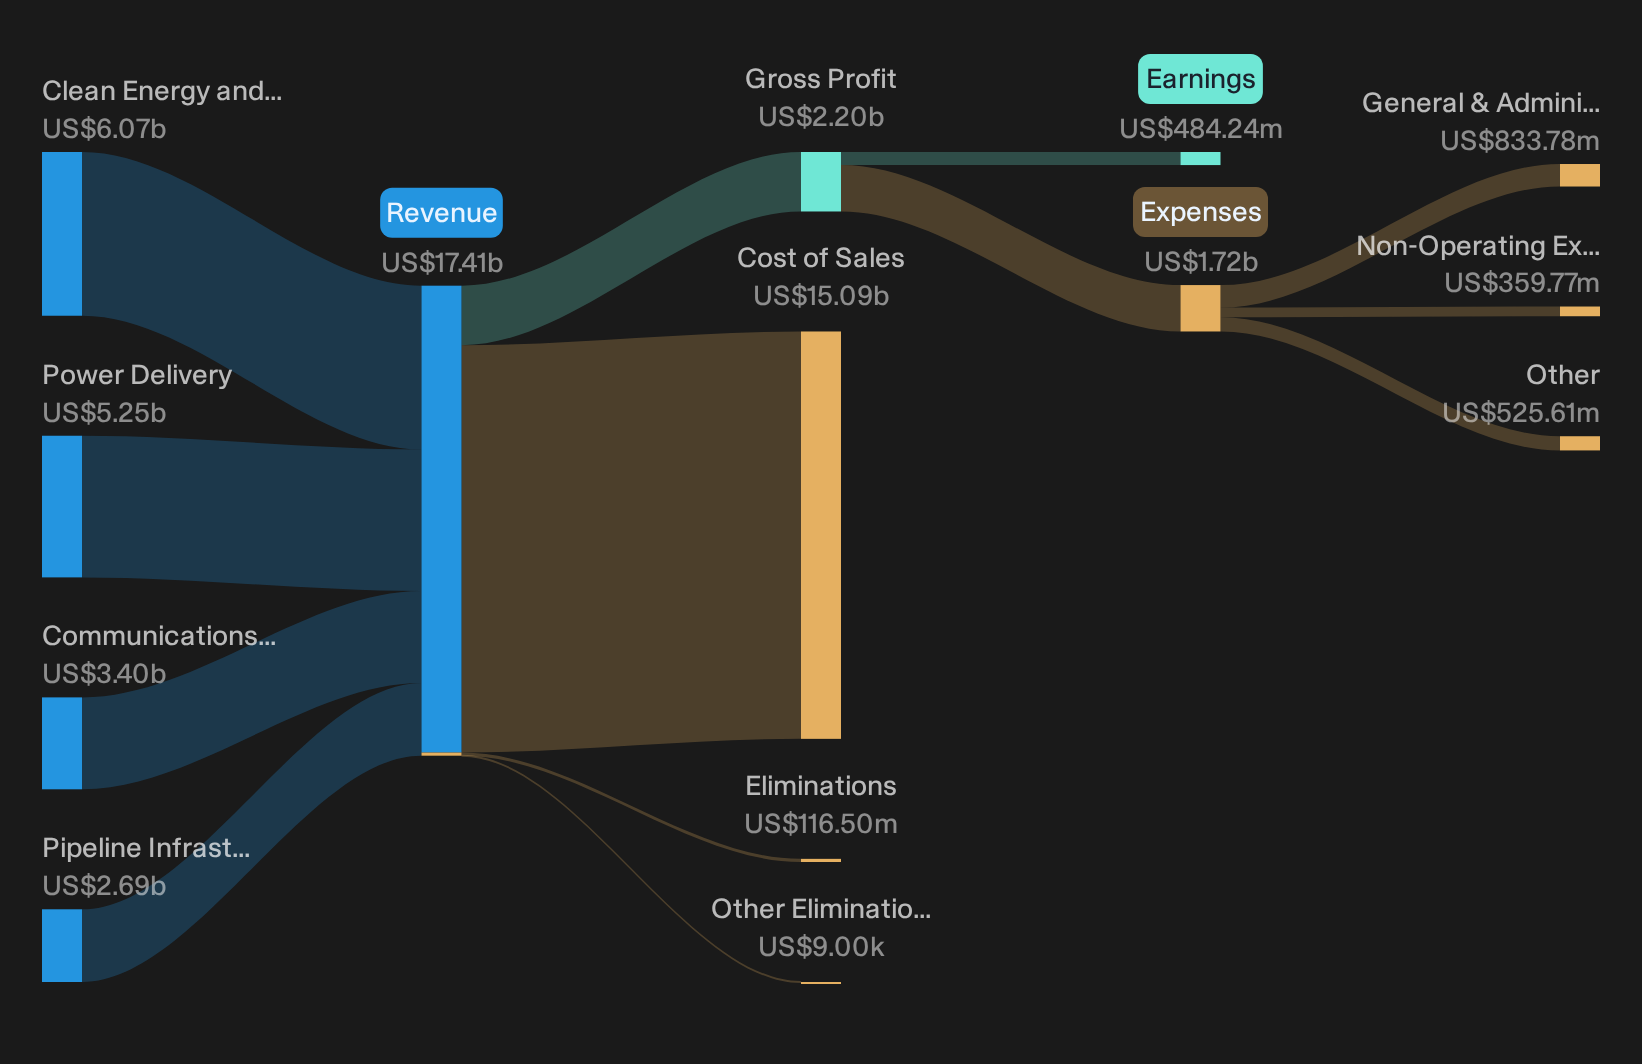
MasTec, an infrastructure engineering and construction specialist for communications, energy, utilities, transport, and water, generated about US$6.1b from Clean Energy and Infrastructure, US$5.2b from Power Delivery, US$3.4b from Communications, and US$2.7b from Pipeline Infrastructure, with a market value near US$13.8b.
For investors tracking data center and utility buildouts, MasTec offers broad exposure to the plumbing behind AI compute, where permitting, water use, and grid constraints are starting to bite.
"Although MasTec highlights record backlog tied to AI and cloud related data center work, there is a risk that customers slow or resize these projects as power availability, permitting or technology choices evolve, which could leave MasTec with underutilized capacity and pressure future revenue and EBITDA if awards are delayed or repriced."
What happens to MasTec’s earnings profile if that single bottleneck on large complex jobs quietly shifts how project dollars are released?
If that release pattern matters to you, the full narrative for MasTec shows where MasTec’s backlog risk could be masking accelerating long term earnings power.
Westlake (WLK)
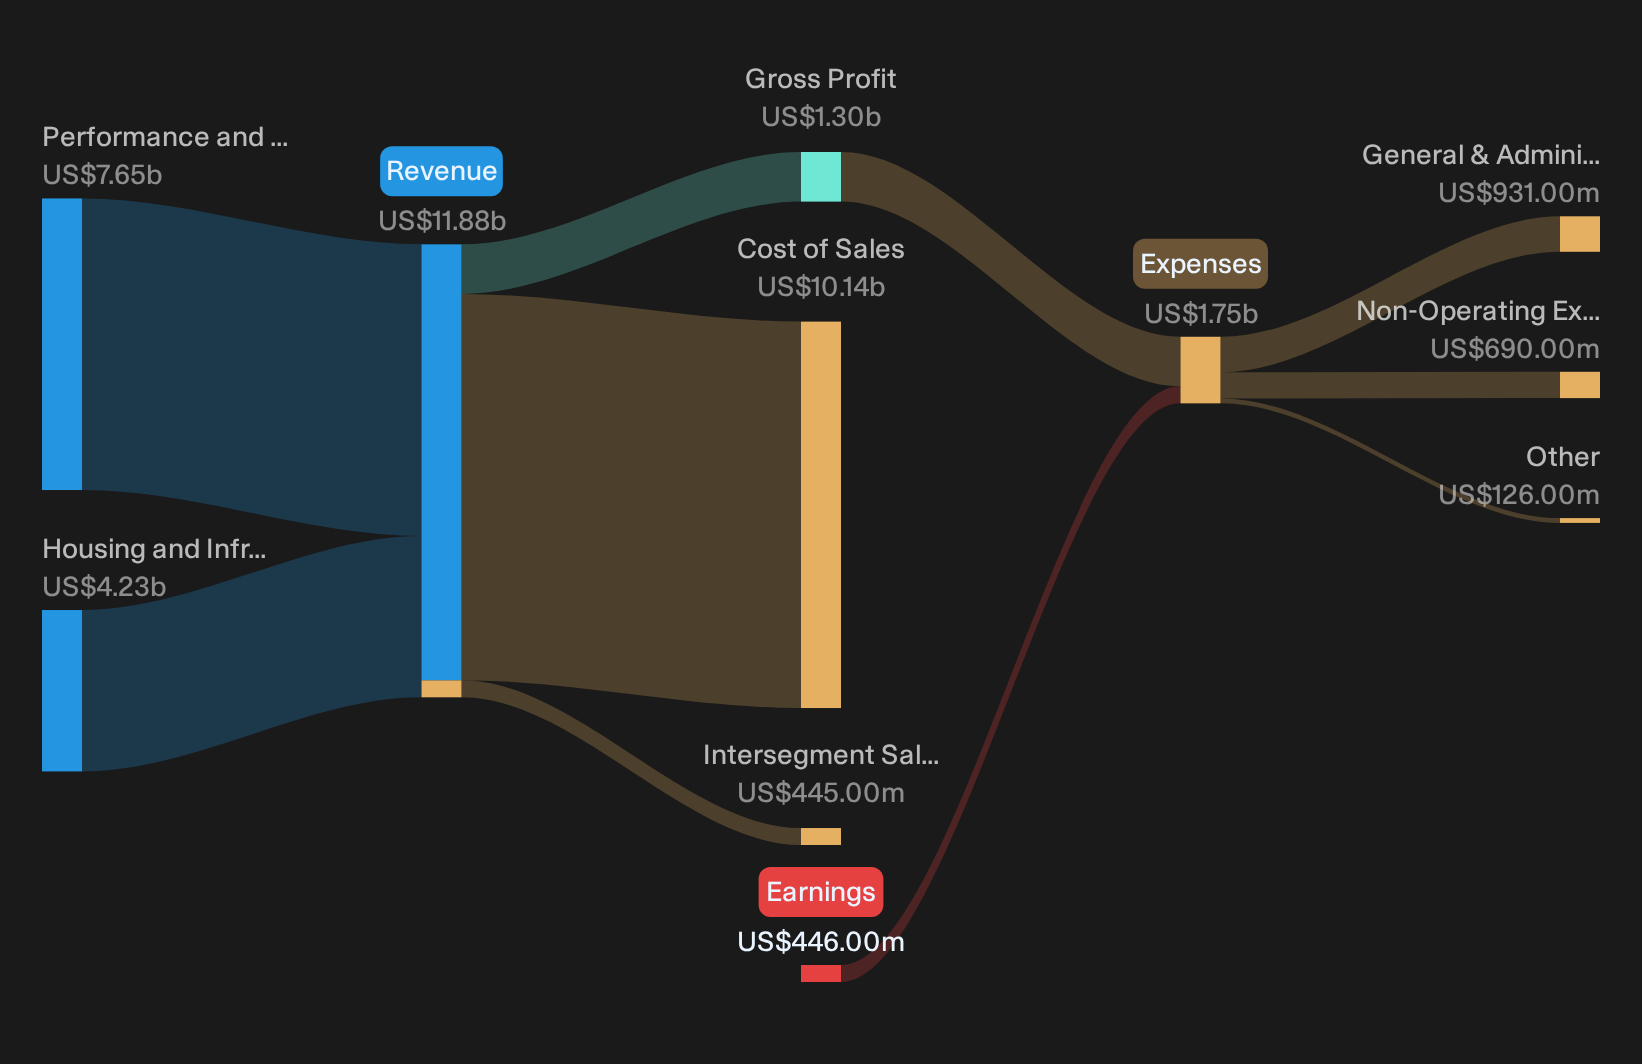
Westlake is a chemicals and building products manufacturer whose PVC pipes, fittings and compounds link it indirectly to industrial water and broader infrastructure work, with about US$7.6b from Performance and Essential Materials and US$4.2b from Housing and Infrastructure Products, and a market value near US$8.1b.
For investors thinking about how data center pushback might redirect capital toward basic infrastructure, Westlake offers a different angle on the theme through the materials that carry and protect industrial water rather than the treatment technologies themselves.
"The multi year increase in municipal infrastructure spending in the U.S., fueled by public investment and ongoing underspend in water systems, is still supporting long term demand for Westlake HIP pipe and fittings. This provides a structural underpin to volumes and revenue even when residential construction is softer."
What matters now is how one quiet shift in where those infrastructure dollars land ultimately feeds through to pricing power and margins.
That is where the quiet shift becomes interesting, and the full narrative for Westlake shows how Westlake’s water exposure could be masking accelerating earnings power and underrated resilience.
Curious About Alternatives You Might Be Missing
Fresh ideas tend to move first, and the quiet setups often catch a breakout before the crowd even looks. Momentum can change quickly, so scan these under the radar lists while it matters and consider potential opportunities early.
- Look for early-stage momentum where balance sheets already carry real weight by scanning the 19 high quality undiscovered gems curated for quality over hype.
- Follow cash-generating AI companies before sentiment shifts by reviewing the 40 profitable AI stocks that aren't just burning cash that filters out heavy cash burners.
- Explore durable cash flows that may support payouts in different market conditions by using the 7 dividend fortresses built around higher yield resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com