


EN
Will DOE Recycling Award Change Eastman Chemical (EMN) Narrative
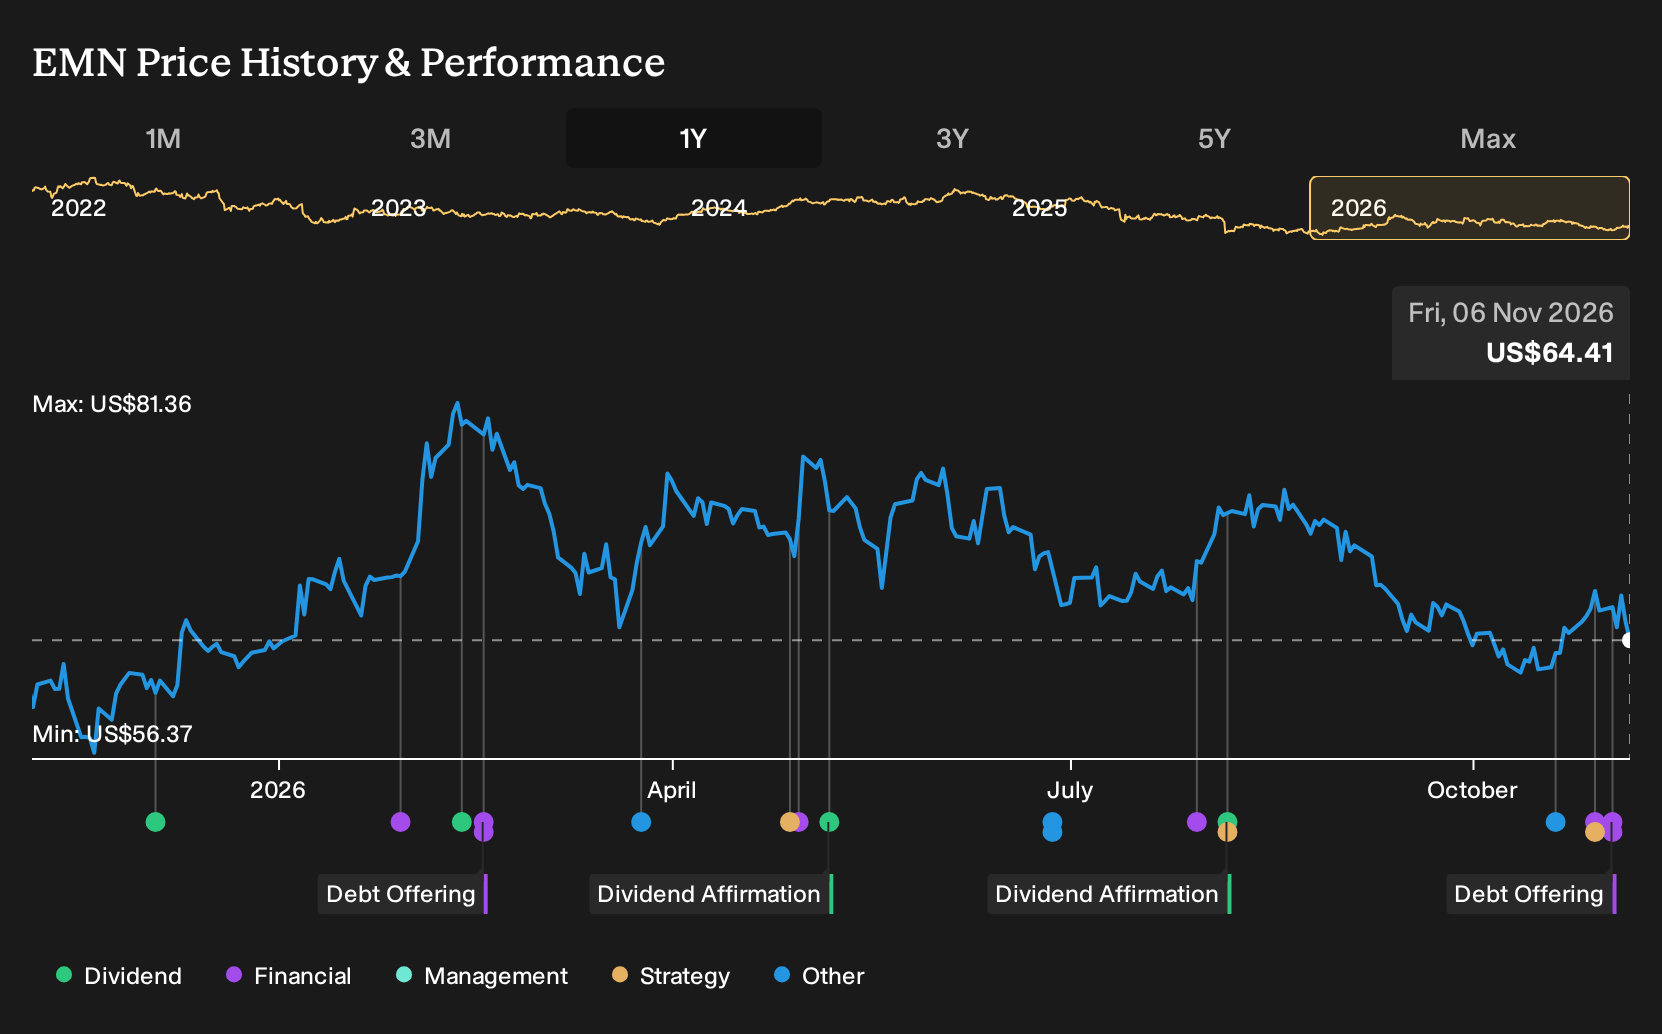
- Eastman Chemical reported third quarter 2026 sales of US$2,385 million and net income of US$252 million, and completed a US$299.652 million fixed rate bond offering with 5.500% notes due 2030.
- The reinstated US$375 million U.S. Department of Energy award, focused on methanolysis based plastics recycling and Kingsport capacity expansion, supports Eastman Chemical’s push into higher value recycled materials.
- We will now examine how Eastman Chemical’s investment narrative is affected by the stronger earnings results and reinstated Department of Energy funding.
Scan how Eastman Chemical’s recycling push and bond issue compare with other potential opportunities by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
Eastman Chemical Investment Narrative Recap
For a shareholder in Eastman Chemical, the core belief is that specialty materials and circular recycling can offset slower, more cyclical areas like Fibers and commodity intermediates. The recent third quarter, with US$2,385 million of sales and US$252 million of net income, points to an operating base that currently supports this mix shift story.
The key short term catalyst is execution on methanolysis capacity and cost savings, together with efforts to keep Chemical Intermediates earnings from slipping if feedstock spreads soften. The biggest risk remains exposure to global trade friction and lower cost producers, which could pressure pricing power and margins. The bond deal does not materially change that operational balance.
The most relevant update is the reinstated US$375 million U.S. Department of Energy award tied to Eastman Chemical’s methanolysis based recycling build out and Kingsport debottlenecking. That funding sits directly on top of the circular plastics thesis that many investors watch as a potential earnings mix upgrade over time.
Planned Kingsport improvements and milestone based steps toward a possible second U.S. methanolysis facility provide concrete levers to track for future catalysts, from higher Renew related revenue to better asset utilization. Execution risk remains, especially around timing, customer adoption and integration of restarted recycling assets into a reliable PET supply chain.
Eastman Chemical's narrative projects US$9.4b revenue and US$847.4 million earnings by 2029. This would require 1.1% yearly revenue growth and about US$222 million earnings increase from US$625.0 million today.
Uncover why Eastman Chemical's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Eastman Chemical’s recycling push as the key swing factor. Before this news, their models were built around revenue of about US$10.3b and earnings near US$909.1 million by 2029. You can compare that upbeat view with more cautious forecasts and decide which assumptions feel closer to your own.
Explore 3 other Eastman Chemical fair value estimates, including one that suggests as much as 117% potential increase from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eastman Chemical research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eastman Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eastman Chemical's overall financial health at a glance.
Looking for more investment ideas beyond Eastman Chemical?
If the Eastman Chemical story has sharpened your thinking about risk, balance sheets and long term earnings power, it can help to line it up against a wider field of potential opportunities using the Simply Wall St Screener.
- Focus on financial strength first and review a curated list of solid balance sheet and fundamentals (25 results) to compare companies with sturdier balance sheets to what you see at Eastman Chemical.
- If value is your priority, scan a wider universe of 36 high quality undervalued stocks that might suit a patient, price conscious approach.
- For investors who care most about consistent income, compare Eastman Chemical with a set of 7 dividend fortresses that aim to pair higher yields with resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com