


EN
How Investors May Respond To AGCO (AGCO) CORE Engine Debut
- AGCO Power’s CORE engine family, including the award winning CORE75 and CORE80, has been rolled out into new Massey Ferguson and Valtra tractors and shown at recent industry events, alongside a new hydraulic singulation chute for Massey Ferguson small square balers aimed at improving field efficiency.
- The combination of a fresh off highway engine platform and practical baler upgrades suggests that AGCO is prioritising fuel efficiency, workload productivity and emissions compliance in core product lines, rather than focusing only on adding digital features at the margin.
- We will now see how AGCO's investment narrative could be influenced by the CORE engine platform rollout into new tractor ranges.
Scan beyond AGCO to find other off highway machinery stocks with resilient fundamentals and potential operating leverage in a hand picked set of 19 high quality undiscovered gems
AGCO Investment Narrative Recap
For AGCO to make sense in a portfolio, you need to believe that heavy investment in CORE engines, PTx precision technology and premium brands can matter more than a soft equipment cycle and tariff headwinds. The big near term swing factor is whether weaker volumes and under absorption ease enough for the multi year cost and mix efforts to show up in cleaner margins.
The risk that looms largest is an extended period of subdued demand in North America and Brazil that keeps operating margin progress slow, especially with tariffs already compressing gross margin. The recent CORE rollout and baler upgrades do not materially change that near term demand and absorption picture on their own.
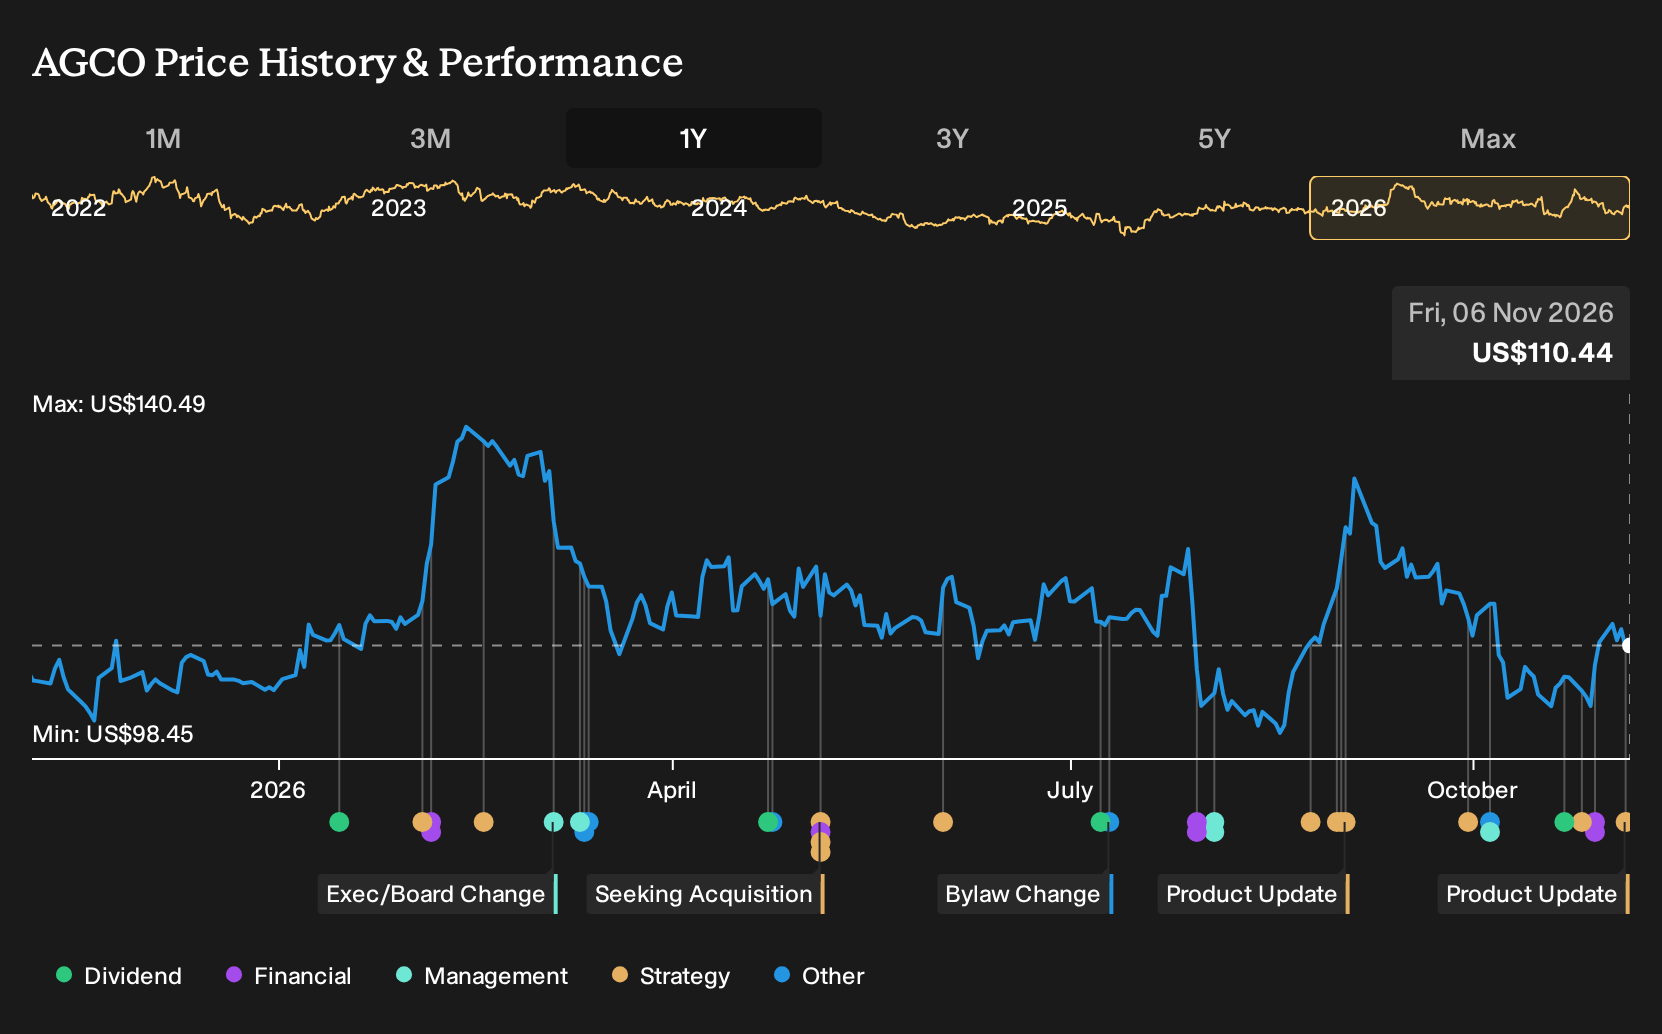
The earnings report from 29 October 2026 is the clearest counterweight to the product news. Sales for the quarter were US$2,262.5m, down from US$2,476.3m a year earlier, while net income fell from US$305.7m to US$51.7m. That type of compression keeps the focus squarely on execution, cost discipline and cash generation rather than headline technology launches.
Over the first nine months of 2026, sales of US$7,215.1m were close to the prior year but net income dropped from US$631.0m to US$183.9m, so earnings leverage is clearly under pressure. Against that backdrop, investors watching AGCO may treat the CORE engine and baler advances as longer term product assets. The more immediate catalyst is whether guidance of US$9.8b to US$10.0b of 2026 net sales proves achievable without further margin strain.
AGCO's current analyst narrative points to revenues of US$12.2b and earnings of US$871.8m by 2029. This outlook rests on 5.5% yearly top line growth and an earnings increase of about US$338m from the US$533.4m reported today.
Uncover how AGCO's fair value indicates a 12% potential upside to its current price before the discount to AGCO closes.
Exploring Other Perspectives
Some analysts frame the CORE engine rollout as a catalyst rather than a side story. The most optimistic forecasts already had AGCO reaching about US$12.5b of revenue and US$1.1b of earnings by 2029. Those estimates came before this product push, so you should expect opinions to shift and explore a few different narratives yourself.
Explore 3 other AGCO fair value estimates, including one that suggests as much as 43% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your AGCO research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AGCO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGCO's overall financial health at a glance.
Looking for more AGCO style investment ideas?
If AGCO's mix of real world machinery and longer term earnings potential appeals to you, it can help to line it up against other opportunities that share some of the same strengths. The Simply Wall St Screener can surface a wider field of candidates so you can compare balance sheets, income resilience and dividends side by side.
- For investors who want potential value combined with quality fundamentals, scan a curated set of 36 high quality undervalued stocks and see how they stack up against AGCO on metrics that matter to you.
- If income is a priority and you are weighing AGCO against stronger yield options, review a focused group of 7 dividend fortresses that pair higher payouts with fundamental checks.
- When capital preservation sits near the top of your list, broaden your watchlist with a targeted 31 resilient stocks with low risk scores to compare steadier profiles alongside AGCO.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com