


EN
Will Raised Earnings Outlook Change EPR Properties Stock Narrative
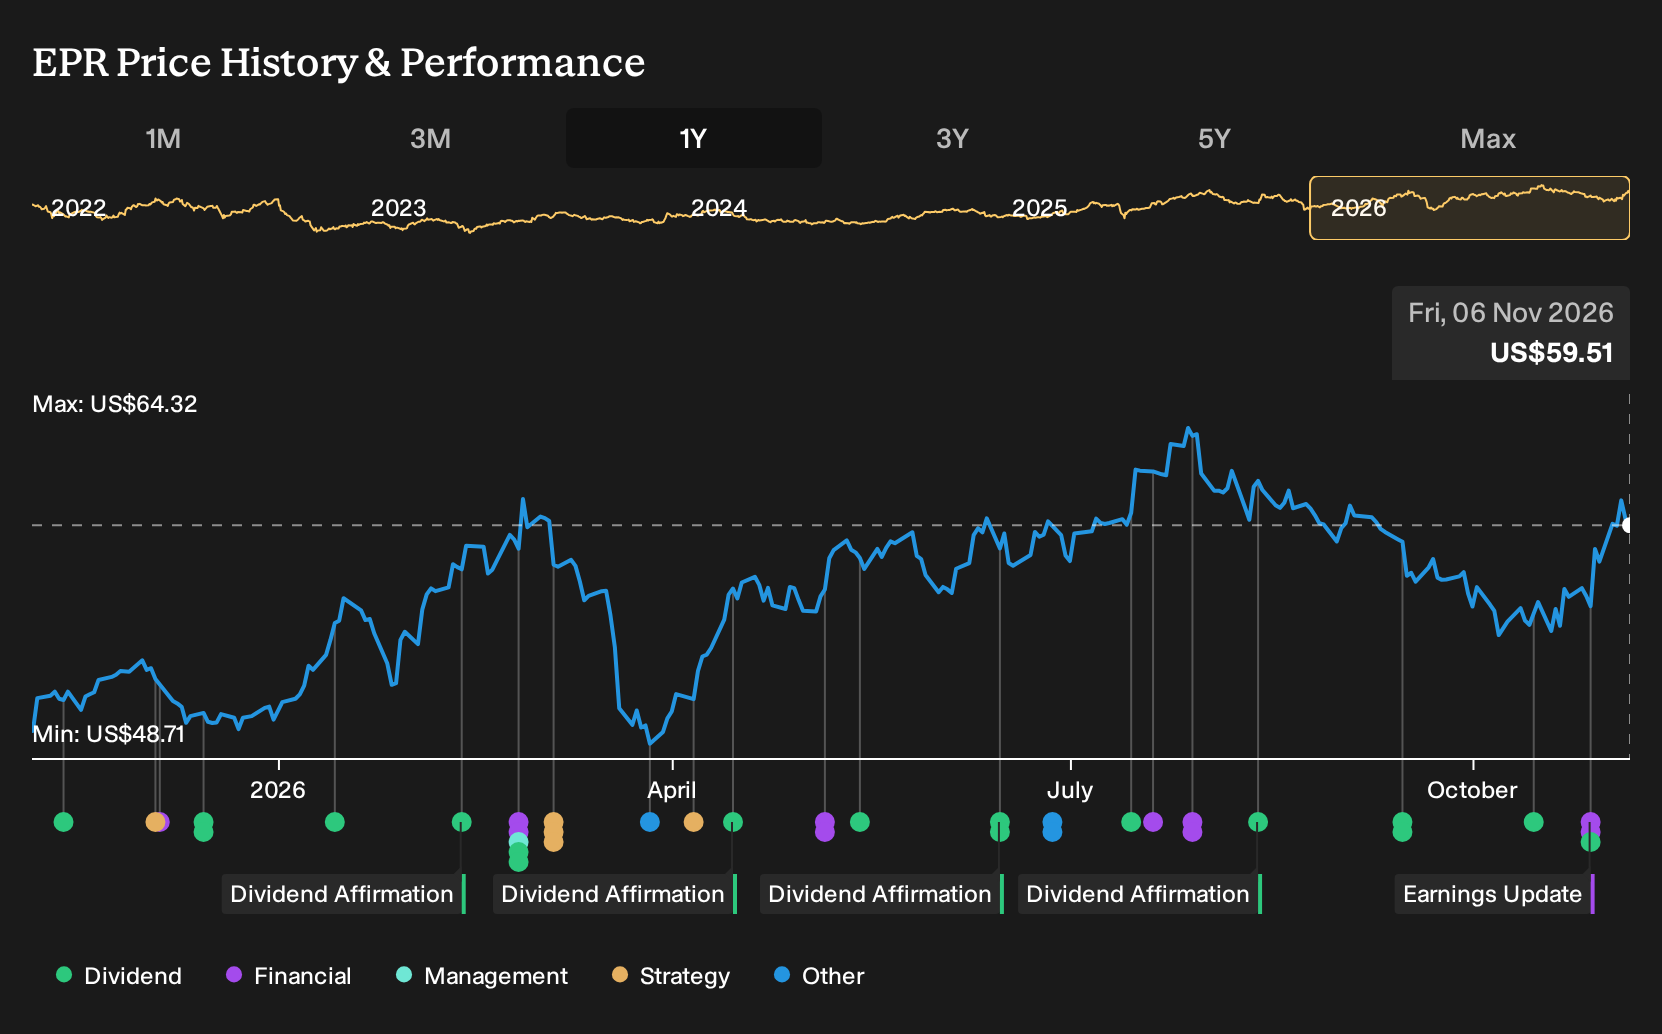
- EPR Properties reported third quarter 2026 revenue of US$204.1 million and net income of US$100.12 million, with higher basic and diluted earnings per share from continuing operations than a year earlier, and affirmed a higher monthly dividend of US$0.31 per share as of the October 27, 2026 board decision.
- The combination of stronger recent earnings, raised 2026 net income guidance per diluted share to US$3.41 to US$3.49, and a 5.1% uplift in the annualized dividend indicates that EPR Properties is using current operating performance to support both capital allocation plans and ongoing cash returns to investors.
- We will now assess how EPR Properties' raised 2026 earnings guidance could reshape the investment narrative that analysts had outlined previously.
EPR Properties Investment Narrative Recap
To own EPR Properties, you need to be comfortable with a focused bet on experiential real estate that depends on tenants whose revenue comes from discretionary consumer spending. The raised 2026 net income guidance suggests management currently sees enough earnings power to keep funding investment plans and the higher payout. In the near term, the key question is whether tenant health and rent coverage remain solid as capital is recycled away from theaters and education into broader experiential assets.
The biggest operational risk still sits with exposure to in-person entertainment if consumer time and money keep shifting toward at-home digital options, or if the economy softens and pressures discretionary spending. The latest earnings and guidance upgrade do not remove that risk. They indicate that current rent collections and margins are tracking well enough for EPR Properties to reaffirm its existing playbook.
The most relevant update for you as a shareholder is the higher 2026 net income guidance of US$3.41 to US$3.49 per diluted share compared with the prior range of US$3.03 to US$3.19. That guidance ties directly into the key catalyst analysts have focused on, which is EPR Properties using balance sheet flexibility to keep investing in experiential assets while maintaining rent coverage and funding its dividend.
This updated outlook sits alongside the 5.1% uplift in the annualized dividend to US$3.72 per share. Together, those two datapoints provide a clearer view of how current operations are supporting both reinvestment and cash distributions. The combination also sharpens the trade-off between reward and risk, given the company still relies on tenants whose revenue is sensitive to shifts in consumer behavior and any broader downturn.
EPR Properties' current analyst narrative points to forecast 2029 revenue of US$902.3 million and earnings of US$277.7 million, based on an annual revenue growth assumption of 6.9%. That earnings path implies an increase of about US$38.6 million from current earnings of US$239.1 million by 2029.
Discover why EPR Properties' fair value suggests a 9% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$64.68 to US$127.50 per share, which shows how far apart retail views on EPR Properties can be. When you layer that onto both higher 2026 earnings guidance and the dividend uplift, you get a mix of optimism and concern around tenant resilience and experiential spending.
Explore another EPR Properties fair value estimate, including one that suggests as much as 114% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EPR Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EPR Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EPR Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond EPR Properties?
If the EPR Properties story has sharpened your thinking about income, risk, and growth potential, it can help to widen the lens and compare it with other opportunities that share some of the same traits.
- If you like the idea of paying a lower price for strong fundamentals, scan a focused set of 36 high quality undervalued stocks that combine quality with potentially attractive entry points.
- If capital protection is front of mind, narrow your search to a 31 resilient stocks with low risk scores that screens for businesses with more resilient risk profiles.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (25 results) and focus on companies where debt and cash positions look more robust.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com